The One Definition That Decides If Your Homeowners Policy Actually Pay

Most owners size up a homeowners policy by looking at the numbers on it. Dwelling limit, liability limit, deductible. Those are the visible parts, and they're the parts everyone talks about at the kitchen table.
The part that actually decides whether the policy responds at all is a definition sitting near the front of the contract, in a section almost everyone skips because it looks like pure boilerplate.
Residence premises means the one family dwelling where you reside, or the unit you occupy in a two to four family dwelling, shown as the residence premises on your declarations page. The word doing all the work in that sentence is reside.
That one definition runs through the entire contract after that. Coverage A insures the dwelling on the residence premises. Coverage B is tied to it. Coverage D depends on it. On the liability side, the definition of insured location is built right on top of it too. Change the residency facts on the ground, and you haven't just weakened one clause somewhere in the middle of the document. You've unsettled the foundation the entire rest of the policy is sitting on.
The policy never actually defines reside
This is the part that ends up in courtrooms. The contract uses the word constantly and never once defines it, so courts have had to fill in the blank themselves, and they haven't filled it in the same way from state to state.
Some jurisdictions want actual physical occupancy at the time the policy was written, continuing straight through to the loss. Others look more at intent, and whether the owner kept a real ongoing connection to the property.
The fights cluster in pretty predictable places. Houses bought for an aging parent. Houses mid-renovation. Houses the owner quietly moved out of and never mentioned to anyone. And houses being rented out.
You really don't want to be the case that ends up settling this question for your state. Arguing over what reside actually means in front of a judge costs a lot more than the policy ever saved you in premium.
The policy does allow some rental, and that's exactly the trap
Here's where owners get a false sense of security, and honestly it's a reasonable one, because the contract genuinely does carve out some room for this.
Section II excludes liability arising out of a business. Business gets defined pretty broadly in there, covering a trade, profession, or occupation you're engaged in full time, part time, or even just occasionally, plus basically any other activity you're doing for money.
Then come the exceptions, and these are real ones. Renting the residence premises on an occasional basis, for use only as a residence, doesn't get treated as business. Neither does renting part of the place to a limited number of roomers or boarders, or renting part of it as an office or studio. A lot of policy editions also carve out any activity generating less than $2,000 in total compensation over the prior twelve months.
Hosts find that language, read it, and reasonably conclude they're fine. Two specific words undo that conclusion completely.
Occasional. The policy never defines this one either. A weekend rental twice a year is occasional by any reasonable read. Fifty stays across a season is a rental operation, plain and simple. You don't need a judge to tell you which one you're actually running.
Compensation. If your policy uses that $2,000 threshold, go check your actual revenue against it before you lean on that exception for anything. Most STR properties clear $2,000 in a single decent month, let alone across a whole year.
Where property coverage and liability coverage come apart
The duplex situation is worth understanding in detail, because it shows these are genuinely two separate questions with two completely separate answers.
Say you own a two unit building. You live upstairs. You rent the lower unit out nightly. A grease fire starts in the lower unit's kitchen, does $140,000 in damage, and a guest gets injured getting out.
On the property side, the residence premises test actually passes here. You occupy a unit in a two to four family dwelling shown right there on your declarations. You genuinely live there. The building qualifies for coverage.
On the liability side, that guest injury runs straight into the business exclusion instead. You're operating a nightly rental business out of the insured location, and no exception reaches an operation running at that scale.
So the exact same event produces a paid property claim and a denied liability claim, on the exact same policy. And the liability claim, of course, is the one with no real ceiling on how bad it can get.
There's a third piece to this too. Furniture, linens, appliances, and equipment you bought specifically to serve paying guests can fall under the business property limitation inside Coverage C, which is often capped at just a couple thousand dollars on premises. A fully furnished rental unit isn't personal property in anything like the way this form actually imagines it.
The second home problem
The other mismatch I see constantly is the seasonal property situation.
You use the cabin six weeks a year yourself and rent it out for thirty. Nobody resides there in any normal, everyday sense of that word. It's genuinely not your residence premises, and putting it on a standard homeowners form isn't really a coverage gap so much as a structural error from the start.
Secondary and seasonal dwellings need to be handled differently. Some carriers will schedule them onto your primary homeowners policy as a secondary location. Others require a completely separate policy, usually a dwelling form instead. Either way, the paperwork actually has to reflect what the property really is.
Go check your declarations page for whether the property is described as a primary residence, a secondary residence, or a seasonal dwelling. If that field is just blank, that's worth an actual phone call to your agent.
When this question actually gets asked
The residency question comes up at three specific moments, and only one of them is remotely convenient for you.
At application, when an occupancy question gets answered in about four seconds while you're signing a giant stack of closing paperwork and not thinking about any of this.
At renewal, when more carriers are asking again these days, sometimes backed by aerial imagery or listing site data they've pulled themselves.
At claim, when an adjuster asks who was actually staying in the house the night of the loss, and whether that person paid to be there. That's the expensive version of this question, by a wide margin.
How to actually check your own policy
Open your policy and find the Definitions section, usually sitting in the first few substantive pages. Read the definition of residence premises. Then read the definition of business. Then find the business exclusion in Section II and actually read the exceptions listed underneath it.
Three short passages, maybe ten minutes total. Then hold all of that up against your actual booking calendar from the last twelve months.
If your calendar and your contract are describing two different properties, you've just found the problem at the one point in time when it's still cheap and easy to fix.
What I'd actually ask my agent
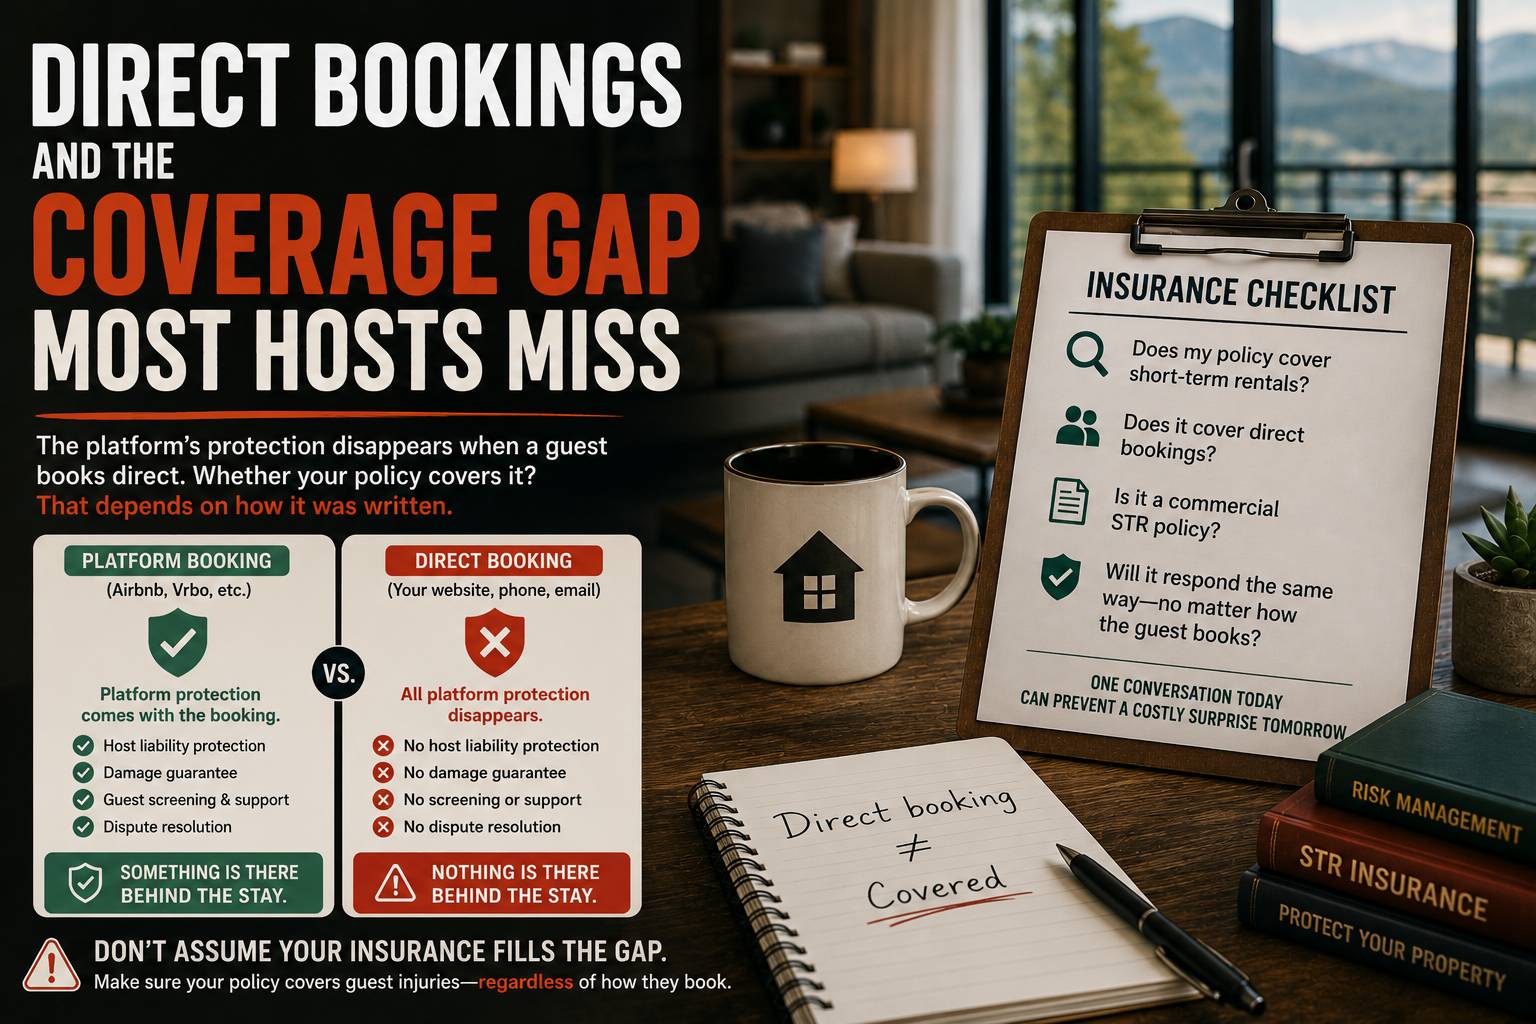
Ask whether the carrier itself has short term rental use recorded in the file for your property, and where exactly that shows up. Not whether your agent personally knows about it. Whether the actual file says so in writing.
Ask how the property is classified on your declarations page, primary, secondary, or seasonal, and whether that classification actually matches how you're using it today.
Ask directly what happens to the liability section if a paying guest gets injured on the property. If the answer contains the word probably anywhere in it, treat that as your actual answer.


Comments