Read Your Policy Backward

Most owners read a policy from the front. Coverage limits first, then the perils, then they just stop reading. The exclusions look like fine print stuck at the end, and everybody treats them accordingly, which is exactly the wrong instinct.
Try reading it the other direction instead. The insuring agreement tells you what the carrier is willing to talk about. The exclusions tell you what you actually bought.
On an open perils form this is even more true, because the entire promise baked into that form is that everything's covered unless it's specifically excluded. The exclusion list isn't some footnote to that promise. It's the actual definition of it.
They're not all sitting in one place
The first problem I run into constantly is that owners go looking for an exclusions page, find one, and assume they've now seen all of them. There are actually at least four different spots.
The Section I exclusions. This is the main property list. Earth movement, water damage, ordinance or law, power failure, neglect, intentional loss, war, nuclear hazard.
The limitations built directly into the perils section. On an open perils form, there's a second set of exclusions living inside the covered causes of loss itself, and it's incredibly easy to walk right past. Wear and tear, deterioration, mechanical breakdown, rust, mold, settling, vermin, animals owned by an insured, and constant seepage happening over weeks or months. These are actually the ones that matter most for rental property, and they're not printed alongside the other exclusions.
The Section II exclusions. This is the liability list. Business pursuits, intentional acts, motor vehicles, watercraft, and on a lot of current forms, communicable disease and controlled substances too.
The endorsements. Anything on your forms schedule with exclusion or limitation sitting right in the title amends everything listed above it. An endorsement added at your last renewal can quietly take away coverage the base form originally granted, and the base form still reads exactly the same way it always did.
There's a fifth spot too, and almost nobody counts it. The definitions section excludes things by narrowing them. When a policy defines residence premises as the place where you actually reside, it's just excluded every single property where you don't reside, without ever using the word exclusion once.
Read all the way to the end of the paragraph
Exclusions come stacked in layers. The exclusion itself, then exceptions to that exclusion, then sometimes an exception to the exception on top of that.
Water damage is the classic example of this. The exclusion sweeps out flood, surface water, and sewer or drain backup entirely. Then an exception comes along and restores coverage for a fire or explosion that results from that same excluded water event. Stop reading after the first sentence and you walk away with a materially wrong answer about what you're actually covered for.
The habit worth building here is simple. Read the exclusion, then keep reading until the numbering actually changes.
The clause that ends most arguments before they start
Near the top of the Section I exclusions, most forms have a sentence that reads like pure throat clearing and is actually the single most powerful piece of language in the entire contract.
It states that loss caused by the excluded events is excluded regardless of any other cause contributing to the loss, concurrently or in any sequence.
That's called the anti concurrent causation clause. It exists because policyholders kept arguing that when a covered cause and an excluded cause combine together, the covered one should be the thing that carries the claim. This language shuts that argument down completely. If an excluded cause shows up anywhere in the chain of events, the exclusion applies, full stop.
Courts in a small handful of states have limited how far this actually reaches. Most of the time though, it does exactly what it says it does.
What this actually looks like on a real loss
Picture three days of heavy rain. The ground is fully saturated. Water comes in through a window well and also through a hairline crack in the foundation. The sump pump runs until the power fails, and then it just stops working. Your cleaner walks in and finds four inches of standing water in a finished lower level. The restoration and rebuild estimate comes back at $52,000.
Three separate exclusions are all in play at the exact same time here. Surface water, excluded. Sump overflow, excluded unless somebody specifically bought that coverage back. Power failure occurring off premises, also excluded.
The instinct is to argue about the actual root cause. The pump would have held fine if the power had just stayed on. The anti concurrent causation clause closes that door before you ever get anywhere near it.
The fix for this costs almost nothing, but it has to happen before the storm, not after. Water backup and sump overflow coverage is usually a pretty small annual premium, often somewhere between fifty and a few hundred dollars depending on the limit and the carrier. Worth knowing it comes as a sublimit though, frequently $5,000 to $25,000. That's real money, and it's not the full $52,000. Buy it anyway, and also know exactly what it won't cover.
The exclusions that matter most on a rental specifically
Water, in all its various forms, produces the most denied claims by a wide margin. Flood is never in the policy to begin with. Backup and seepage are two completely separate problems with two separate answers.
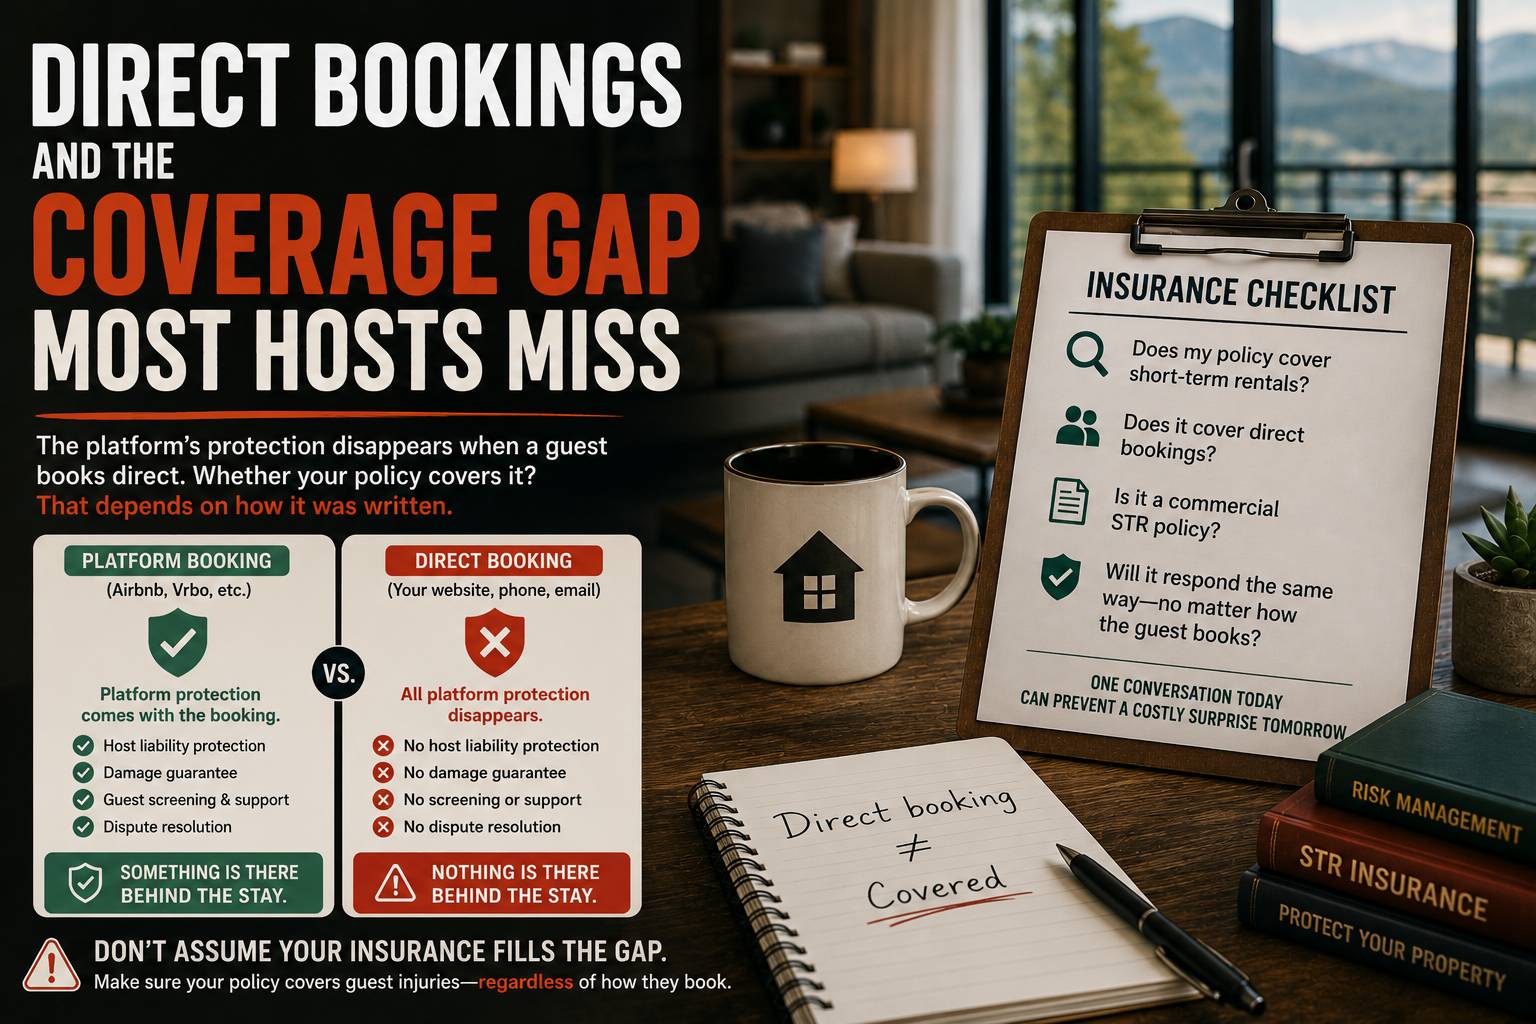
Business pursuits, on the liability side, produces the largest denied claims by dollar amount. That's the guest injury conversation right there.
Wear, tear, and neglect is the one owners find the least fair, and it's also the one carriers apply the most consistently of all of them. Insurance covers sudden accidental events. Deferred maintenance simply isn't an event.
Ordinance or law only shows up after a genuinely serious loss, when the rebuild has to meet current code and the policy ends up paying to replace something that technically wasn't there before.
Then there are a few exclusions specific to how rental properties actually get written. Vandalism caused by a tenant or occupant is excluded on a lot of forms, and that language reaches straight into guest damage. Theft is excluded or sharply limited on dwelling forms. Animal liability exclusions by breed show up on both admitted and program policies alike. And assault and battery is frequently excluded or sublimited on liability forms written for lodging risk specifically. Find that last one before you actually need it, not after.
Most of these can actually be bought back
This is the part that turns an exclusion list from a source of genuine anxiety into a straightforward shopping list instead.
Water backup and sump overflow is an endorsement. Ordinance or law is an endorsement too, usually sold as a percentage of Coverage A. Service line coverage handles the buried water or sewer line running between the street and your house. Equipment breakdown picks up mechanical failure, which the base form throws out entirely on its own. Flood requires an entirely separate policy, either through the NFIP or a private carrier.
None of these cost much relative to what they actually protect against. They go unpurchased simply because nobody ever sat down and read the exclusion that created the need for them in the first place.
How to actually read your own exclusions
Three passes through the document, about twenty minutes total.
First pass, read the entire Section I exclusion list straight through without stopping to overthink anything. You're just building a mental map at this point.
Second pass, go back and read only the exceptions this time, the sentences that start with language like this exclusion does not apply to. That's where coverage actually gets restored, and it's exactly where most people quit reading way too early.
Third pass, pull the forms schedule off your declarations page and find every single endorsement with exclusion or limitation sitting in the title. Read every one of those. They outrank everything written in the base form.
What I'd actually ask my agent
Ask which exclusions have already been bought back on your current policy, and ask for the answer as an actual list, not just a general reassurance that you're fine.
Ask exactly what water backup and sump overflow coverage costs and what limit is available to you. If it's not already on your policy, that's usually a same day fix once you ask.
Ask directly whether any exclusionary endorsements got added at your last renewal. Carriers tighten terms at renewal far more often than they ever cancel a policy outright, and renewal packets get filed away in a drawer without anybody actually reading them.


Comments