Hi everyone,
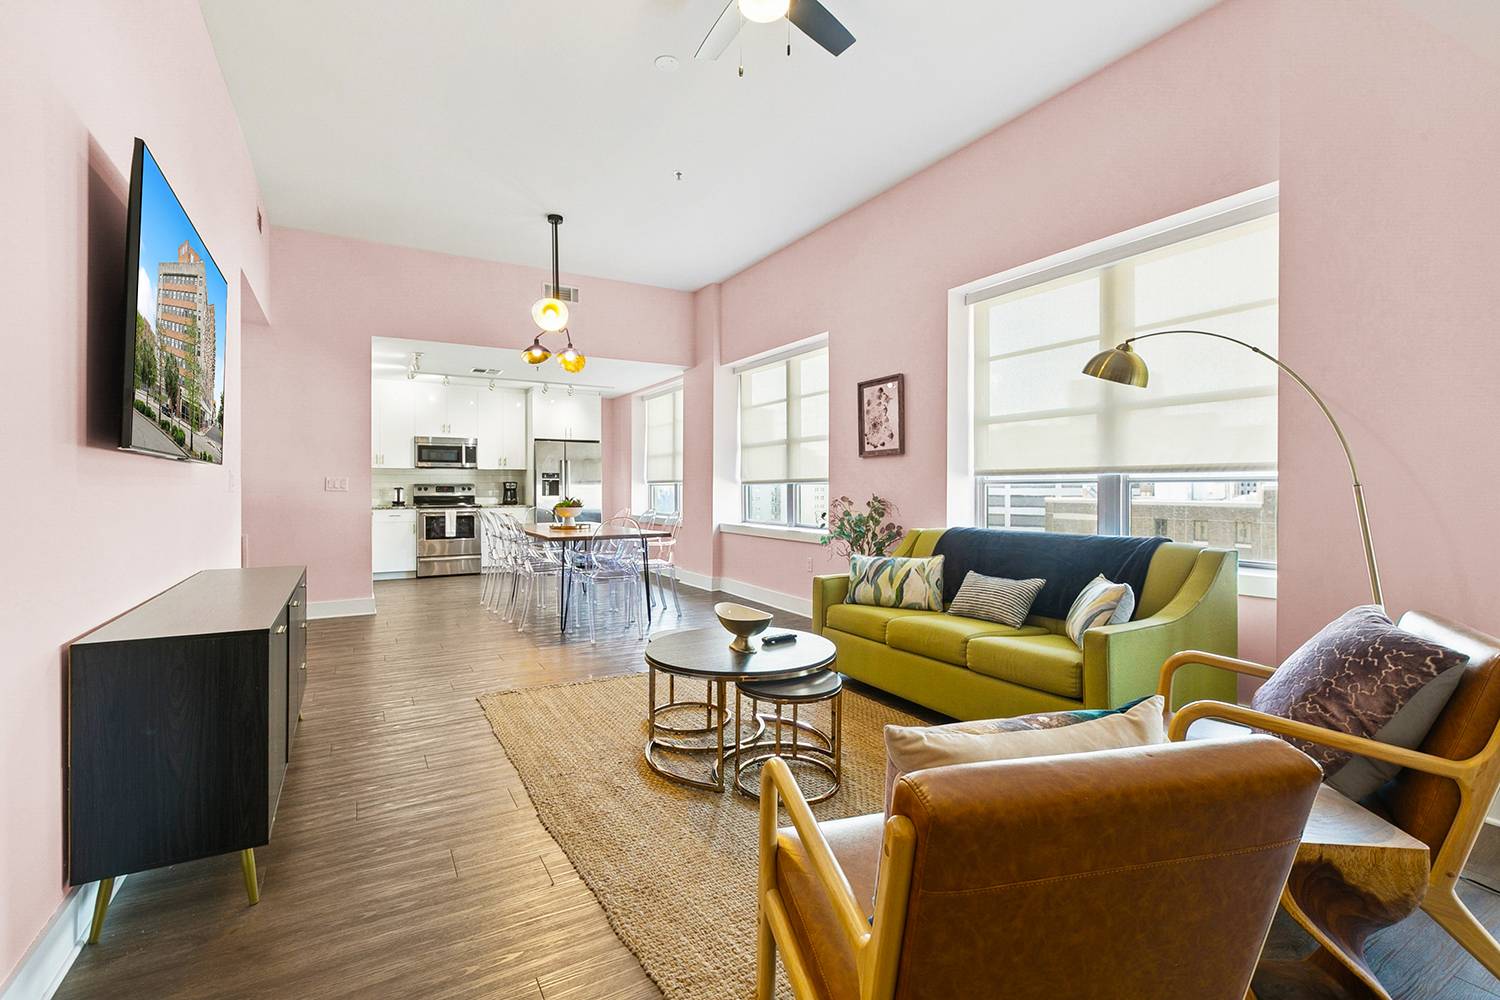
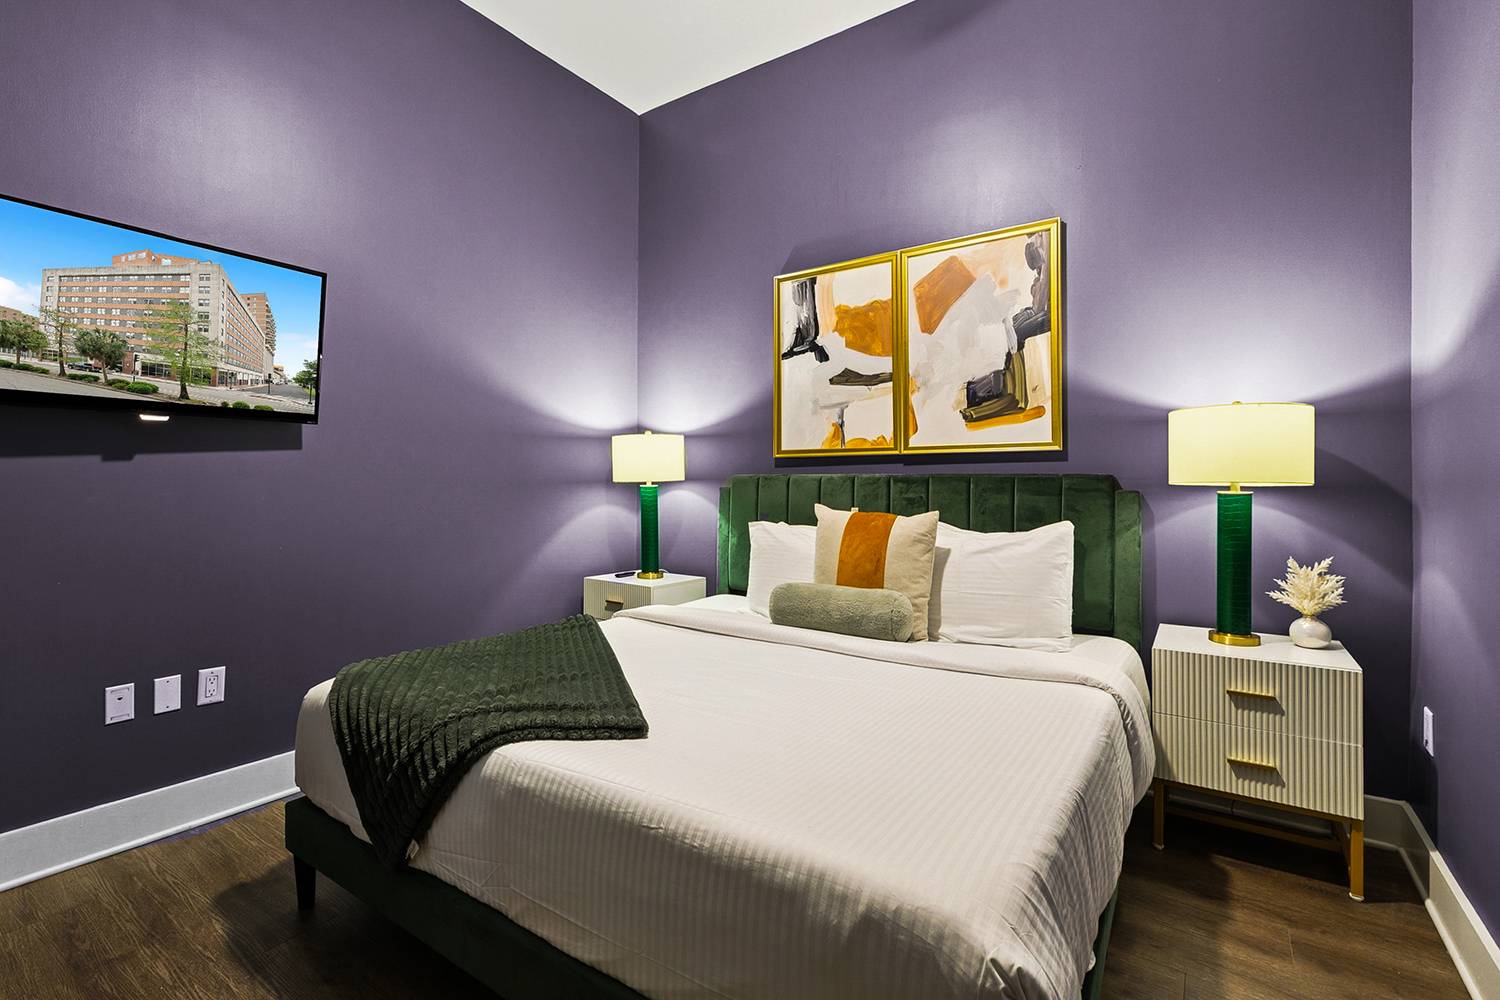
I’m representing a seller with a fully operational short-term rental in New Orleans and would appreciate feedback on pricing and overall deal quality.
One challenge has been comping this asset—there are very few buildings in New Orleans with a similar grandfathered hotel-style STR structure and consistent financials at this scale. Curious how others would approach valuation given limited direct comps.
Key Financials (2025):
• ~$77,400 gross income
• ~$60,900 net after management
• ~$31,200 net cash flow
• ~5.0% cap rate at $629K asking
Upside:
• Management fees reduced from 20% → 15%
• 2026 YTD revenue (through May): ~$34.8K
• Projected returns ~5.5%–6.0% with fee reduction
Property:
• 4 bed / 2 bath (sleeps 12)
• 1,437 sq ft
• CBD location
Highlights:
• Rare grandfathered hotel-style STR license (no individual permit required)
• Fully turnkey with onsite professional management
• Consistent, verifiable performance
Notes:
• HOA ~$14.8K/year
• Fully managed (no self-management allowed due to building structure)
Also recently listed on Rabbu to reach STR-focused buyers, but would value feedback here as well.
Curious to hear:
• Does ~$629K feel appropriately priced?
• How would you evaluate this vs other STR deals?
• What return would you target for something like this?
Sylvia, interesting deal. The biggest thing investors will probably look at here is the cap rate vs risk profile of STRs in New Orleans.
At ~$31K net cash flow on a $629K ask, you're around a 5% cap, which is fairly tight for most STR investors unless there's strong appreciation or a unique licensing advantage (which it sounds like this property has with the grandfathered hotel-style license).
A few things buyers will likely weigh:
• HOA at ~$14.8K/year is a big line item and limits flexibility
• Mandatory management also compresses returns since self-managing isn’t an option
• Regulatory risk in New Orleans STR markets tends to push investors to want a higher yield
That said, the grandfathered STR structure is a real asset because permitting in New Orleans has become much harder. For the right passive investor who wants a hands-off STR in the CBD, it could still make sense.
My guess is most investors comparing deals nationally would probably target closer to a 6–7% return to feel comfortable, unless they really value the turnkey aspect and licensing.
Curious if most of the interest you're getting is from local buyers or out-of-state STR investors?
Thanks for this — this is super helpful and aligns with a lot of what I’ve been seeing in conversations as well.
I’ve actually had a mix of both out-of-state and local interest, which surprised me a bit. I initially expected mostly buyers with ties to New Orleans, but a few of the inquiries have been from investors who have never been here and are specifically drawn to the hands-off structure.
For a smaller unit I have in the same building, I’m seeing more in-state buyers — typically those who understand the market more deeply and are looking at it through a combination of income + tax strategy + long-term hold.
We did have one offer that ultimately terminated during the due diligence period — the buyer was actively comparing multiple deals and mentioned circling back once he has capital freed up in April/May. His offer did come in below asking, which I think speaks directly to your point on yield expectations.
That’s kind of where I’m trying to pressure test things right now:
Do I adjust price to better align with that 6–7% return window most investors are targeting, or focus on getting this in front of a more niche buyer who values the specific advantages here?
Because I do think this sits in a slightly different category than a typical STR:
• The grandfathered hotel-style license removes a lot of regulatory friction
• It’s truly passive (which some investors are actively seeking)
• There’s potential upside with management fees dropping from 20% → 15%, which should push returns closer to the ~5.5–6% range
One thing I’ve been thinking through — and would love your take on — is upside through increased bookings.
While owners can’t self-manage, they can drive traffic (ads, direct marketing, etc.) to the management company’s booking platform. In theory, that could improve occupancy without changing the structure — but I’m not sure how much weight investors actually give to that kind of upside vs just underwriting current performance.
At a high level, I’m trying to figure out:
• Is this best positioned as a yield play (and priced accordingly)?
• Or as a “scarcity + ease” play for a more passive investor who values the licensing and turnkey nature?
Also — if you were trying to get this in front of the right buyer, where would you focus? (BiggerPockets, specific broker networks, STR investor groups, etc.)
Really appreciate the insight here — this has been one of the more helpful perspectives I’ve gotten.