Real Estate Agent · Member since 2023 · 3 posts · 0 votes
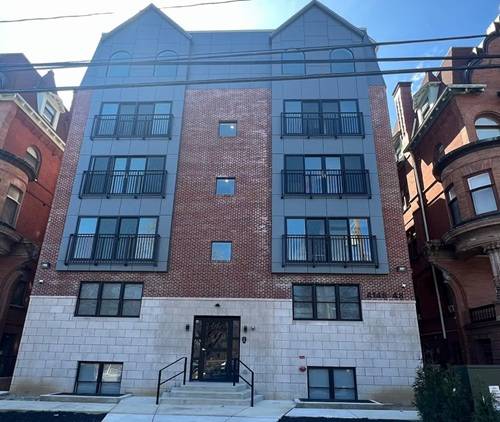
Team Money is proud to present 4146-48 Parkside Avenue, a newly constructed 28-unit multifamily investment located directly overlooking Fairmount Park.
Built in 2023, the property offers investors modern construction, immediate cash flow, and approximately seven years remaining on Philadelphia's original 10-year tax abatement, providing significant long-term tax savings.
Here are some highlights:
* Sales Price: $5,350,000
* 28-Unit Multifamily Asset
* In-Place NOI: $322,921
* Built in 2023
* Approximately 7 Years Remaining on the Original 10-Year Tax Abatement
* Directly Overlooking Fairmount Park
* Prime Parkside Location Near University City & Center City
Our streamlined 3‑Step Loan Approval Process makes funding fast and simple.
DOWN PAYMENT FUNDS:
* 10% down (through PhoneOps Funding)
* Gift funds allowed
* May qualify for downpayment assistance
* Down payment is not seasoned like most lender requirements
Call me today so we can start securing your loan approval immediately.
$322,921 NOI ÷ 28 units = ~$961/unit/month, or $26,910/month in total debt service capacity at true breakeven.
Here are the maximum loan amounts at 1.0x DSCR (debt service exactly equal to NOI), 30-year amortization:
$3,667,000 @ 8.0%
$3,849,000 @ 7.5%
$4,045,000 @ 7.0%
$4,257,000 @ 6.5%
$4,488,000 @ 6.0%
Whatever the loan doesn’t cover has to be down payment — real cash into the deal:
8.0% → $1,683,000 down (31%)
7.5% → $1,501,000 down (28%)
7.0% → $1,305,000 down (24%)
6.5% → $1,093,000 down (20%)
6.0% → $862,000 down (16%)
And that’s at 1.0x. Most lenders underwrite multifamily to 1.20–1.25x, so knock those loan amounts down another 20–25% and add it back to the cash column — call it $1.75M to $2.4M in equity depending on rate.
The part worth staring at: $5,350,000 on $322,921 NOI is a 6.04% cap. The loan constant on a 30-year am at 6% is 7.19%. That means negative leverage at every rate on that list — the debt costs more than the asset yields, which is precisely why the equity requirement is so heavy.
Where the deal gets interesting is the value-add window. If there's mobility over the next 6–12 months to improve the property and push rents, you're underwriting to a higher NOI at refinance. Re-appraise on the improved income, and you either pull cash out on the equity created or leave it in and keep the stronger cash flow. That's the path that makes a 2023-built asset with 7 years of abatement left pencil — not the day-one leverage.