Delinquency Data not Matching "My Gut"

Delinquency Data not Matching "My Gut"

Doug SmithPro Member
Lender · Tampa, FL · Member since 2013 · 2k+ posts · 2k+ votes

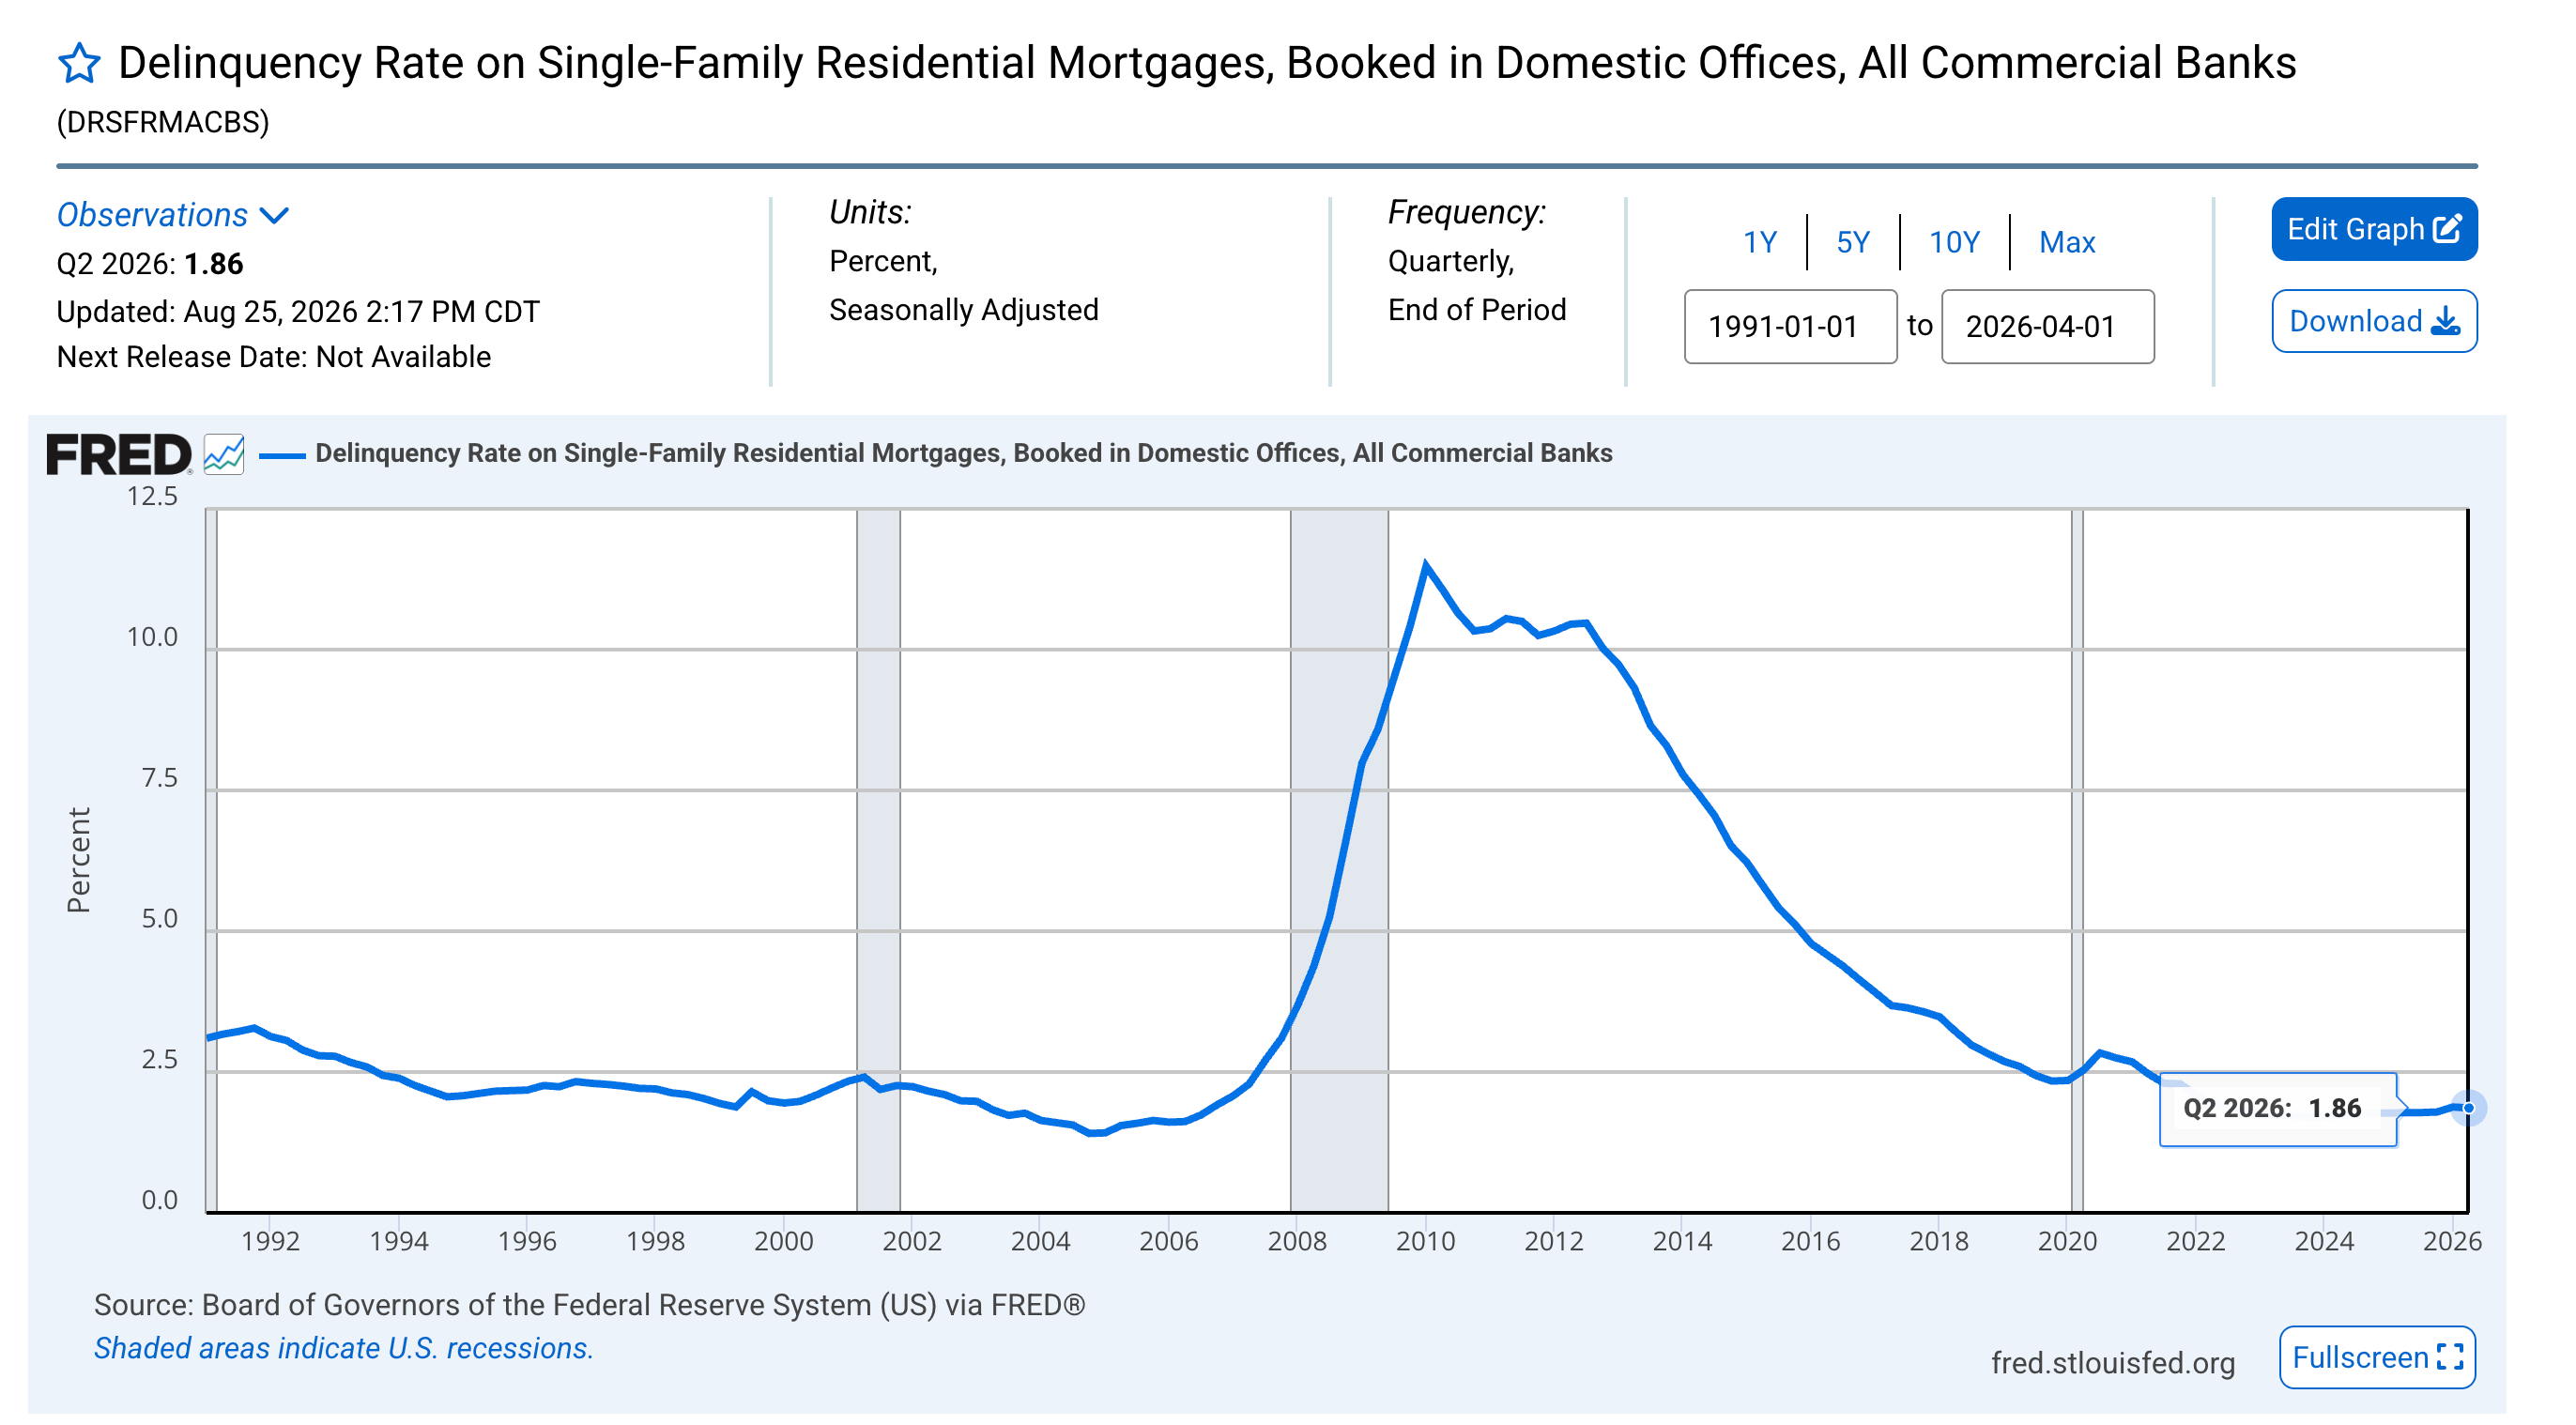
My gut was telling me that gloom-and-doom days are ahead, so as I prepared for this post, I thought I would turn to one of my favorite sources of economic data, the St. Louis Federal Reserve, for their data. What I found regarding mortgage delinquency was not as bad as I thought. Check out this chart. I fully expected a trajectory that was more “upward” than this. That being said, they don’t say I’m “Dougie Downer” for nothing, so we’ll still err on the side of caution and focus on mitigating downside risk as opposed to swinging for the fences. We’ll remain conservative by not overstretching on our LTVs. We’ll continue to insist on being able to identify both a primary and secondary source of repayment instead of relying on collateral liquidation for the payback on loans. We’ll continue to ensure that borrower character is a huge factor in our loan decisions. I still think delinquency is heading North, but I would have expected this chart to show more “bad stuff”. Just thought this was a good topic for discussion. 
0Reply
182 views

2 Replies

Jump to latestLatest
  • Lender · Orlando, FL · Member since 2023 · 220 posts · 183 votes
    1mo

    Hey Doug, I think the chart is actually pretty encouraging considering everything the housing market has dealt with over the last few years. At 1.86%, single-family mortgage delinquencies are still well below historical norms and nowhere remotely close to what we saw coming out of 2008.

    One thing I’d keep an eye on, though, is that this data is for mortgages held by commercial banks and doesn’t necessarily tell the entire story of stress in the housing market. A lot of homeowners are also sitting on significant equity and locked into historically low rates, which gives them options that borrowers simply didn’t have going into the last housing crisis.

    I agree with staying conservative on leverage, but I don’t necessarily see this chart as pointing toward a major wave of distress. If delinquencies do continue moving north, I think it’s more likely to create pockets of opportunity rather than another 2008-type event. For us on the lending side, the quality of the deal, borrower experience, and having multiple exit strategies are definitely becoming more important.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.