Cash offers Vs. Waiving the Financing Contingency

Cash offers Vs. Waiving the Financing Contingency

Landlord and Rehabber · Newton, MA · Member since 2010 · 2k+ posts · 877 votes

Do people feel that there is a difference between "Cash offers" and waiving the Financing Contingency?

I often see people talk to people like they are the Spawn of Satan if they say they are making a "cash offer" and don't have the actual money in a bank account, liquidatable stock account, or stuffed in a mattress as they don't trust them there banks!

I put in offers in 3 different states (MA, NH and PA) and none of the standard contracts have a place to put you are buying with cash. However they ALL have a place to elect of decline opting for a financing contingency. If you are not using standard forms then you can also just opt to not use the word "Cash" in it. Minimally I know that the offers you submit to HUD and Fannie Mae addendum also only have the yes/no for financing contingency so those don't say "Cash" either.

I don't think I have ever made a cash offer but I rarely have a financing contingency.

While it is of course ASSUMED that you are paying cash all you are saying is that you can't cancel the contract based on financing. As in if you don't get the loan you expect you aren't getting your deposit back.

Do other states and institutions have different forms where you would have to say that you are bringing cash to the table?
0Reply
32 views

7 Replies

Jump to latestLatest
  • Investor · Wichita Falls, TX · Member since 2010 · 3k+ posts · 603 votes
    12y

    I've only made cash offers in Wisconsin. There is no section to check "cash offer" but we just waive the financing contingency in the contract and submit it with my proof of funds. The POF is pretty much the way they know.

  • Dawn AnastasiPro Member
    Rental Property Investor · Milwaukee, WI · Member since 2013 · 6k+ posts · 4k+ votes
    12y

    I have submitted a cash offer with a 401(k) statement as "proof of funds" even though I didn't use the 401(k) account for my "cash" at closing and that was accepted. I've done that a couple times.

  • Investor · Clairemont, CA · Member since 2011 · 3k+ posts · 2k+ votes
    12y

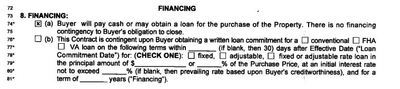
    This is what is in the FL standard contract. So along with this you will have to submit a POF for a cash offer. I've never used a HML so I don't know if you submitted a pre-approval with no financing contingency what they would say. I know when I submitted this offer the bank (it was a short sale) wouldn't look at my offer without a POF and asked for it again at the end of the next 2 months to verify that the money was still there as they continued through the SS process. So in that case if I was using a HML I don't know how the process would have gone.

  • Landlord and Rehabber · Newton, MA · Member since 2010 · 2k+ posts · 877 votes
    12y
    Originally posted by Dawn Anastasi:
    I have submitted a cash offer with a 401(k) statement as "proof of funds" even though I didn't use the 401(k) account for my "cash" at closing and that was accepted. I've done that a couple times.

    One reason I pretty much go to Bull$hitPOFletters.com (or whatever it is called:) ) to get POF letters is having issues with that kind of stuff.

    Once had a HUD offer accepted and I gave a POF letter from a legit HML in my area but it had a 6 month expiration on it. It was still valid but was going to expire like 2 days before the proposed closing date so they didn't accept it. I then submitted a pre-approval I had from a real bank that they verbally said would work even though it was in my name and the offer was in an LLC. They rejected that at first once they saw my wife's name on it as well. I then pointed out she is a member of that LLC and they were okay. The boss then shot that down since they said if it was in the LLC name that the letter had to be to the LLC. This also meant I could not use my 401k or a stock account or our personal bank accounts as POF.

    I went online and generated a POF letter with the LLCs name, the property address and like $2K more than the price I was paying (In case they said something about closing costs) and sent them that. No issues after that...

  • Landlord and Rehabber · Newton, MA · Member since 2010 · 2k+ posts · 877 votes
    12y
    Originally posted by Matt Devincenzo:

    This is what is in the FL standard contract. So along with this you will have to submit a POF for a cash offer. I've never used a HML so I don't know if you submitted a pre-approval with no financing contingency what they would say. I know when I submitted this offer the bank (it was a short sale) wouldn't look at my offer without a POF and asked for it again at the end of the next 2 months to verify that the money was still there as they continued through the SS process. So in that case if I was using a HML I don't know how the process would have gone.

    That is interesting that this one explicitly says what I said about could be cash or you can get a loan but don't think you aren't obligated to close if it doesn't work out!

    I bank will be more diligent about following up on that kind of stuff, though banks accept the convenient online POF letters all the time from me. Can't see why they would not accept a letter from a HML or other private lender if you waive the contingency and that is how the contract is written.

    Heck on that one I could see them taking a typical pre-approval letter from a bank but asking for a really big deposit.

  • Real Estate Agent · Milwaukee County, WI · Member since 2009 · 3k+ posts · 525 votes
    12y

    FYI : future knowledge @Dawn Anastasi and @Mehran Kamari

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    I believe " city owned properties " does have this option

    cash or financing contingency. ( check box )

    Reason :

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    City of Milwaukee requires all agents/brokers to use their

    offer to purchase contract versus standard wb-11.

  • Investor · Round Rock, TX · Member since 2010 · 8k+ posts · 4k+ votes
    12y

    In TREC contracts in Texas you can specify cash offers. There is also a section for a financing contingency.

    Whether or not there is a real difference in substance depends greatly upon whether or not you have substantial earnest money at risk. With little or no earnest money I wouldn't even look at your offer on the sell-side if it didn't have a financing contingency unless it was accompanied by a hard POF. If the contract specified a cash closing with a short option period and quick closing I'm not sure I would care as much about the earnest funds provided you have a POF.

    A lot also depends on the size of the deal and the market. In a tight market you'd likely be competing with many other offers and the cash offer with a hard POF would matter more.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.