I'm just curious what y'all think about the general market? Good time to buy or sell? Buyer's market/Seller's market/neither?
I had a discussion today with a Realtor who expects a rough time ahead....what with the election year coming up and the current state of the Economy/Feds/Rates/Etc. I don't necessarily agree, but I'm thinking status quo is maintained. I am selling a big property and buying a couple of LTRs so I would prefer that.
But what the heck do I know?
The first high level point, for me, is that I think that the housing market is about to see a huge regional variance. Over the next few years, some markets will see appreciation and rent growth, and others will see severe corrections. If I had to guess, on a national basis, I'd expect to see deep correction/crash declines in multifamily real estate (5+ units) and more muted declines or close to flat prices in single family housing in 2024 and beyond, with 2-4 unit properties somewhere in between.
The second high level point is that I personally do not believe interest rates are coming down. I think we are nearing the top in terms of raises from the Fed, but I expect the federal funds rate to remain north of 5% for the next several years, and personally believe that the yield curve will uninvert, seeing mortgage rates and interest rates on commercial real estate investments continue to increase from here. I understand the counterpoints here, but feel that the bet on rates coming down is a bet on the Fed suddenly and dramatically reversing course - something I think unlikely until Jay Powell's term expires and a new chairman is installed.
Diving a bit deeper:
5+ unit multifamily: I'm deeply, deeply bearish. Cap rates are already rising nationwide, and we have 700K+ units currently under construction (multifamily alone) nationwide. Mostly concentrated in the South and West. I think it's really hard to believe in interest rates saving the space from general cap rate expansion, and the glut of supply coming online in the next 16 months is going to continue to crank the vise on operators already struggling by and large to achieve their NOI targets. I think this is going to get worse before it gets better, and 2024 is going to be a part of the "getting worse" phase. I'll be really surprised if any major market in this country sees Cap Rates decline or even stay totally flat in the next 2-3 years. Thus, I believe that only the true value-add plays are viable at this time, and investors need to have a really long time horizon.
Fundamentally, investors have to believe in interest rates coming down, or believe rents will rise rapidly in the commercial space to justify buying property at cap rates below interest rates. I don't believe either, and I bet the market will be painfully forced to agree in a process that will get more excruciating with each passing month for the next 18.
Now, sometime in 2025 and beyond, the bottom hits, and a new dawn will emerge for the multifamily space. All that new construction will cease coming online, and there will be very few new projects hitting the market, and a lot of painful exits may mean less competition for entrants.
In the residential space, I'm cautiously optimistic that a "Crash" (nationwide) will be avoided. however, note that supply is even bigger here with some 900,000 single family units under construction (also concentrated in the south and west). Some markets, like Florida and big chunks of Texas, unfortunately, are unlikely to be spared. These markets, and their neighbors, have a ton working against them. Huge supply growth, huge anticipation of inbound migration that I think, frankly, is overly optimistic), and rising costs, due in part to climate change, do not bode well for these areas. I'd lump cities like Phoenix, Denver, Boise, and Nashville into this category as well, but I'd bet that they will feel a "secondary pain" to many Texas and Florida markets.
Markets that have already taken hits in 2022 and didn't see a big run up in the aftermath of COVID, like California, might actually not see the same pain. I'm not bullish on California, I'm just less bearish on big parts of the state, including Southern California, than the South and other parts of the West.
Markets that didn't change or have been steady for years are likely to be the best friend for investors over the next few years. Upstate New York, big chunks of the midwest, and less urban parts of the West and NorthEast are likely to do great. Chunks of the South as well, but in places that didn't see the big booms of the last few years.
I think that vacation rental operators will feel a ton of pain, relatively speaking, over the next 2-3 years. Prices in these markets can swing by 50-100% in a matter of a few short years, and the party's over in terms of "moderately wealthy" Americans being able to afford vacation homes for the forseeable future. I'll be surprised, frankly, if we do not see a couple of notable vacation rental markets decline precipitously from a pricing standpoint in the next few years. Further, even though demand for buying these properties puts downward pressure on rates, even the well-off investors and homeowners are likely to try to find extra ways of generating cash, and a personal home or vacation home in a vacation rental market, even at lower Average Daily Rates, generates cash for the owner. Expect to see even more competition in markets that allow short term rentals over the next few years, even as the profitability in the sector per unit declines. I think this is going to be really hard.
I think that by end 2026, investors will be feeling very differently about real estate depending on their strategy and market, but very few will have created massive amounts of wealth through market forces.
Investors with a long-term, traditional outlook on investing will see their properties slowly amortize and rents go up over the next 5-10 years, and are still likely to do better than alternatives like the stock market or a conservative bond portfolio. I personally have this viewpoint, and even though I am in Denver with my portfolio (a market I expect to underperform the nation over the next few years), I am holding and will continue to buy (1-2 in the next 2 years).
But, investors chasing great returns in a 2-3 year timeframe may be disappointed in some of the recently hot markets, and those depending on big rent growth and appreciation in any form may be devastated.
As usual, the well-capitalized, long-term investors will soak up inventory, buy when their financial positions are ready, and do so on solid properties that they can and intend to hold for decades. A few will place bets and try to time it, and inevitably, there will be some really smart but unlucky losers, and the same in reverse on the upswing.
Lastly, some real estate entrepreneurs (I use this term to describe wholesalers, flippers, large-scale operators, turnkey providers, etc.) will likely be "business as usual". The spread on deals, flips, etc. is likely to normalize quickly, and these activities will likely be as profitable as ever for the select few who perform them professionally, quickly, and at reasonable scale.
Agree 99% with your statement on politicians. Luckily I’m gullible about the 1%.
Great people rise to the occasion or difficult times create great people. The US system is built to be awkward and imperfect with the three legs of government. Luckily the people are the deciding factor. They are 99% wrong and deserve what we get. But during war or the Great Depression we always come together.
.
As far as I am concerned we are at war right now with change. What is abnormal at this moment in time there is not one enemy but several critical changes.
.
1. Our stated national debt versus our gdp has reached critical mass. On top of that social security, Medicare and Medicaid will triple that over the next 30 years.
2. Baby boomers timing out.
3. China has timed out as a cheap labor source. It will take 10 years to transition.
4. World population is growing to big. With a petroleum based agricultural system, man made water shortages, no next great Agricultural yield technology, won’t be sustainable. Luckily throughout history China has used famine to control its population.
For the US food is not a foreseeable problem for centuries.
People are pushing climate change. Whether you agree with it or not it can be solved in 2 to 3 years world wide. So if people believe in it they can fix it in 2 to 3 years. Plus make it an REI strategy.
5. We are moving into the Entertainment age. Bronze, iron, agricultural, manufacturing, technology, medical and now Entertainment age. Problem with the entertainment age is you don’t need a lot of workers. We have to figure out how to “give” for free the basics to people.
6. That leads to the item I intentionally did not include as my third item in my previous post. Pressure to mov to socialism and communism. We are an REI forum and I did not want to bring that up.
7. All. All great nations have failed when their military cost grew too large and there were no more countries to conquer. The US is fortunate that due to the various ages noted above, plus the Nuclear age you don’t need as large of a military as in the past.
Back to real estate.
A. The US will self correct. It’s built to.
B. Personally we have trimmed our investment portfolio and positioned to take advantage of high inflation.
Forget the politicians.
Start small and Make Your Big Mistakes Early.
Worst case my wife, dog and I move to Belize.

Always sage words of wisdom Henry.
I might add 1 point to what you have here. It's not a given the U.S. will "correct" or endure in a manner like the one before. My G.Father was a historian, as many of military command have been. And with that there is a known life cycle of "empires", and the final stage before collapse is, the age of entertainment....
Panem et circenses....
Yep, have you noticed the renewed call for masks and vaccines already starting....?
ugh.... Yeah, apparently it isn't just Hollywood who's lost it's creativity and is stuck into just doing rehashes anymore, right.
So a while back, I'm at my Dr, with COVID. Nurses all in hazmat suites, stuck to my own "special" section like I'm off-gassing aid's or something. My Dr comes in no mask, no face shield nothing, just normal. Does all the things per normal Dr visit right. At end asks if I have any questions, well hell yeah how about this giant purple poka-dotted elephant bouncing around the room!
So I ask her, "well yeah Doc, uhm, why arn't you wearing any PPP? I'm confused, aren't you worried about catching" and she cut's me off with an eye-roll "COVID, lol." She leans in toward me like to share a secret and says "it's all bull-sh#t" and sits back with a little matter of fact grin and a nod. Lol.
And she is not just any Dr., she's a one of the top doc's there.
She tells me yeah, if your diet is a pound of bacon a day and your 150lbs overweight, yeah, it can kill ya, just like ANY cold or virus can.
Told me what I should fear is whatever the hell there putting in these shots, whatever the heck they may be doing, and influenza.
Yeah, that was an interesting Dr visit.
Oh, and she said if asked she'd deny she ever said any of it because she likes her job, lol.
My cousin dies from covid, last time he was under 300lbs he was like 12. He was in 40's when died. Sucks, it does, I liked him, but who knows how many bacon sandwiches away from a coronary he was, we all knew it. Knew another guy, covid kicked his butt and he soon died, mid 80's. he was great for 80's but still, 80's, he coulda tripped and fallen down on a sidewalk and died.
At the height of covid heart disease was still the #1 killer in US, was before, still is today. In time I wrote this something like 7 people died from heart disease..... kinda bonkers to think about like that.
But-ahhhh.... so where is the bacon-patrol?
How's McD's still allowed to facilitate mass murder?
And butter, that psychotic killer, wow let's not even mention that Dr-of-death roaming the streets.
Seriously, are people not capable of the most basic self-thought anymore? We have the internet, really, how long does it take to google "#1 killer in the us"? Does nobody question a single thing the idiot-box tells them anymore?
Politics is tricky. The worse part is that they now have so many streams of media to manipulate people with. The uninformed and inexperienced will fold after a few clicks and lies.
Gotta keep digging. Gotta keep questioning thing, now more than ever.
Great post. Covid sucks. But there is no need to stop the world in its tracks because of it... or shall it be said better... there is not need for us to allow politicians to use it as an excuse to destroy our lives. just saying..
Powell tends to mention he wants housing costs to go down. In the stock market they say don’t bet against the fed. I expect interest rates to remain high unless housing seems a substantial decline. With that said labor and materials costs suggest new housing can’t go down in price (and old housing as well)
With that said I expected a recession between now to q1 2025 and that doesn’t seem to be shaping up.
In my market (Rochester, ny) the economy is primarily driven by defense and healthcare so I expect to be largely unaffected by the broader economy. (We didn’t feel as much of a pinch in 2008 as the rest of the country).
The thing is Fed has failed to crash the stock market , to crash the job market , and to crash the housing market. So far.
If the Fed has failed miserably to do their job than their analysis is not super accurate as well, although they're able to lower inflation to three percent.
In bond market we have hedge fund shorting the bond but majority of the funds is long the bond LOL Everyone confused.
So I do have crystal ball for the future , and it says the fed has no crystal ball.
I would say this decade of how the Fed manage the economy is like what the San Francisco local gov doing to their city, they intentionally trying to increase the crime in the city by defunding the police, the Federal gov. is so keen to laying off people LOL these are so weird time in America, they want to create more criminal, homelessness and joblessness in the society. Market say no no no LOL
At no point in your rambling, incoherent response were you even close to anything that could be considered a rational thought. Everyone in this room is now dumber for having listened to it. I award you no points, and may God have mercy on your soul.
I agree with @Carlos Ptriawan. Not because the fed doesn’t know what they’re doing, but because they aren’t calling the Legislative and Executive branches out. No matter what party. The feds have no where to go. They have no tools to fight inflation.
As @Carlos Ptriawan has mentioned they can’t keep increasing the rate or the banking system will go bankrupt.
They can’t use the labor market as a tool to fight inflation since unemployment is so low, baby boomers are exiting, Social Security Medicare Medicaid will start to rise and illegal work force won’t show up.
If the feds back off an inch on rates, inflation will skyrocket immediately.
The only solution to inflation is the executive and legislative branches. Stop spending, turn on keystone pipeline/coal/nuclear, cut off illegal immigration, tune up immigrant work visas, tune up white collar immigration.
The other solution is for the world to keep chasing cheap labor and poor environmental practices in India and Malaysia. China has timed out and is no longer a cheap labor source. But India and Malaysia are not chasing the Western dollar so they won’t convert like China.
Ah, but that's where your wrong. See, your thinking like a normal intelligent human being, remember, politicians rule the hill, so you have to answer to such in a way a politician would think.
Now, what is the universal #1 un-matched talent of all politicians, regardless of party lines? They are Gold Medalist's in Can-Kicking. A common ethos on the hill is "never let a crisis go to waste". I have no doubt they will employ these skills, why, because actually solving the problem is too dang difficult. Look, name a problem they have actually solved in last 20 years of any complexity, just 1.
What I expect, is the Fed to do exactly as it has continuously said it's going to do, why any think a reverse is even a potential is beyond me, it's the Fed, there "THE" bank, they think like a bank, there out for their interest's first and foremost, and really how can anyone fault them for it, if your expect a cat to fetch, it ain't the cat's issue why it doesn't work out.
I am betting we will see "TARP 2.0" come into existence, just about time things start to hit unbearable, and doom seems certain, remember "never let a crisis go to waste". Oh, and "TARP 2.0", yeah, the oldest play in the politicians book, why fix a problem when you can borrow your way out of it. Oh, short term you say, well aparently you forgot our Gold Medalist Can-kicking All-Stars, because don't worry there will be a fairy tale of growing GDP out of it or blah-blah-blah, or, heck we'll just borrow MORE....
Via some "special" funding actions, they can argue BOTH directions simultaneously; providing liquidity for those in need, maybe some bridge financing offset for commercial finance, 1% down mortgages for first time home buyers, etc etc, all while allowing the Fed to SQUEEEEEze to "fight inflation", even though there "help" is making more inflation, that then requires more "help" and hey, wouldn't ya-know it there happy to "help" all ya-gotta do is vote for them because "booo" look at that other "meanie" saying ugly things like fiscal responsibility, reign in spending, man what a kill-joy that guy is right.......
Lets divide and conquer the problem with real estate now :
- The TARP 1.0 is created after the subprime mortgage in 2008.
Now the Fed before started increased the rate, they have their own publication where they indicate, thru their indicator, they're very sure, at this time it would not create chaos in banking financial system as foreclosure now is very low and lot of homeowner owned large equity.
However , they have contrarian view as well thru inflation data, they want to see the "home price" to go down to reduce the inflation as major expense in inflation calculation is the rent/mortgage payment. This is where the Fed doesn't know what to do on how to influence the market in such a way that they expect price to go lower following interest rate hike. This surprise the Fed by a LOT.
- By increasing interest rate, the bond price is going lower obviously. And the Fed understand that the biggest owner of the (MBS) bond such as Wells Fargo and/or Bank of America would have huge losses in their book. But so far it's accounting losses only. They know if that bond doesn't need to be sold (like what SVB did), then it would not cause crisis (yet). But if somehow BAC has to sell the bond, the gov. may have to rescue the big bank as well which may cause TARP 2.0 very quickly.
- Most of the troubled with real estate is on certain asset class only, in particular, office building A/B , mall and/or hotels. If you have 1980/1990 office building asset class in SF basically your money is cut by 35%. Everyone knows that. Now that asset is held mostly by Regional Banks. They have large losses due to its massive valuation mismatch. We still do not know the future about the valuation of office building, as 2023 pricing is set back as far as 2005. This is what the Fed doesn't know what would be the impact and where the leak would be.
Are they going to bring bridge financial bridging to some Regional ? may be
- The TARP 2.0 is actually already happening @James Hamling, this happen in very private transaction for US to save "Credit Suisses" crises where US gov. is loaning cheaper dollar than normal to their European counterpart to save their banks. In much cheaper transaction, the TARP 2.0 is done discreetly to SVB and FRB.
So yes like you said, there are still many unknown that the Fed doesnot understand as well but it seems they would do few minor selective (and reactive) TARP 2.0
What is the biggest "threat" to the roll-out of the FedNow and CBDC? Adoption.
Whom has the greatest power to be a "threat" but defiance in adoption? Regional banks.
Who has greatest risk exposure of liquidity crisis from commercial finance? Regional banks.
What is the greatest "threat" to creating a liquidity crisis in commercial finance? Strategic default.
What would cause one to need, want or have profitable interest in doing Strategic Default? Financed capital resetting at a non-serviceable level, such as one that's interest rate is doubled/tripled may do. And where in walking away under bankruptcy just makes more profits.
What would happen in a deluge of Strategic Defaults in commercial finance? Regional banks would disintegrate, simply put.
The Fed "solves" the regional banks problem via a quazi TARP 2.0, could be as simple as bridge financing for said borrowers to cover the increased cost of resetting debt, deferring out to a later date, tacked onto end of their current finance, payments on such deferred. Funding to transact via, you guessed it, CBDC, thus solving the Fed's problem of adoption, and while allowing rates to remain in the altitude they sit to squeeze the economy at-large into the mirage of a 2% inflation rate submission.
It's brilliant, really, only 1 issue. If no crisis, it doesn't work, it requires a crisis. But hey, that's just opening the door to crazy talk, our gov. would never do anything like making up a crisis just to be empowered to "deliver the cure".... (Gulf of Tonkin, Iraqi WMD, Panama, Granada, explosion on battleship Maine....)
So a while back, I'm at my Dr, with COVID. Nurses all in hazmat suites, stuck to my own "special" section like I'm off-gassing aid's or something. My Dr comes in no mask, no face shield nothing, just normal. Does all the things per normal Dr visit right. At end asks if I have any questions, well hell yeah how about this giant purple poka-dotted elephant bouncing around the room!
So I ask her, "well yeah Doc, uhm, why arn't you wearing any PPP? I'm confused, aren't you worried about catching" and she cut's me off with an eye-roll "COVID, lol." She leans in toward me like to share a secret and says "it's all bull-sh#t" and sits back with a little matter of fact grin and a nod. Lol.
And she is not just any Dr., she's a one of the top doc's there.
She tells me yeah, if your diet is a pound of bacon a day and your 150lbs overweight, yeah, it can kill ya, just like ANY cold or virus can.
Told me what I should fear is whatever the hell there putting in these shots, whatever the heck they may be doing, and influenza.
Yeah, that was an interesting Dr visit.
Oh, and she said if asked she'd deny she ever said any of it because she likes her job, lol.
My cousin dies from covid, last time he was under 300lbs he was like 12. He was in 40's when died. Sucks, it does, I liked him, but who knows how many bacon sandwiches away from a coronary he was, we all knew it. Knew another guy, covid kicked his butt and he soon died, mid 80's. he was great for 80's but still, 80's, he coulda tripped and fallen down on a sidewalk and died.
At the height of covid heart disease was still the #1 killer in US, was before, still is today. In time I wrote this something like 7 people died from heart disease..... kinda bonkers to think about like that.
But-ahhhh.... so where is the bacon-patrol?
How's McD's still allowed to facilitate mass murder?
And butter, that psychotic killer, wow let's not even mention that Dr-of-death roaming the streets.
Seriously, are people not capable of the most basic self-thought anymore? We have the internet, really, how long does it take to google "#1 killer in the us"? Does nobody question a single thing the idiot-box tells them anymore?
@Scott Trench dude is smart.
On the first go round with COVID most of us thought the market was going to have a nasty dive. It didn't because the government stimulated the heck out of the economy. In an election year I think it is 50/50 if not more that the government steps in and further distorts the markets. Personally I am good with a crash even if means rents and my income drop. I just don't want send my kids to school again with masks on and be guilted everyday for not wanting a vaccine until we have a little more evidence that the vaccine is better then just getting COVID which all the vaxxed seem to get anyway.
This is more like one of those political thriller movie okay
But Fed is not stupid.
They acted like God.
They intentionally has to create financial crisis every 12-15 years or so to stimulate the overheating economy and to restart again.
So this all has been planned.
Covid is just being used as undercover project to trigger the crisis LOL LOL
They are not stupid when they print more USD to the market. Of coz my grandma also know too it would create inflation and subsequent crisis.
isn't the market constantly in distortion? I just don't think they have the ability or competence to flip a switch and try to juice the economy just because it's an election year. they waited too long to raise rates and here we are.
@Bruce Woodruff
Good morning Bruce. Lots of great points and opinions already. But I'll chime in... from a SoCal perspective...
I think the market is still hot! It's predominately a sellers market still. Although I mainly concentrate on small multifamily, I can tell you that it is HOT!!! It flies off the shelf if it gets listed at any reasonable price. However, most times it never gets listed because the demand is so hot that the agents get it sold with only a few calls.
The last 5 out of 7 deals I closed were all off market. And I had to jump on it because I knew if people got wind, I would lose them. They were all small multifamily, 6 to 20 unit buildings.
My most recent deal, to be closed next week, is also off market. It has a blended COC of 7.5, CAP of about 7.5, and GRM of about 8. Total price was originally about 2M, but I negotiated to 1.85M with a promise of no trades. Its 14 homes and one vacant lot, spans 1.5 blocks, and unit mix from studios to 4 bedrooms.
I am always looking and negotiating and I can tell you that the market here is so competitive that you better have funding at a moments notice. There is no sign os slowing down, only limited inventory. I was negotiating a 32 unit and was almost there when the word got out. Suddenly all kinds of investors jumped it to snatch it up.
I feel that the market will vary from region to region. However, the major markets might have seen their bottom, or close to bottom... with the stagnant prices. Now, there may be a good possibility that it will begin another in up in 2024. I do not have any concrete evidence, just a gutt feeling based on experience.
Sam, I'm in Southern California too and invest mostly small multi family 1-4 units. Recently try to bid a triplex off MLS that was priced about 100k under value. I made an offer with the listing agent but still got beat by 2 cash offers at 1.2 mil. Curious though...how are you cash flowing with these high interest rates? I'm currently working a deal on a offmarket duplex in long beach but the numbers look terrible..almost negative 4k/month cash flow after all expenses with the rate and low rents. Both factors can be corrected over time but itll be a painful slow process. The rate portion we can't control. The deal itself is awesome at 360/sqft where the area goes for 450-500/sqft so that's the main reason I still want to pursue.
Folks:
They are not cashflowing at these rates. These investors are sitting on cash and need to park it in something. So they don't care about cash flow because they don't have mortgages.
Instead of distortion I should say less of a market based economy, thats fair. My overall point is with stimy's, PP&E, zero interest rates and the rest of it on paper everyone got richer but in real life there was less production. Guys like us actually did great since we had debt and that debt got further and further diluted. So while I agree with Mr. Trench that if the economy was dependent on market forces real estate investors would be in trouble, I am not sure the government's financial engineers won't bailout even make certain asset owners richer yet again.
Many times I disagree with folks on the forums about how much of a roll the market actually plays in REI's fortunes. Less and less about supply and demand "invisible hand" and more and more about government reactions.
got it, i see what you're saying now.
isn't the market constantly in distortion? I just don't think they have the ability or competence to flip a switch and try to juice the economy just because it's an election year. they waited too long to raise rates and here we are.
What would you call the NINJa loans of yesteryear? That sure as heck was "flipping a switch" was it not? And it was all done via policy makers, making policy to lend-baby-lend.
How about COVID, what did they do? Yup, flipped a switch via policy, it was the "Opera-Hour", "you get a check, YOU get a check, YOU ALL GET CHECKS!!!!!".
Look back, that's literally what they do all the time, flip-a-switch via policy, using financed funds in 1 way shape or form, fluffing things coincidentally before some election cycle. Just look back and see.
This is more like one of those political thriller movie okay
But Fed is not stupid.
They acted like God.
They intentionally has to create financial crisis every 12-15 years or so to stimulate the overheating economy and to restart again.
So this all has been planned.
Covid is just being used as undercover project to trigger the crisis LOL LOL
They are not stupid when they print more USD to the market. Of coz my grandma also know too it would create inflation and subsequent crisis.
Well, it goes back to foundational facts. The Fed is a bank. Banks sell $. When things are booming there is need to buy-$. When things are melting down there is a need to buy-$.
But when things are calm, coasting, stable in the middle, there is no need to buy-$.
Stability and calm is the "villain", in their business existence.
Oh I agree, I just don't think they get the intended result very often!
And that is the crux of it all isn't it, whom are they truly with intentions of serving? If the general populous, heck no, it has been anything but prosperous really since 90's, late 90's were freakin awesome. At least where I was, for the middle.
But, if for the top 2%, the past decade has been very literally the best, most profitable decade in history for the 2%. Which is saying much because previous decade was also the most profitable ever. So they've been winning from it all consistently.
Oh I agree, I just don't think they get the intended result very often!
And that is the crux of it all isn't it, whom are they truly with intentions of serving? If the general populous, heck no, it has been anything but prosperous really since 90's, late 90's were freakin awesome. At least where I was, for the middle.
But, if for the top 2%, the past decade has been very literally the best, most profitable decade in history for the 2%. Which is saying much because previous decade was also the most profitable ever. So they've been winning from it all consistently.
I guess we better stay in that top 2%...
I loved the 90s. Best decade, at least for me. Gas was under $1, food was cheap, tech was booming, and music was evolving. Got out of the Army end of 99, it still felt good, but only for a minute. It's been a rollercoaster since the 2000s started.
I think there is some truth to your assessment. I feel like the Lower middle class got push lower and the upper middle class enjoyed most of the prosperity. A few were able to step put of the norm and move upward.
Oh I agree, I just don't think they get the intended result very often!
This is what I meant at the beginning
Govement action usually got the “unintended consequences “
Hello @Bruce Woodruff,
There is no general answer to your question because real estate local and broad statements do not apply. While national level events like interest rates can impact local markets, some markets will perform better than others.
Even within a city, property sectors perform differently. For example, sales of homes priced > $1M may be dead while homes priced between $300,000 and $400,000 might be selling in days.
The only information I can provide pertains to the specific property segment we target in Las Vegas. Hopefully, others can provide similar information on property segments in other cities.
Overall inventory is falling in Las Vegas. The chart below is from the MLS and includes all property types and price ranges.

The following information pertains specifically to the property segment that we are targeting:
Type: Single-family
Configuration: 1,000 SF to 3,000 SF, 2+ bedrooms, 2+ baths, 2+ car garage, minimum lot size is 3,000 SF.
Price range: $320,000 to $475,000
Below is a map showing where many of our client’s properties are located.
I prefer using charts instead of lengthy text to convey information. We generate these charts every month, include them in our monthly market update, and post them on my blog. If you're interested, you can find the link to my blog on my profile page.
Rentals - Median $/SF by Month
June rents were unchanged from May. YoY is flat. However, rents follow prices and prices are rising.
Rentals - Availability by Month
The number of homes for rent continued to drop.
Rentals - Median Time to Rent
The median time to rent is 20 days, unchanged from May. 45 days is typical for this time of the year.
Rentals - Months of Supply
There is only about 0.7 months' worth of supply.
Sales - Months of Supply
The inventory is only about 0.6 months of supply, whereas a balanced market is considered to have a 6-month supply. This shortage in supply will drive up prices.
Sales - Median $/SF by Month
Despite increasing interest rates, $/SF is climbing month after month in 2023. June $/SqFt is 7% higher than January.
Prices and rents are driven by supply and demand. Below is the supply and demand situation for Las Vegas.
Supply
Las Vegas is unique in that it is a tiny island of privately owned land in an ocean of federal land. See the 2020 aerial view below.
There is very little undeveloped private land remaining, and any available land in desirable areas costs more than $1 million per acre. Due to the high cost of land, new homes in our targeted locations start at $550,000. The homes that appeal to our target tenant segment are priced between $320,000 and $475,000. Therefore, no matter how many new homes are built, the housing stock we target remains almost constant. Most metropolitan areas have unlimited expansion room so new homes limit the growth of rent and prices of existing properties. A good example of this is Phoenix.
Demand
The driver for housing demand is population growth. Where there is sustained and significant population growth, demand for housing causes prices to rise.
The average Las Vegas annual population growth is between 2% and 3%. However, according to Yahoo Finance, Las Vegas is now the top city to which people are moving so the growth rate may be increasing.
What attracts people to Las Vegas (and other metropolitan areas) are jobs. In the last job fair, there were over 20,000 open positions. Moreover, the number of jobs will increase in the future. Currently, there are approximately $30B worth of new projects either under construction or planned. As these projects come online, they will create thousands of additional jobs, attracting more people to Las Vegas and further increasing housing demand.
A significant portion of those who move to Las Vegas fit the tenant segment we've targeted since 2005. Therefore, the demand for properties priced between $320,000 and $475,000 will continue to increase over time.
The fixed supply of homes in our target price range, coupled with increasing demand due to population growth, almost guarantees that prices and rents will continue to rise for the foreseeable future.
The only solution to inflation is the executive and legislative branches. Stop spending, turn on keystone pipeline/coal/nuclear, cut off illegal immigration, tune up immigrant work visas, tune up white collar immigration.
Say it louder... MUCH LOUDER...
@Bruce Woodruff it’s either going up, or it’s going down. Depends on the market and your strategy. Pick the right market and strategy and all is good. Pick the right market and the wrong strategy then not so much. Pick the wrong market and the wrong strategies, then buckle up butter cup. You are going for a ride.
Hi Bruce!!
My answer reflects the Phoenix market as it's the market I work in and know the best.
It's a bit of a double edged sword, buying now, high rates.. selling now, potential for upside next year. The entire thing is really subjective to your situation and if it makes sense.
Personally, I think Phoenix real estate prices are in for a wild ride UP next year once we get some sense of direction on rates and the overall detriment on the real estate industry here in town relaxes a little bit. Inventory has recently climbed about 1,000 units (13k total between active and coming soon) and is still far below the numbers needed for prices to go down. I'm sure you see it and hear it but with the overall growth, attractions, developments and economy booming into our state we are likely to continue leading the country in population growth. These people will need a place to live.
For buying - buying the "cookie cutter" long term rentals, (think 3/2 1700 sq ft in Surprise) has become easier than ever as the stuff that needs work is sitting on market longer and longer allowing for you to negotiate the price, terms, repairs, etc. As long as you break even (which is likely the scenario even with 20% down) you will be alright when rates take a small dip and refinancing becomes a thing again. I'm estimating at least 16-24 months before that happens, but hopefully it's sooner. Very few are over bidding and waiving everything like before.
For selling - this is where I really see some potential in waiting. I feel when the sentiment eases up on the market and the buyers come back into the market, the pent up demand that has been building all year will hit prices hard and competition will raise prices once again. How high? I think that depends on rate. People will pay more for a house they love but everyone has a monthly payment budget they must abide by. I don't expect to see 50-100k over asking like we did a few years back but maybe 10-30k over. I recently had to do that on a four plex to win against 13 offers. If you purchased prior to 2019 then either way you're making a killing so could be worth selling now if you plan on using that money to buy other properties.
I hope this helps. Feel free to reach out with any specific questions about which part of town you plan on buying the LTR's in to see how the SFR and rental rates are doing in that area.
The only solution to inflation is the executive and legislative branches. Stop spending, turn on keystone pipeline/coal/nuclear, cut off illegal immigration, tune up immigrant work visas, tune up white collar immigration.
Say it louder... MUCH LOUDER...
Ok BP "masters", seriously this is NOT going to be political speak, it's a legitimate question.
So, if these kind of statements are "extremist" as my "idiot box" keeps saying they are.... Does that mean non-extremist, and there in "good" direction is; - Spend more - turn OFF more oil, OFF more coal, OFF more nuclear and just energy in general - more open boarders, is the good/smart way to go ????
Seriously. Am I the only one who's taken the defining of all that's been called "extremist" and thought "ok, so, your saying do the opposite then?" and thought out what the opposite is?
Because the opposite seems crackers. Just, obviously crackers, where if anyone said it out loud they'd get laughed out of a room because the economic impact of destruction is obvious.
I want MORE rental properties, so in a way that's cheering for calamity to some extent. But I want great tenants, and for great tenants they need good blue-collar income. So, in that I am rooting for strong economy. But I want renters, so, not too strong, lol.
Soooo apparently I am a house divided, lol. I would like a horrible, great and ok economy, lol.
Ok BP "masters", seriously this is NOT going to be political speak, it's a legitimate question.
So, if these kind of statements are "extremist" as my "idiot box" keeps saying they are.... Does that mean non-extremist, and there in "good" direction is; - Spend more - turn OFF more oil, OFF more coal, OFF more nuclear and just energy in general - more open boarders, is the good/smart way to go ????
Seriously. Am I the only one who's taken the defining of all that's been called "extremist" and thought "ok, so, your saying do the opposite then?" and thought out what the opposite is?
Because the opposite seems crackers. Just, obviously crackers, where if anyone said it out loud they'd get laughed out of a room because the economic impact of destruction is obvious.
I want MORE rental properties, so in a way that's cheering for calamity to some extent. But I want great tenants, and for great tenants they need good blue-collar income. So, in that I am rooting for strong economy. But I want renters, so, not too strong, lol.
Soooo apparently I am a house divided, lol. I would like a horrible, great and ok economy, lol.
Ok BP "masters", seriously this is NOT going to be political speak, it's a legitimate question.
So, if these kind of statements are "extremist" as my "idiot box" keeps saying they are.... Does that mean non-extremist, and there in "good" direction is; - Spend more - turn OFF more oil, OFF more coal, OFF more nuclear and just energy in general - more open boarders, is the good/smart way to go ????
Seriously. Am I the only one who's taken the defining of all that's been called "extremist" and thought "ok, so, your saying do the opposite then?" and thought out what the opposite is?
Because the opposite seems crackers. Just, obviously crackers, where if anyone said it out loud they'd get laughed out of a room because the economic impact of destruction is obvious.
I want MORE rental properties, so in a way that's cheering for calamity to some extent. But I want great tenants, and for great tenants they need good blue-collar income. So, in that I am rooting for strong economy. But I want renters, so, not too strong, lol.
Soooo apparently I am a house divided, lol. I would like a horrible, great and ok economy, lol.
Why would you think prices "can't" stay at this level, or rates "can't" stay at this level?
With the direction of things now, I am 98% certain that prices will not only stay at this level, but go up MORE.
The problem with the notion your using, is your basing a sense of pricing, off yesterdays income. And while todays income, may be from yesterdays negotiation of income, the issue is price direction is reflective of TOMORROWS income.
And Wage Inflation is steadily raising tomorrows income 20-30% right now as we speak.
So, with incomes up 20-30%, does it really make sense to say prices "must" come down, when people are earning more?
I get where your coming from, your venting the whip-lash and still in a daze from it, as many are. But fact is, wage inflation is here, it's no longer a forecast, it's happening, and once the genie is out of the bottle there no stuffing it back in.
So, buckle up, prices are destined to go up MORE. Raise COGS and the consumer price will go up as well. There is a feed-back loop to inflation, and we are just in one of the early waves, #3, of such.
It starts as wave #1, mass liquidity injected into system that spurs consumer activity.
Which get's wave #2, mass inflation fueled by #1 facilitating supply shortages and the two with a feed-back loop making #2, mass inflation, which is prices running up, way up.
Which leads to wave #3, Wage Inflation. Persons feeling the squeeze of prices, press employment for more income to counter-weight. And in a labor shortage environment, this too has it's own feed-back loop which forces employers to relent to wage-inflation demands, which increases COG's and causes.....
Wave #4, prices go up yet again but this time as supply exists it's amplitude is a bit less, but it's pressed by wage inflation in 2 ways of increased COGs, and more consumer liquidity/affordability from wages inflating.
And these waves repeat, in cycle, over and over and over again. It's a freight train, Fed applies the "rate" breaks but it does not stop on a dime, it's has momentum that carries it and has to be depleted, which takes time, wave cycles to wash through system.
This is why the Fed said they were trying to fight wage inflation, to stop the next wave in the cycle, or to lesson it, to lesson the following inflation to follow, and all following cycles. Because the Fed can't waive a wand and create surplus of supply in material goods or labor, which would also do it, but those are both in shortage, so the only tool left is rates, to slow liquidity, slow everything.
Home builders are not idiots, they are throttling supply, there not going to allow supply over-runs. So guess what, rates will stay up, possibly even higher, because it IS sustainable at these rates, as current activity has proven.
It's renters who will next feel the squeeze, as supply for renters becomes ever more constricted. And it will. Forcing rental rates up, even though affordability is already strained, supply-demand will rule.
And this is why you see the "big boys" building apartments today, as you scratch your head wondering what "idiot" is throwing away $ on building MFH today, at todays rates. There not idiots, they just happen to know something you don't. And so do their backers.
This today is a "Perfect Storm" scenario. The complexity makes '08' look like little leagues in comparison.
Hello @Bruce Woodruff,
The only information I can provide pertains to the specific property segment we target in Las Vegas. Hopefully, others can provide similar information on property segments in other cities.

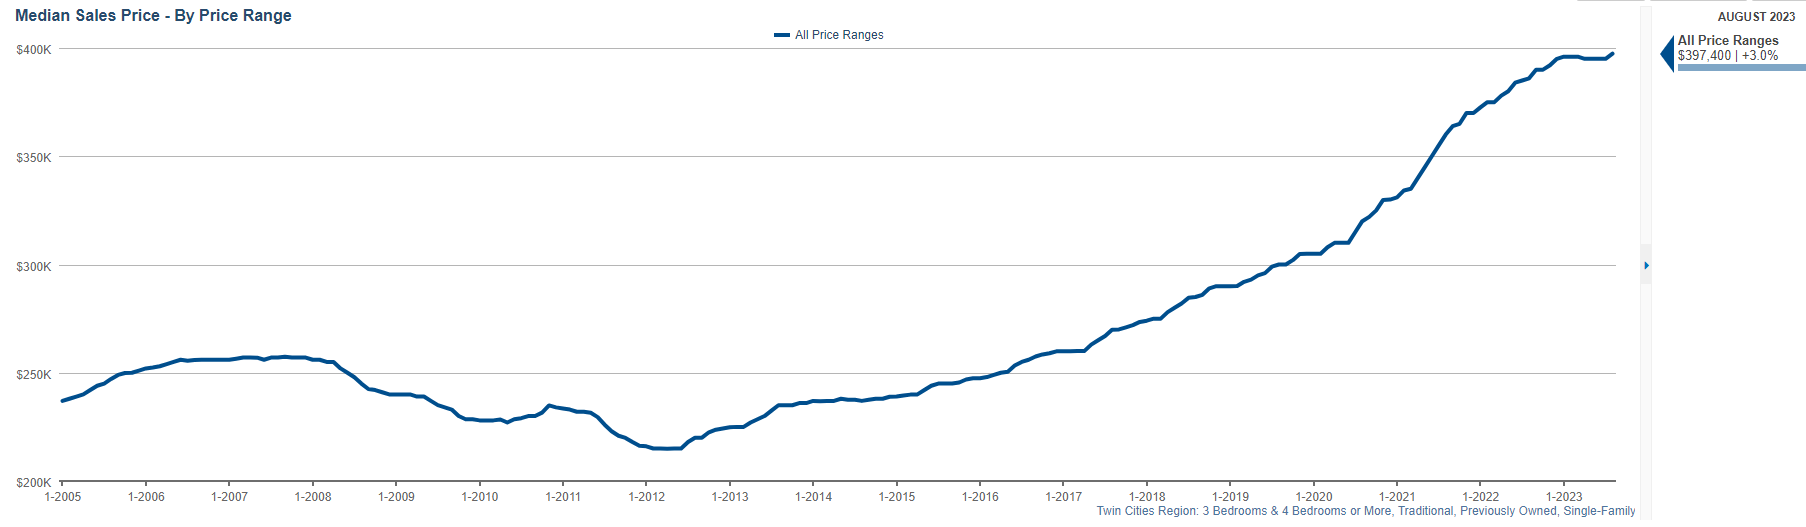
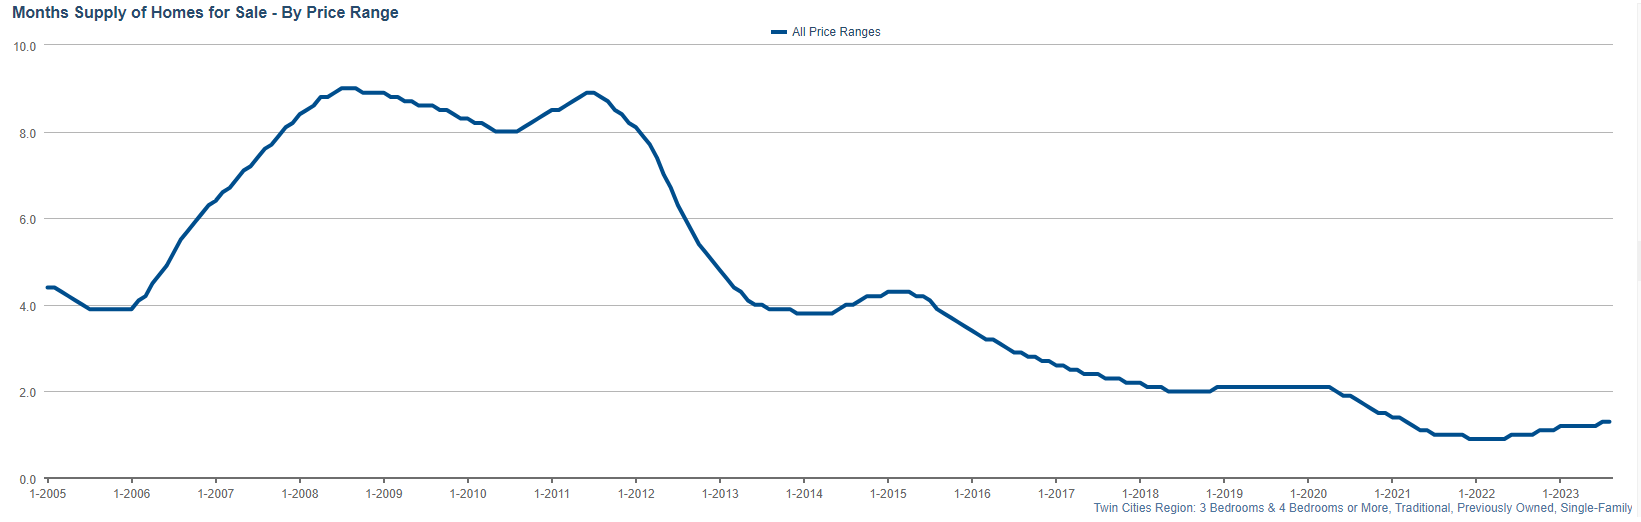
To no surprise we find correlation in inventory too median price movements, now sitting at 1.3 months supply. "Shortage" is designated under 3 months.
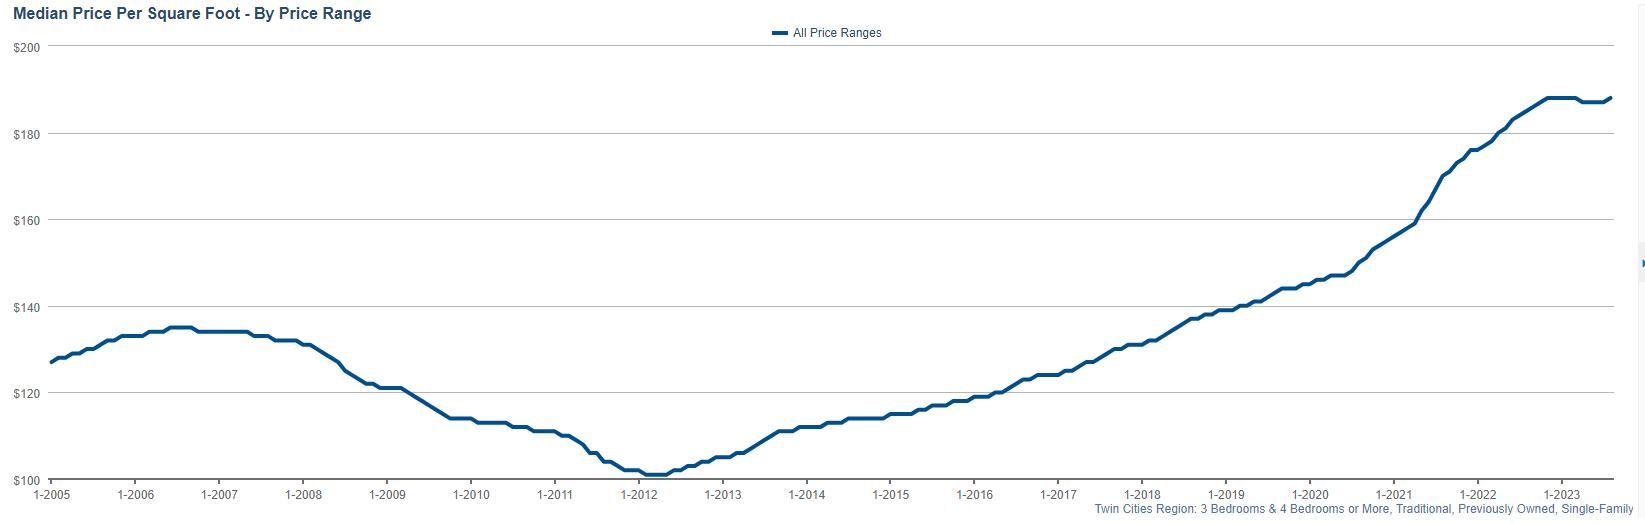
Price per sqft holds it's historical high of $188sqft, this data indicates many things but in general it defeats any false narrative that people are simply paying more because they are getting more.
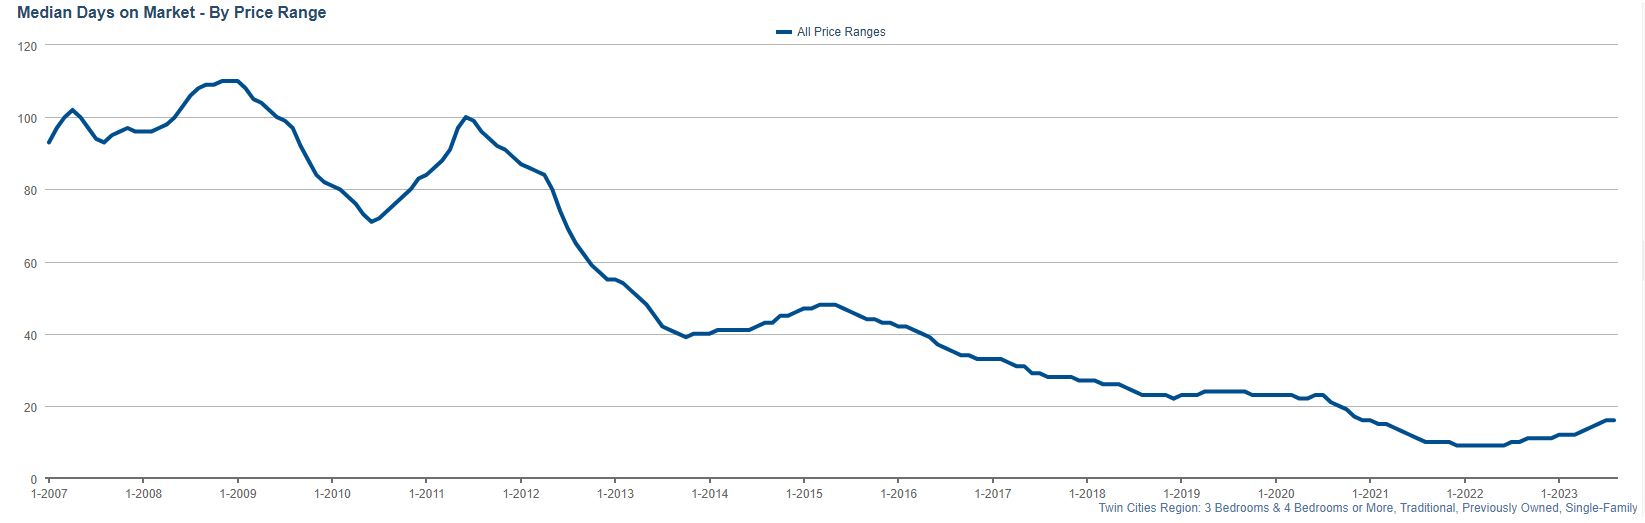
Days on market, sitting at just 16, is an important metric because as people say there "feeling" is prices are far too high, and there is lack of affordability, the data speaks otherwise, where the data says it's a robust absorption in the market, if anything a very "hungry" market. Anything under 30 days is considered "rapid" or "quick" and as pre-'08' shows ~90 days was "the norm".
New listing inventory continues it's decline post '22', indicating an ever tightening of supply and with it price support in supply - demand curve.
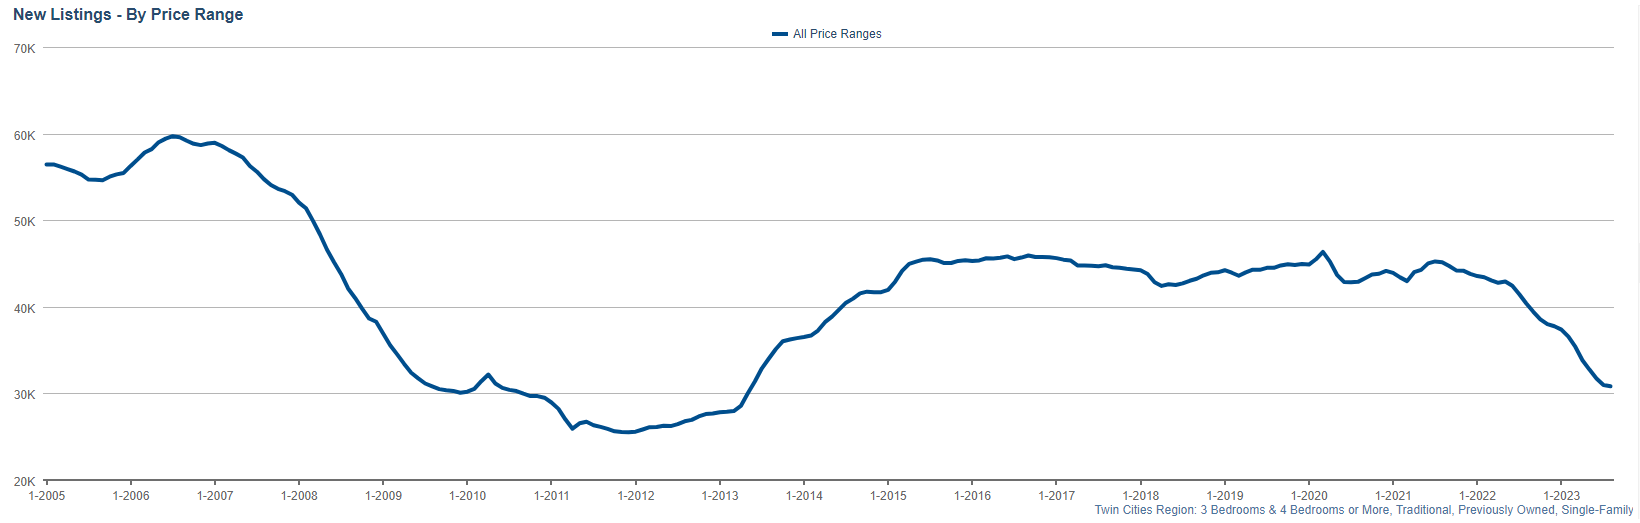
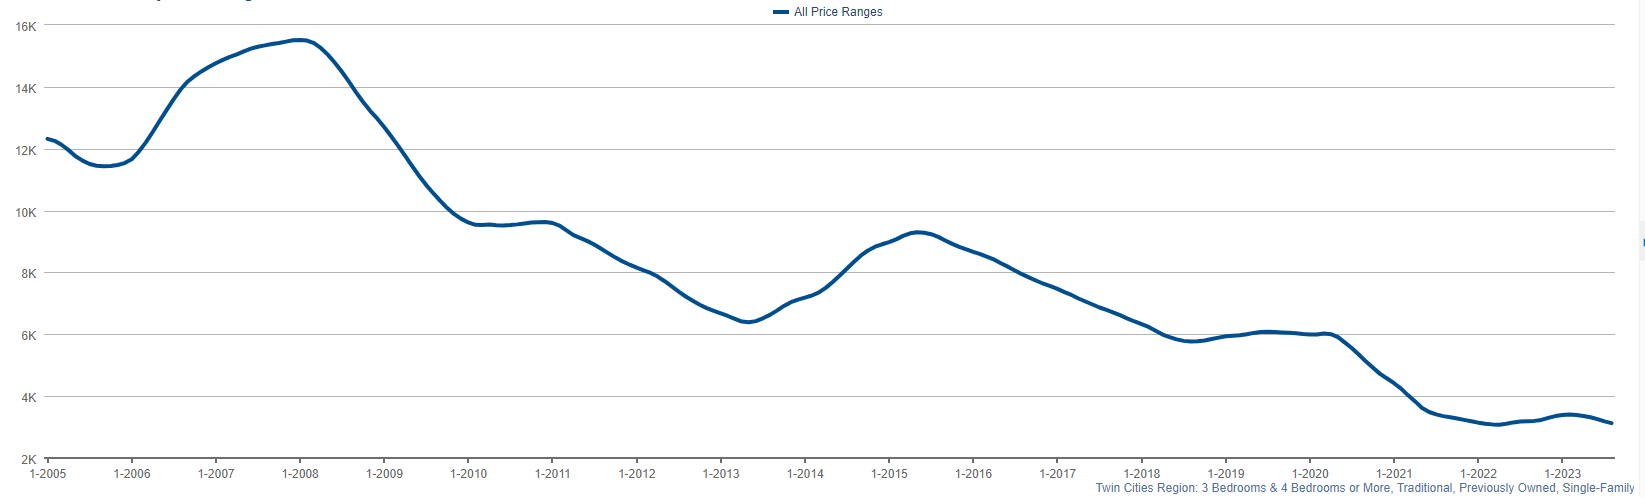
Total inventory can best be described as a complete collapse of inventory, being less than 1/5th that of pre-'08' levels and roughly half pre-covid levels. Showing that the myth that builders can run a glut of supply as all but mathematical impossibility, they would have to increase out-put by thousands of units PER MONTH, in just this 1 market. Which would require an additional labor force of roughly 100k additional skilled labor to the pool.
As for rental data, that's all internal and I'd have to put to graphs to show graphs of such vs the metric's we have it in. In a nut-shell, no relent to collapse in inventory for renters, supply is at historical "tight" levels. Prices have gone up on average 20%+ annually for last 3 years consecutively. And the trend continues as not only inventory remains tight but as long term leases expire through setting to the "new" reality of market rents, thus solidifying this new basis of market rents, and supporting foundation for future increase.
Trends have emerged in tenants taking mitigating actions of multi-gen living at a multiplier rate of increase.
MFH is only segment adding, not loosing, inventory supply, much of which is concentrated in luxury MFH segment. Despite inventory additions, occupancy rates remain historically low.
Ok BP "masters", seriously this is NOT going to be political speak, it's a legitimate question.
So, if these kind of statements are "extremist" as my "idiot box" keeps saying they are.... Does that mean non-extremist, and there in "good" direction is; - Spend more - turn OFF more oil, OFF more coal, OFF more nuclear and just energy in general - more open boarders, is the good/smart way to go ????
Seriously. Am I the only one who's taken the defining of all that's been called "extremist" and thought "ok, so, your saying do the opposite then?" and thought out what the opposite is?
Because the opposite seems crackers. Just, obviously crackers, where if anyone said it out loud they'd get laughed out of a room because the economic impact of destruction is obvious.
I want MORE rental properties, so in a way that's cheering for calamity to some extent. But I want great tenants, and for great tenants they need good blue-collar income. So, in that I am rooting for strong economy. But I want renters, so, not too strong, lol.
Soooo apparently I am a house divided, lol. I would like a horrible, great and ok economy, lol.
Why would you think prices "can't" stay at this level, or rates "can't" stay at this level?
With the direction of things now, I am 98% certain that prices will not only stay at this level, but go up MORE.
The problem with the notion your using, is your basing a sense of pricing, off yesterdays income. And while todays income, may be from yesterdays negotiation of income, the issue is price direction is reflective of TOMORROWS income.
And Wage Inflation is steadily raising tomorrows income 20-30% right now as we speak.
So, with incomes up 20-30%, does it really make sense to say prices "must" come down, when people are earning more?
I get where your coming from, your venting the whip-lash and still in a daze from it, as many are. But fact is, wage inflation is here, it's no longer a forecast, it's happening, and once the genie is out of the bottle there no stuffing it back in.
So, buckle up, prices are destined to go up MORE. Raise COGS and the consumer price will go up as well. There is a feed-back loop to inflation, and we are just in one of the early waves, #3, of such.
It starts as wave #1, mass liquidity injected into system that spurs consumer activity.
Which get's wave #2, mass inflation fueled by #1 facilitating supply shortages and the two with a feed-back loop making #2, mass inflation, which is prices running up, way up.
Which leads to wave #3, Wage Inflation. Persons feeling the squeeze of prices, press employment for more income to counter-weight. And in a labor shortage environment, this too has it's own feed-back loop which forces employers to relent to wage-inflation demands, which increases COG's and causes.....
Wave #4, prices go up yet again but this time as supply exists it's amplitude is a bit less, but it's pressed by wage inflation in 2 ways of increased COGs, and more consumer liquidity/affordability from wages inflating.
And these waves repeat, in cycle, over and over and over again. It's a freight train, Fed applies the "rate" breaks but it does not stop on a dime, it's has momentum that carries it and has to be depleted, which takes time, wave cycles to wash through system.
This is why the Fed said they were trying to fight wage inflation, to stop the next wave in the cycle, or to lesson it, to lesson the following inflation to follow, and all following cycles. Because the Fed can't waive a wand and create surplus of supply in material goods or labor, which would also do it, but those are both in shortage, so the only tool left is rates, to slow liquidity, slow everything.
Home builders are not idiots, they are throttling supply, there not going to allow supply over-runs. So guess what, rates will stay up, possibly even higher, because it IS sustainable at these rates, as current activity has proven.
It's renters who will next feel the squeeze, as supply for renters becomes ever more constricted. And it will. Forcing rental rates up, even though affordability is already strained, supply-demand will rule.
And this is why you see the "big boys" building apartments today, as you scratch your head wondering what "idiot" is throwing away $ on building MFH today, at todays rates. There not idiots, they just happen to know something you don't. And so do their backers.
This today is a "Perfect Storm" scenario. The complexity makes '08' look like little leagues in comparison.