July CPI Cools, Home Sales Slow: What It Means for Your Next Deal
Good week of data if you're buying or refinancing anything right now. Here's the short version!
Inflation
Consumer prices rose just 0.1% in July, putting annual inflation at 3.4%. Core inflation, which drops food and gas out of the math, came in at 2.5% for the year. That's the lowest since March 2021.
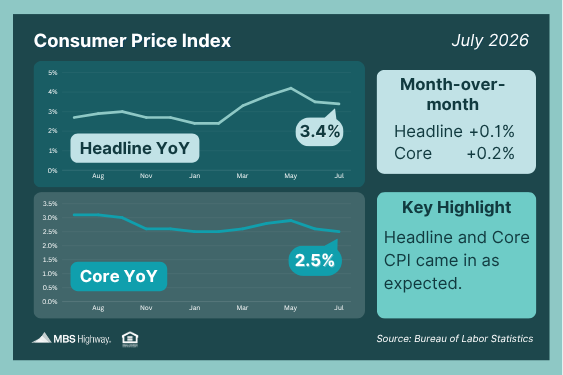
Look at only the last three months and the pace works out to about 1.6% a year, under the Fed's 2% target. Wholesale prices, meaning what businesses pay before goods hit shelves, were basically flat.
Why you care: mortgage rates follow inflation more closely than almost anything else. When inflation cools, the bond market that funds mortgages gets more comfortable, and rates tend to ease. Not overnight, but that's the direction.
The Fed
A few Fed officials wanted to raise rates back in July. Their case was that inflation was too hot and hiring was too strong. Since then the July jobs report showed actual job losses and inflation came in soft twice. Both halves of that argument fell apart. Notes from that July meeting come out Wednesday.
Housing
Existing home sales dropped 1.7% in July, the second monthly decline in a row, down to a pace of about 4.06 million homes a year. Sales are still up 2.4% for the year though, and inventory fell 1.9%, so it isn't just buyers stepping back. Sellers listed less too.
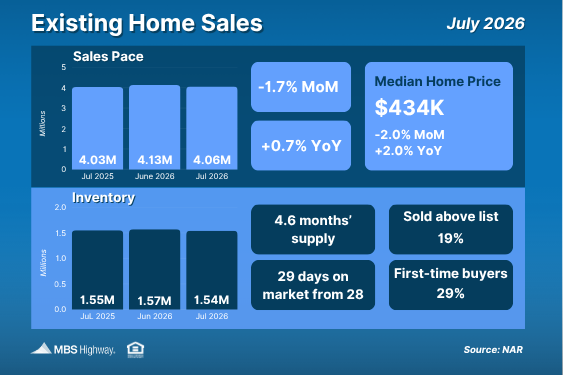
NAR's chief economist Lawrence Yun called sales "remarkably stable" and said things could really move if rates get closer to 6%.
Prices kept climbing. Up 0.3% from May to June, up 1.2% from a year ago, and up 1.7% across the March through June stretch.
The Consumer
Retail sales fell 0.6% in July. Cheaper gas explains part of it, but online sales dropped too, down 1.3% over the past two months. New unemployment filings are still low around 209,000, but people already collecting sit at 1.78 million, meaning it's taking longer to find work.
What I'd Take From It
Fewer deals closing, less inventory, and a consumer starting to pull back. That's not a fire sale setup, so don't wait for sellers to panic. But you're bidding against fewer people than you were in spring.
The bigger point: if inflation keeps running this cool, rates should follow eventually. Underwrite the deal at today's rate so it works today. If rates drop later and you refinance, that's a bonus, not the plan.
This Week: Homebuilder confidence Monday. Housing Starts, Building Permits, and Pending Home Sales Tuesday. Fed meeting notes Wednesday. Unemployment claims Thursday.
Anyone adjusting their buy criteria with sales volume this soft, or sitting tight until the Fed notes drop?
