The Real Cost of a Fix & Flip – What Do You Include in Your Analysis?

The Real Cost of a Fix & Flip – What Do You Include in Your Analysis?

Charles WalkerBusiness Member
Real Estate Consultant · Member since 2025 · 39 posts · 2 votes

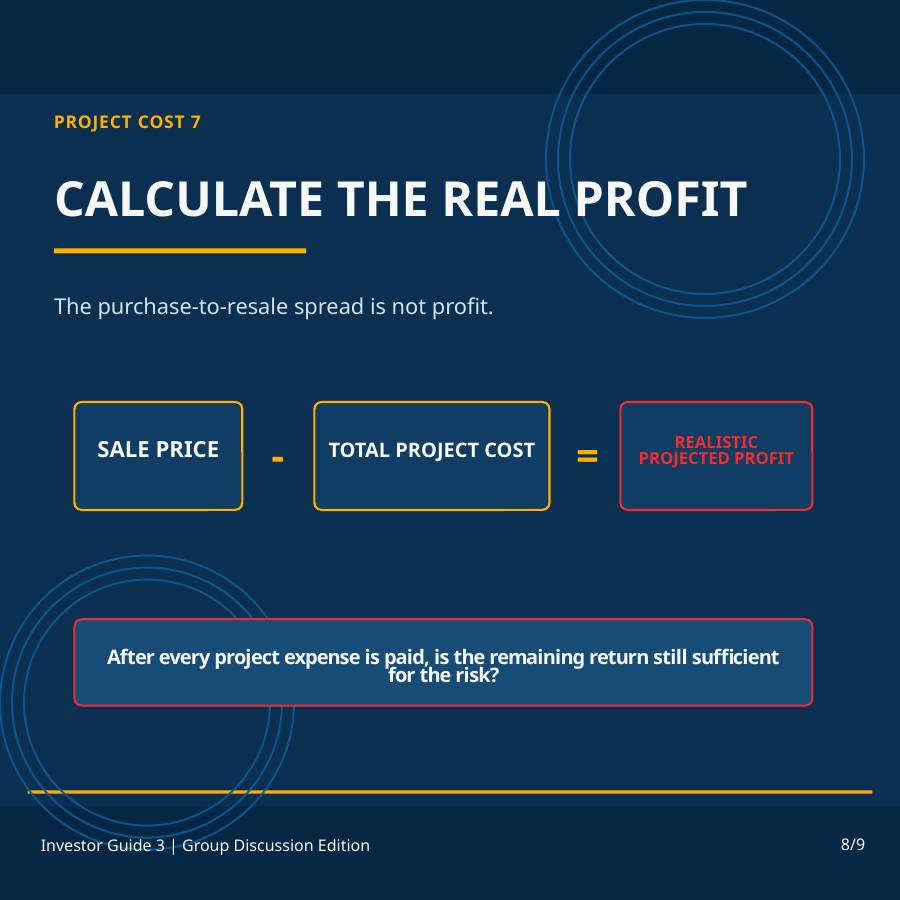
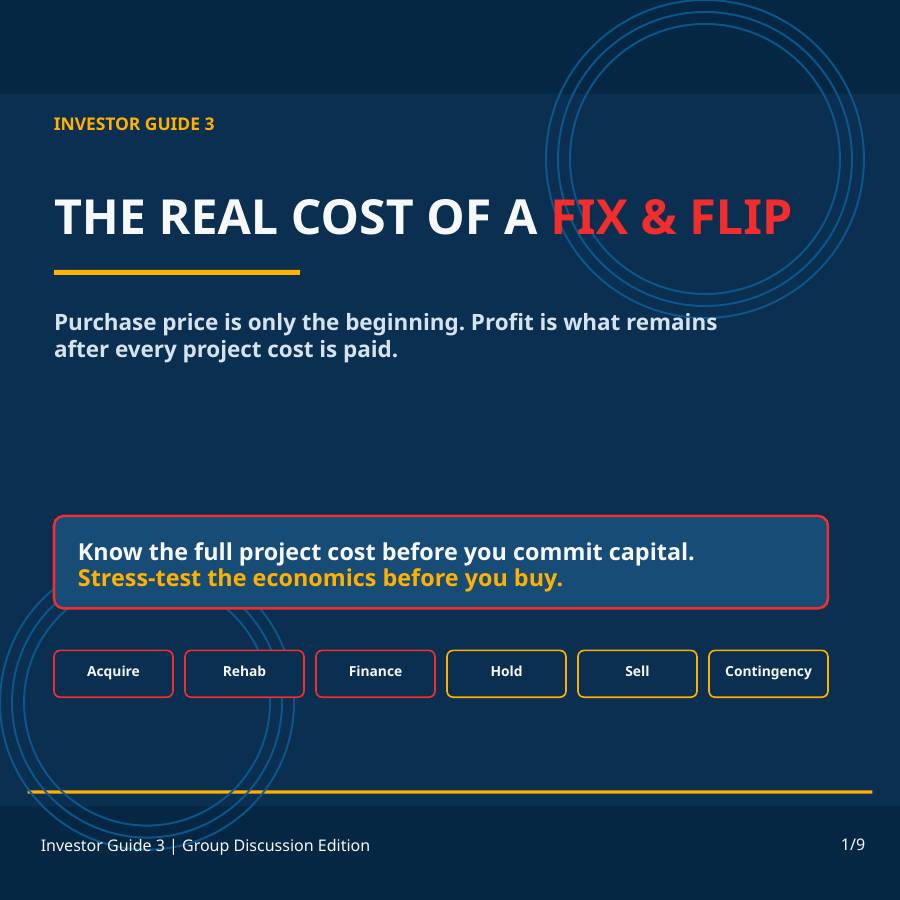
I've been looking at the real cost of fix and flips and I think one of the easiest mistakes is looking at purchase price, rehab and ARV and thinking the difference is profit.

Once you add closing costs, financing, holding costs, selling costs and unexpected repairs, that number can change pretty quickly.

For those of you who have done several flips, what cost has surprised you the most?

One of the easiest ways to overstate a flip is to treat the purchase-to-ARV spread as though it represents profit.

The project has to absorb several categories of expense before you know what may actually remain:

  • Acquisition and closing costs.
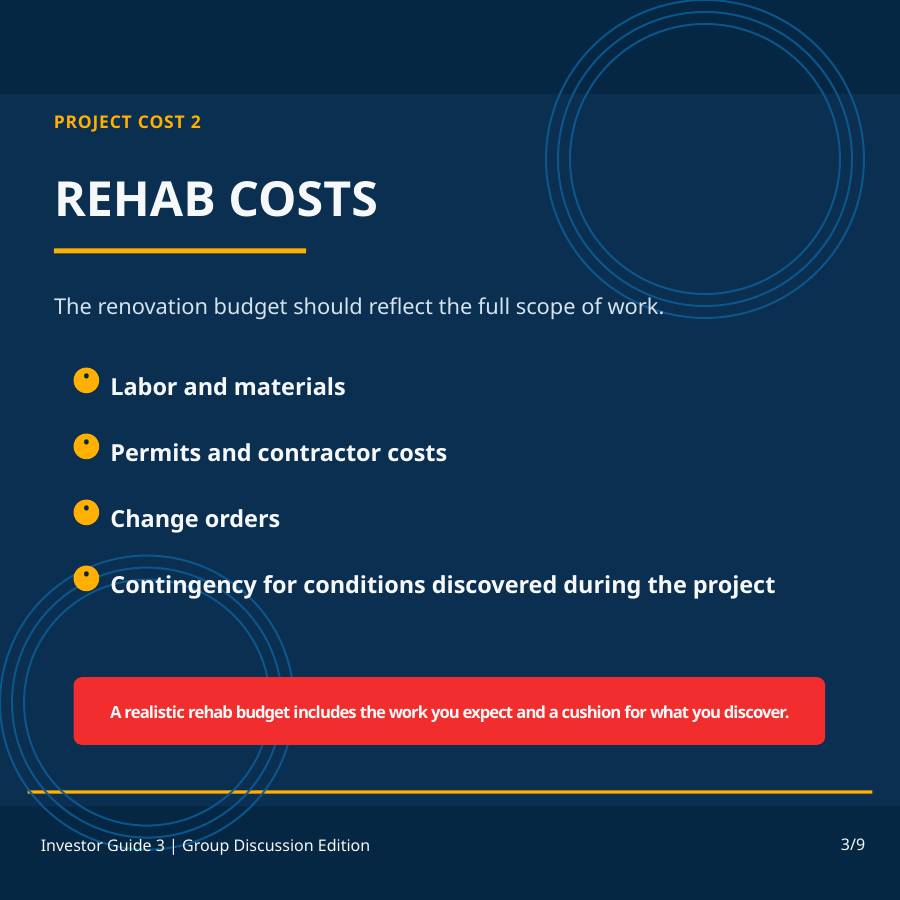
  • Rehab labor, materials, permits, contractor costs, change orders, and contingency.
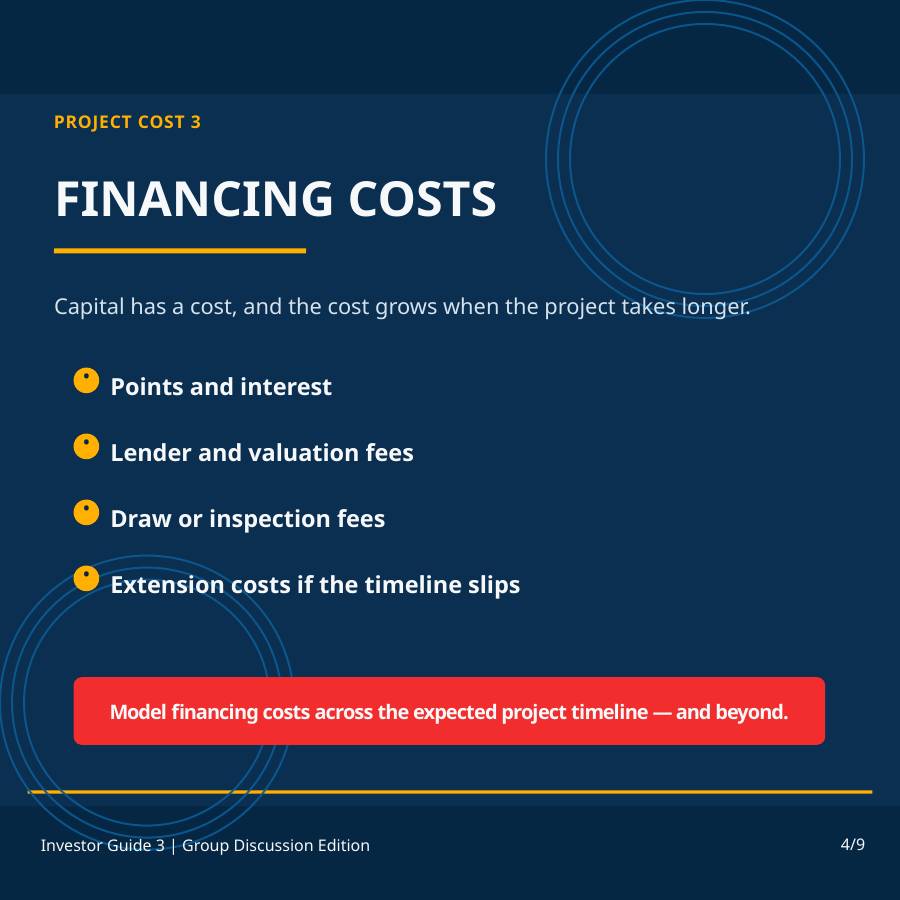
  • Financing costs over the expected life of the loan.
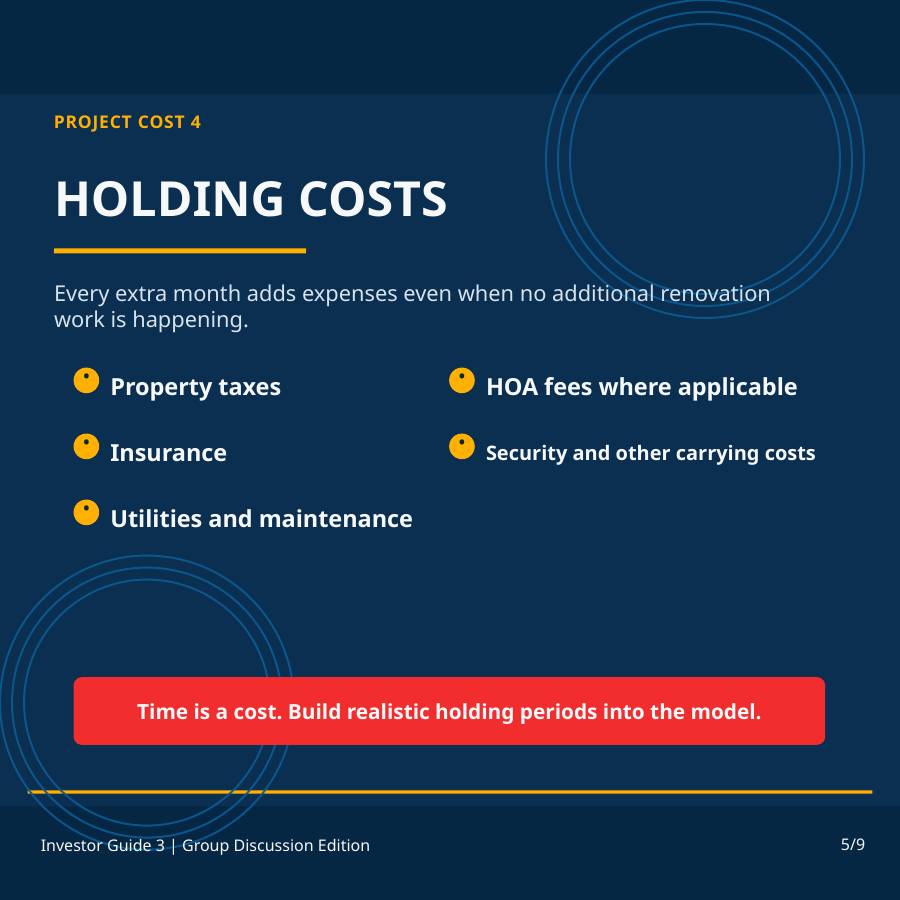
  • Taxes, insurance, utilities, maintenance, and other holding costs.
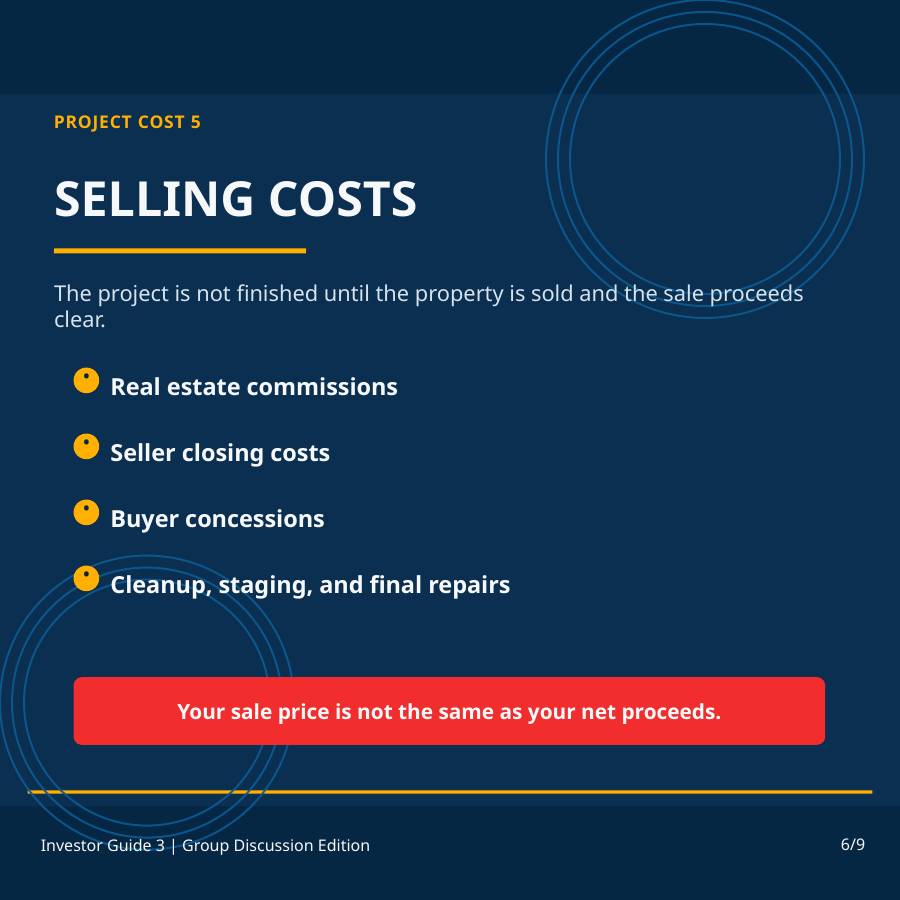
  • Selling expenses and buyer concessions.
  • The financial effect of delays or newly discovered repairs.

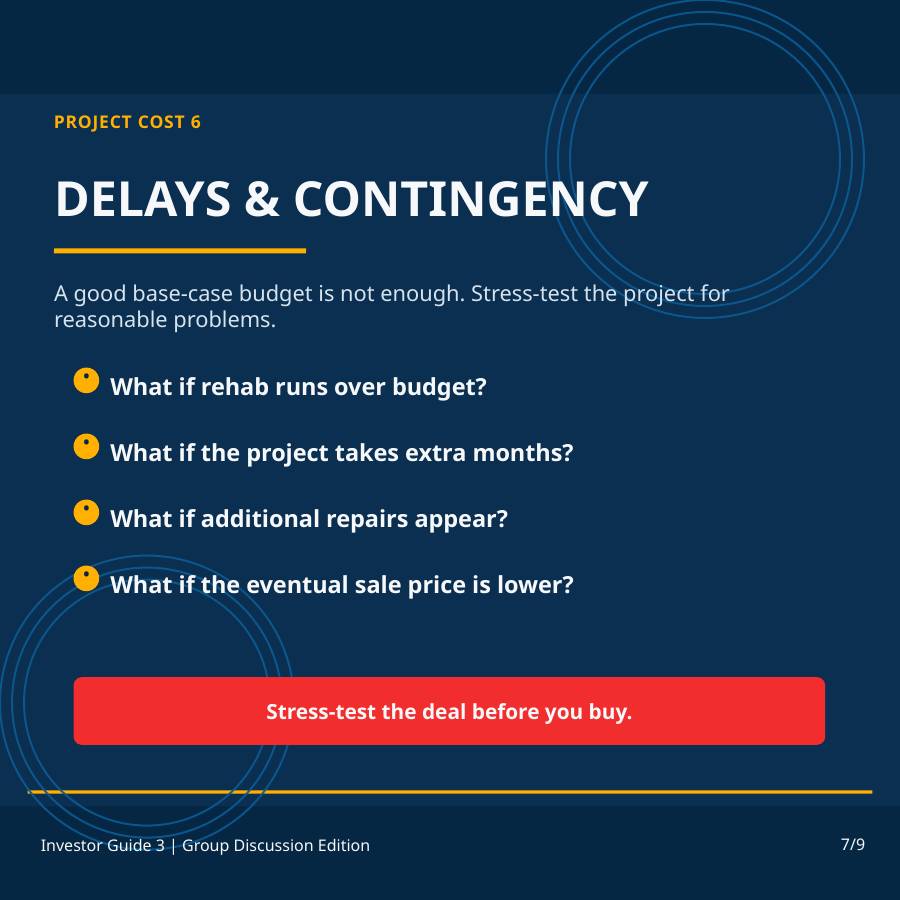
I also think it is useful to stress-test the deal rather than rely only on the base case: What happens if the rehab is over budget? What happens if the project takes three months longer? What happens if the eventual sale price is lower than projected?

The objective is not to prove that the deal works. It is to determine whether the economics still make sense when reasonable things go wrong.

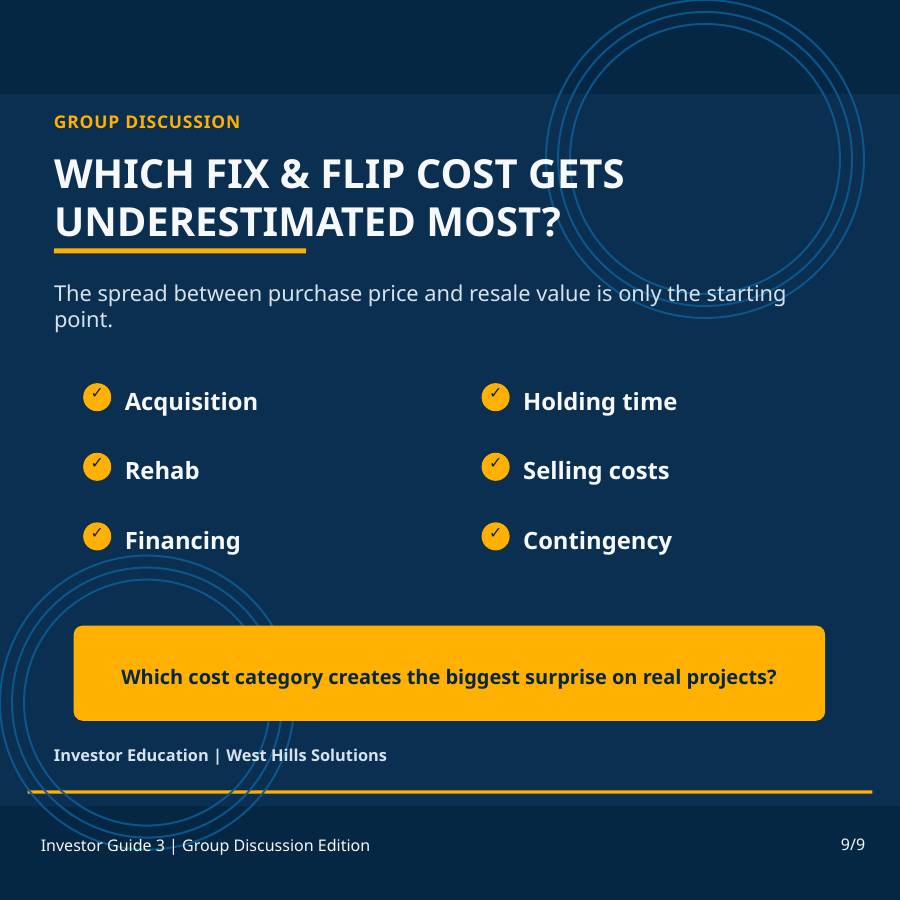
Question for the group: Which cost category do you see investors underestimate most often — rehab, financing, holding time, selling costs, or contingency?
1Reply
303 views

3 Replies

Jump to latestLatest
  • Accountant · San Francisco, CA · Member since 2026 · 119 posts · 72 votes
    1mo

    Hi Charles, yes, agree. Holding time is the most underestimated cost. A delay compounds three expenses at once: ongoing debt service, fixed holding bills, and trapped capital. When timelines slip, carrying costs consume profit margins long before market shifts occur.

    • Charles WalkerBusiness Member
      OP
      Real Estate Consultant · Member since 2025 · 39 posts · 2 votes
      1mo


      Absolutely, Kasing. That compounding effect is exactly where many otherwise profitable flips get into trouble.

      Investors often budget the obvious monthly carrying costs, but the cost of trapped capital is easy to overlook. Every additional month not only adds interest, taxes, insurance, utilities, and maintenance—it also delays the investor from redeploying that capital into the next opportunity.

      That is why I believe the timeline should be treated as part of the financial model from the beginning, not simply as a construction estimate. A deal that works at a 4-month hold may look very different at 7 or 8 months.


  • Drew SygitBusiness Member
    Property Manager · Royal Oak, MI · Member since 2012 · 13k+ posts · 9k+ votes
    1mo

    Not budgeting a 10-20% contingency category for the inevitable surprises.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.