Rental Property Investor · Columbia, SC · Member since 2020 · 244 posts · 275 votes
So I am going through the lending process with another lender and we just got my rental appraised last week. Now Quicken, who has the current mortgage, has gotten the notice that I’m about to pay off the loan and then they call me offering me a deal. My current rate with the new lender is 3.875% for 30 years. Today, quicken offers me 2.99% for 30 years. I must admit the Quicken is giving a much better deal, but I don’t want to burn the bridge with the lender that I’m working with now. When I called Quicken back in early January they said that they weren’t doing a cash out refi‘s on rental properties, but the lender I’m working with now said he could and we moved forward.
Should I ditch the lender I’m working with for the better deal with Quicken? I don’t want to burn a bridge or ruin my name. I would like to work with the current lender in the future, but if I bail so far in the process I’m not sure if he would want to.
Rental Property Investor · Shrewsbury, MO · Member since 2012 · 4 posts · 0 votes
5y
Don’t stick with a lender, no matter how chummy they are with you, if you can save thousands or even hundreds somewhere else. And it’s not just about the money. The best deals are about favorable terms. No pressure-payment penalty? No down-payment?
Investor · Bethlehem, PA · Member since 2016 · 929 posts · 951 votes
5y
@Ryan Copeland What are the fees/closing costs associated with both? I was in the exact same situation last year. Quicken's fees were 2X more than the other lender and also required a lower LTV than the other lender. I ultimately chose the lender.
Your situation may be different. I wouldn't be concerned about burning a bridge. I would tell your other lender the exact terms Quicken is providing. If Quicken is a better deal they will understand. I'm sure they will be happy to take your business on your next deal that comes up.
2.99% on an investment property with Quicken?
I would ask to see an estimate. I would imagine with that quote you are probably paying multiple points.
You're right, I am. It's not that good of a deal.
That is what I figured. Points and fees are a sunk cost, so I try to minimize them. Odd are good you will either sell the property or refinance again before you even hit the break even point on the fees. A loan is more than the interest rate. Many of these national lenders nail you with upfront fees to advertise low rates. Sometimes they say "no cash to close" but that means the fees are rolling in, so you pay for them over 30 years.
Lender · Lewis, CO · Member since 2017 · 218 posts · 159 votes
5y
Quicken is not beating anyone by 7/8th's of a point comparing apples to apples; they hardly ever beat anyone by even a little bit so I'm guessing that what you are seeing is that you locked at the high a few weeks ago around the end of February and then rates dropped 3/8ths to 1/2 a point over the next 3-4 weeks. So your lender is higher because the market was higher. It's an unfair comparison.
You should try and renegotiate the rate. Some lenders won't do a renegotiation. If they won't renegotiate then tell them you've found a much better deal elsewhere and see if that changes their tune. Most lenders have ways of trying to keep a deal that this happened to, but it's more work so they usually try and avoid it unless a client brings it to them first. You shouldn't be worried about hurting your loan officers feelings, that's funny though.
Lender · Nationwide Lender · Member since 2019 · 391 posts · 140 votes
5y
Any lender can offer any rate they want, it is all about the overall cost. Things to compare are Origination fees, title charges, points for the rate, and the time it will take to complete the refinance. Do you have a locked rate with the current lender? Is quicken offering to be able to lock you at 2.99 immediately, and also close on time? If they cant close then its going to cost more.
Investor · Worcester, MA · Member since 2020 · 1k+ posts · 1k+ votes
5y
@Ryan Copeland I ran into this situation with my last house hack. I was offered a 0.5 % lower rate via a FHA loan from another lender early in the process. The previous lender I worked with was providing support for months so I did not want to ditch him without giving him an opportunity to match. I presented my original lender with the quote from the new lender and they matched the offer at no cost. If this lender has been great to work with and has provided excellent service, I would at least give them the opportunity to match the rate. Just make sure you provide the detailed quote so you are comparing "apples to apples".
I second the idea of giving your first lender a chance to match. Also check the Quicken offer for pre-payment penalties or (I'm dating myself here) computing interest according to the Rule of 78s or the Rule of 88s.
Rule of thumb: Your new payment should save you your origination and closing costs (fees, title, survey, points, etc., etc.) in three years.
Lender · Washington DC · Member since 2015 · 2k+ posts · 2k+ votes
5y
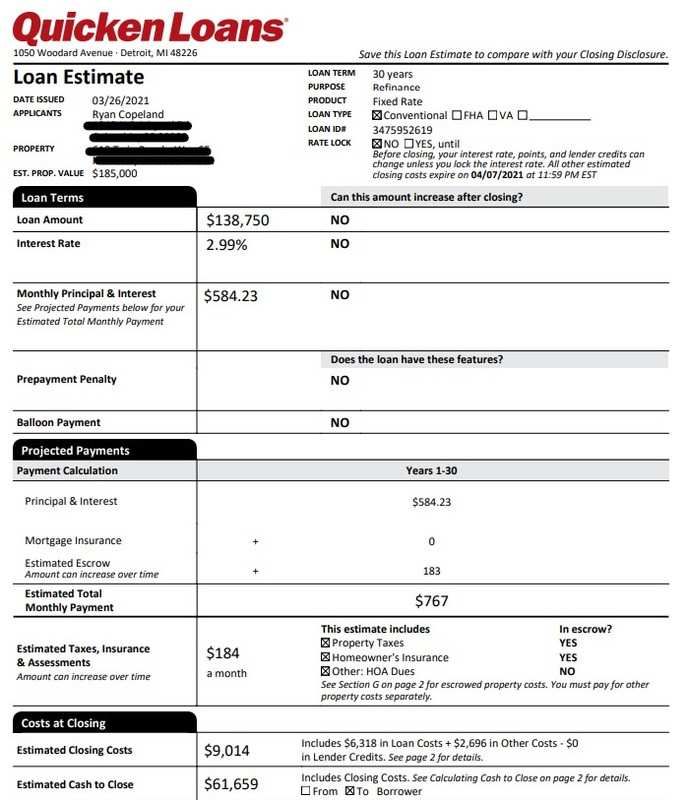
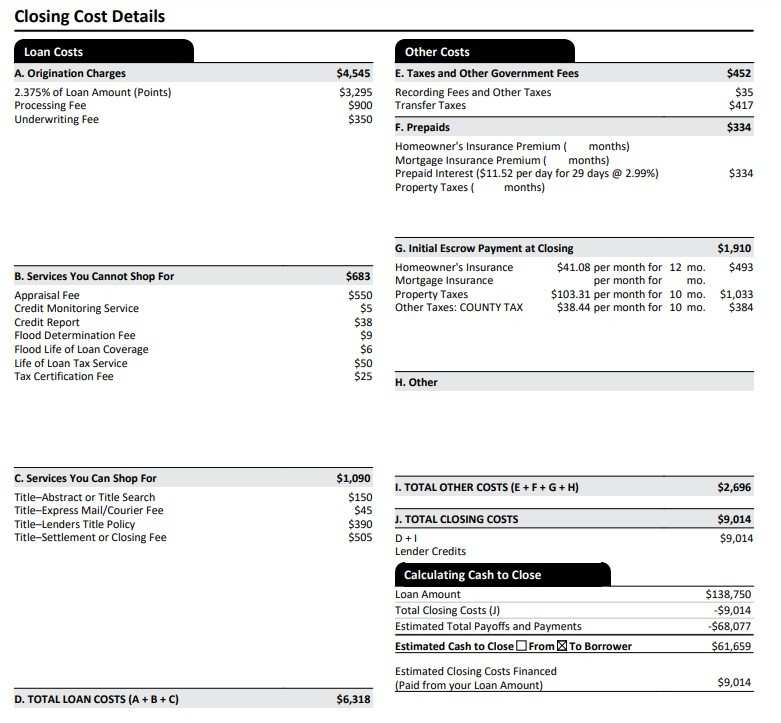
What is missing on the Quicken quote: non owner/ investment pricing add is 3.25; cash out if middle FICO is above 764 .625; refinance .5 - ad d those to 30 year par rate of 2.99 that's 4.725 points which will take ten years or more to recoup the cost. You are better off with 5 at zero points
I wager Quicken will not honor a 30 day lock at 2.99 30 year with that small of points. You need a commitment letter and rate lock.
Rental Property Investor · Columbia, SC · Member since 2020 · 244 posts · 275 votes
5y
@Caroline Gerardo my credit score is still in the excellent category. It should be above 760, but may have dropped since I’ve had a lot of inquiries lately. After I analyzed the numbers that quicken offered, it’s definitely not a better deal. The additional $3300 I would have to pay them in closing costs would take me 9 years to recoup in the $30 of monthly savings their offer would give me. The rep on the phone kept trying to focus on the “lower payment amount” and I got agitated because I felt like she was insulting my intelligence. The math just doesn’t make sense! It’s not a good offer. They sent me another offer dropping some of the points I had to pay, but increasing the rate. I didn’t even look at it yet.
I second the idea of giving your first lender a chance to match. Also check the Quicken offer for pre-payment penalties or (I'm dating myself here) computing interest according to the Rule of 78s or the Rule of 88s.
Rule of thumb: Your new payment should save you your origination and closing costs (fees, title, survey, points, etc., etc.) in three years.
No prepayment penalty, but it’s just not a good offer
Quicken is not beating anyone by 7/8th's of a point comparing apples to apples; they hardly ever beat anyone by even a little bit so I'm guessing that what you are seeing is that you locked at the high a few weeks ago around the end of February and then rates dropped 3/8ths to 1/2 a point over the next 3-4 weeks. So your lender is higher because the market was higher. It's an unfair comparison.
You should try and renegotiate the rate. Some lenders won't do a renegotiation. If they won't renegotiate then tell them you've found a much better deal elsewhere and see if that changes their tune. Most lenders have ways of trying to keep a deal that this happened to, but it's more work so they usually try and avoid it unless a client brings it to them first. You shouldn't be worried about hurting your loan officers feelings, that's funny though.
The legal limit on lender fees for rental properties is 5%.
So on a $500k loan, that would be $25k in junk fees.
That's also how you optimize for the gov't "APR" number. Slightly lower the rate, but make the fees absurd. A sexy "APR" is what is spit out.
Post pages 1 and 2 of the Quicky LE. Those gov't disclosures exist for a reason.
Please see the thread for the images. I’ve posted them.
The reality if you moved forward would probably be worse than that. That still looks like either owner occupant, or vacation home, financing. It does not look like rental property financing, which is worse.
But hey, at least you'd get to say you helped sponsor the Super Bowl with your points and fees. :)
Something super frustrating on my end as a loan originator. You made this thread on biggerpockets dot com. Boom, you just saved yourself several thousand dollars (and last I checked, biggerpockets.com did not charge you anything to be able to make this thread, it is worth noting :). A good majority of people would have just looked at the rate and stopped there, without making this thread. That's why they are the largest and most profitable mortgage enterprise on the entire planet. Their profitability per loan is about 3x the industry norm, imagine if you could charge your tenant's 3x the going rate for a similar rental unit! By being about 75% (2019) to 88% (last quarterly call report to stock owners) refi, where you can just bake the unusually high junk fees into the loan balance (unlike purchase mortgages), that's exactly where they are at in the market. It would be like if you charged slightly below average rent, but had a 4 month non-refundable security deposit, and people didn't notice b/c you could somehow take that security deposit out of their retirement accounts (home equity).
It's super tempting just to play the same game they play - tack a couple points on, and focus on the rate and monthly payment.
In reality, I do not do that (and I often lose the business of low information borrowers as a consequence), but I do own some Quicken/Rocket stock. What's bad for a customer of a business, is concurrently often good for an investor in a business. :) And if you develop that model where you can plunder a renter's retirement account for a non-refundable 4 month security deposit (the Quicky model for refis, using your hard earned home equity instead of your 401k), please let me know, and I'll invest in your REIT too, because it's the exact same thing!