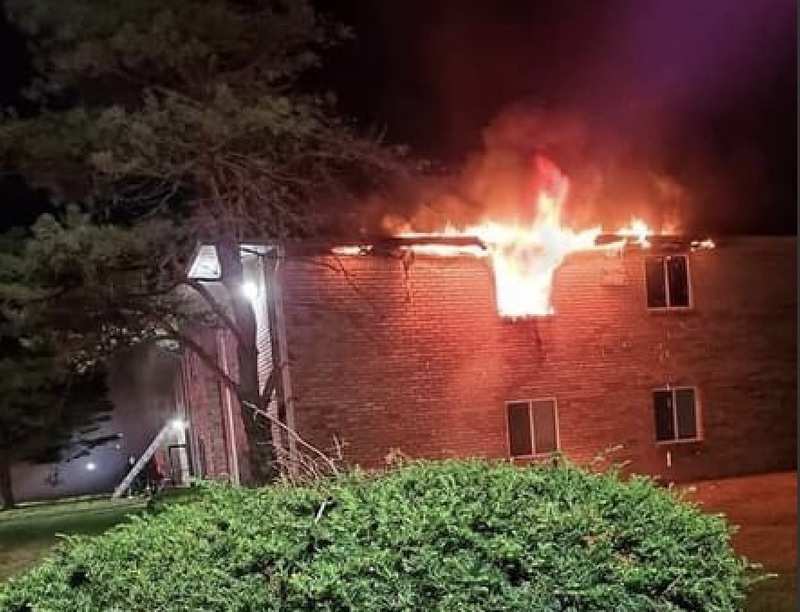
House Burned right before Insurance Policy was taken Out :(

House Burned right before Insurance Policy was taken Out :(

Real Estate Investor · Des Moines, IA · Member since 2016 · 922 posts · 533 votes

Hi everyone.  It's been awhile since I was on here.  I'd value any input.

We had a house where we were ALMOST ready to start painting, and I hadn't quite made the call to get an insurance policy going yet, and it had a major fire that doesn't look salvageable (total loss). It's a very heavy hit financially for us, and this asset was owned under a self directed IRA.

The investigation is still ongoing but so far the fire and police sides have informed me based on a couple items so far, that they suspect Arson.

I can be a little aggressive in how I handle certain contractor items, and I have maybe 3-5 relationships just in the last year where I can imagine, perhaps, that someone might have felt aggrieved.  Anyways, now I'm really trying to think in terms of controlling this risk in the future.  

We are going to have to demolish the house which is of course more salt in the wound.  I had actually thought in terms of getting insurance set up at least a couple times just in the last couple weeks (we were right at that point) ---- 

Here are my thoughts/questions for everyone:

Are there insurance policies that we can take on - for the really aggressive 'down to the studs' kinds of projects that we are taking on, in the future - and then perhaps transition the policy into a more traditional homeowners' policy once it's a bit more finished (I've been told in the past those are available when you have all the drywall work done often)?

I'm trying to search for ways to help handle this kind of risk but borderline blaming myself.  I think I'm having trouble separating the two.

Generally if anyone has any thoughts that might help me to psychologically move on, I'd appreciate it.  This just happened two days ago but I can already tell that although financially we can absorb this, psychologically it is impacting my desire to get involved / continue down this road.  It's just such a bad feeling to have that much time and effort and money into something and to know someone made the choice to burn it all down

Protecting our other assets and other two ongoing projects now is top of mind.  I'm thinking, cameras, adjusting our contractor onboarding, adjusting site security protocols, etc.

I'd appreciate thoughts on ways people have handled this stuff in the past.

2Reply
60 views

Most Popular Reply

Greg ScottPro Member
Rental Property Investor · SE Michigan · Member since 2014 · 4k+ posts · 6k+ votes
5y

Sorry for your financial loss.  Instead of being a devastating blow, I hope it simply becomes a lesson that propels you to bigger and better things in the future.

When you have a house under major reconstruction and vacant, you should have a builders risk policy.  Your insurance professional should be able to help you with this.  If they are not familiar with this sort of thing, you have the wrong insurance broker.  Find one that is investor-friendly.  A good broker can help you find the right policy for any and every property so that you have protection against catastrophic loss.

See this reply in the discussion

11 Replies

Jump to latestLatest
  • Greg ScottPro Member
    Rental Property Investor · SE Michigan · Member since 2014 · 4k+ posts · 6k+ votes
    5y

    Sorry for your financial loss.  Instead of being a devastating blow, I hope it simply becomes a lesson that propels you to bigger and better things in the future.

    When you have a house under major reconstruction and vacant, you should have a builders risk policy.  Your insurance professional should be able to help you with this.  If they are not familiar with this sort of thing, you have the wrong insurance broker.  Find one that is investor-friendly.  A good broker can help you find the right policy for any and every property so that you have protection against catastrophic loss.

  • Bonnie LowPro Member
    Lender · Asheville, NC · Member since 2016 · 1k+ posts · 1k+ votes
    5y

    That's rough. Sorry that happened to you. I'd start by calling your insurance agent. We recently renovated a house that had been red tagged by the City. We had to take it down to the foundation and basically salvaged 1.5 walls. Our hard money lender required insurance on the property and, luckily, our insurance company (State Farm) was willing to write a policy for it. They came out and made a determination of what it was worth at the time (not a lot) and covered it for that.  With the wildfire situation in CA, we were very concerned about protecting our investment. We increased the coverage twice during construction to account for the additional value we put into it to make sure it wasn't under-insured. I don't know if this is relevant to your situation, but it's good to know it is possible to get a policy written when the house is all but torn down. 

  • Real Estate Broker · Member since 2019 · 5 posts · 0 votes
    5y

    Wow, this is a hard lesson and I really hope they can find some footage from a neighboring security system or something to help catch the people responsible.  Over the years we have had to search near and far for an insurance agent to cover some of our tough to place properties.

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    5y

    BUILDERS RISK policy the day you close escrow.. 

  • Real Estate Investor · Des Moines, IA · Member since 2016 · 922 posts · 533 votes
    5y

    Thanks all.  Yes I think it'll be an expensive lesson but I'll look into that as we have two other ongoing projects that I need to get something initiated on.

    Jim

  • Greg ScottPro Member
    Rental Property Investor · SE Michigan · Member since 2014 · 4k+ posts · 6k+ votes
    5y

    FWIW, I feel your pain.  Here is a picture of one of my properties from September.  We are working through the insurance claim now.

  • Investor | Syndicator | Instructor · Cincinnati, OH · Member since 2008 · 435 posts · 198 votes
    5y

    @Jay Hinrichs Ditto. This is just real estate 101 chapter 1.

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    5y
    Originally posted by @Bill P.:

    @Jay Hinrichs Ditto. This is just real estate 101 chapter 1.

    ya and it not expensive.. I pay 750.00 per year for 300 to 400k coverage for a new build.. 

  • Insurance Agent · Pensacola, FL · Member since 2019 · 2 posts · 1 vote
    5y

    @Jim Goebel

    Echoing what my fellow constitutes are saying... a builders risk policy is what is needed for new builds or in your case a total reconstruction.

    On day of closing of a investment property that you are planning to flip or do renovations to, we recommend having a vacant home policy set up to protect your asset. They can be for as little as 3 months, however are more expensive because it is obviously riskier to insure a vacant property than an occupied one.

  • Jason BottPro Member
    Insurance Agent · Nationwide · Member since 2014 · 2k+ posts · 1k+ votes
    5y

    @Jim Goebel sorry to hear of the fire.

    There are insurance programs set up for flipping that insure the property if Vacant, under Rehab or Occupied.  Unlike a traditional Builders Risk policy, the policies are billed monthly so you do not need to be locked into a specific timeline.

    I will send you info on the program my clients use.

  • Insurance Agent · Norwalk, CT · Member since 2016 · 2k+ posts · 1k+ votes
    5y

    Jim,

    So sorry that this happened.  I echo the recommendation of a builders risk policy.  The traditional builders risk policy was designed for ground up construction.  The type used for a rehab is often referred to as a Renovation Builders Risk.  It provides coverage for the existing structure and also for the additional materials being put into the building.  Most include limits for materials in transit and for those stored at the job site.   Don't forget that you also need Liability coverage for the location.  Some Builders Risk policies can include it while others will require a separate policy.

    If there was a Mortgage on the property the bank may have some coverage.  The Mortgagee may have a blanket policy that protects them if you do not have insurance.  

Join the conversationCreate a free account to reply, vote on answers and follow this thread.