Anyone request loan forbearance / delayed payments?
Most Popular Reply
Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes
6yThere is unfortunately a lot of misinformation by supposed experts here on this thread. I strongly urge you all to look at the text of the new CARES act.
Bottom line - if you have a federally backed mortgage (Fannie/Freddie) - you will get forbearance guaranteed with no documentation needed, no penalty, no interest and not affect on your credit.
Here is the relevant text:
Forbearances:
Borrowers with a “Federally backed mortgage loan” experiencing financial hardship due to COVID-19 may request forbearance, regardless of delinquency status. To request a forbearance, the borrower must submit a request to his or her loan servicer and affirm that he or she is experiencing financial hardship during the COVID-19 emergency. No documentation other than the borrower’s attestation of financial hardship due to COVID-19 is required.
The borrower is entitled to a forbearance for up to 180 days, and this period shall be extended an additional period of 180 days at the request of the borrower. The borrower’s initial or extended forbearance period may be shortened at the borrower’s request. During the potential 360-day forbearance period, no fees, penalties, or interest beyond the amounts scheduled or calculated as if the borrower made timely contractual payments shall accrue on the borrower’s account.
Reciprocally, servicers may not collect any such fees, penalties, or interest during this forbearance period. The only caveats allowing servicers to collect fees, penalties, or interest are that any forbearance request must be made by the borrower and within the covered period.
43 Replies
- Investor · Roseville, CA · Member since 2016 · 893 posts · 1k+ votes6y
@Cliff T. I signed up for forbearance that my lender was offering, but likely will not use it because I don't want to put myself in a hole in 3 months and/or have to sign up for repayment program that will affect my credit. I signed up merely as a 'break here in case of emergency' option if my other income streams fail in the next 3 months that will absolutely force me to not able to make the mortgage payments.
People need to realize the rules and limitations of these forbearance programs before they just decide to stop paying their mortgages.
Cheers
- Hatfield, PA · Member since 2012 · 1k+ posts · 629 votes6y
My long-term rental backup plan makes me still very positive monthly cash-flow. Now if renters start being unable to pay, that is a different story.
- Real Estate Agent · Merritt Island, FL · Member since 2017 · 974 posts · 1k+ votes6y
From what I read, self-employed folk may delay mortgage payments up to 12 months with zero penalty or interest. What I don't know is if that's only for primary homes. No hit to credit either.
Multi-units get an automatic 30-day, but on a case-by-case may get up to 90 days. You must be current as of Feb 2020. Also no penalty or hit to credit.
- 6yGreg CampbellPro MemberInvestor · Park Ridge, IL · Member since 2017 · 23 posts · 6 votes
I agree with @John Crosby. My lender offered me a three month forbearance as well. He said to call back shortly before the end of the forbearance period to see what other options are available. My property manager received deferment where the payment will simply be added to the end of the loan with no adverse credit associated but that option was from a smaller, local bank in which he does a large amount of business.
I plan on taking the forbearance and seeing what options are available when I reach the end of that period. I have read a number of articles that seem to suggest there is a possibility that some type of mortgage deferment could be part of another stimulus/relief package/government directive but that is certainly not written in stone at this point. My thought is that if I do not take the offer of forbearance now I will not have any options later.
I'd love to hear other thoughts on this and what negatives people may believe would accompany taking the forbearance. I've spoken to two accountants that don't believe there will be any adverse effects but my concern is that lenders will look upon the forbearance as a negative in my ability to borrow in the future.
- Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes6y
There is unfortunately a lot of misinformation by supposed experts here on this thread. I strongly urge you all to look at the text of the new CARES act.
Bottom line - if you have a federally backed mortgage (Fannie/Freddie) - you will get forbearance guaranteed with no documentation needed, no penalty, no interest and not affect on your credit.
Here is the relevant text:
Forbearances:
Borrowers with a “Federally backed mortgage loan” experiencing financial hardship due to COVID-19 may request forbearance, regardless of delinquency status. To request a forbearance, the borrower must submit a request to his or her loan servicer and affirm that he or she is experiencing financial hardship during the COVID-19 emergency. No documentation other than the borrower’s attestation of financial hardship due to COVID-19 is required.
The borrower is entitled to a forbearance for up to 180 days, and this period shall be extended an additional period of 180 days at the request of the borrower. The borrower’s initial or extended forbearance period may be shortened at the borrower’s request. During the potential 360-day forbearance period, no fees, penalties, or interest beyond the amounts scheduled or calculated as if the borrower made timely contractual payments shall accrue on the borrower’s account.
Reciprocally, servicers may not collect any such fees, penalties, or interest during this forbearance period. The only caveats allowing servicers to collect fees, penalties, or interest are that any forbearance request must be made by the borrower and within the covered period.
- Specialist · O'Fallon, MO · Member since 2010 · 148 posts · 46 votes6y
If you have a way to manage without doing a modification on the account or a forbearance you are probably better off. I've been an asset manager and once an account goes into delinquency chances are you could face issues you could never imagine. Most banks suck at servicing accounts. It's quite interesting what they get by with as well. If you enjoy the assets you already own seek other methods. That protect you as an investor now and in the future. If you have more than one property perhaps doing a whole new loan would be better. The rates are low. There are loans you can get done that are interest only without balloons. Maybe a blanket loan. Interest only loans vs P/I really puts an investor in money mode :)
- Investor · Columbus, OH · Member since 2017 · 861 posts · 1k+ votes6y
Originally posted by @Alan Ford:
@Kathy Utiss are you saying the banks break the law or don’t follow it properly or what? I don’t understand why anyone wouldn’t take advantage of these options in the short term?
I have to admit, i am incredibly confused on this matter. I read the same thing you did, and to me it looks pretty straightforward. Yet I keep seeing people talking about banks doing something different, eg expecting lump sums or smaller forbearance periods. Is the CARES act actually in effect now? Are the comments about banks doing something different from before CARES passed?
- Investor · San Diego, CA · Member since 2012 · 121 posts · 43 votes6y
Originally posted by @Alan Ford:
There is unfortunately a lot of misinformation by supposed experts here on this thread. I strongly urge you all to look at the text of the new CARES act.
Bottom line - if you have a federally backed mortgage (Fannie/Freddie) - you will get forbearance guaranteed with no documentation needed, no penalty, no interest and not affect on your credit.
Here is the relevant text:
Forbearances:
Borrowers with a “Federally backed mortgage loan” experiencing financial hardship due to COVID-19 may request forbearance, regardless of delinquency status. To request a forbearance, the borrower must submit a request to his or her loan servicer and affirm that he or she is experiencing financial hardship during the COVID-19 emergency. No documentation other than the borrower’s attestation of financial hardship due to COVID-19 is required.
The borrower is entitled to a forbearance for up to 180 days, and this period shall be extended an additional period of 180 days at the request of the borrower. The borrower’s initial or extended forbearance period may be shortened at the borrower’s request. During the potential 360-day forbearance period, no fees, penalties, or interest beyond the amounts scheduled or calculated as if the borrower made timely contractual payments shall accrue on the borrower’s account.
Reciprocally, servicers may not collect any such fees, penalties, or interest during this forbearance period. The only caveats allowing servicers to collect fees, penalties, or interest are that any forbearance request must be made by the borrower and within the covered period.
Are you saying you can get 360 day’s without paying your mortgage and the loans will just get extended by 360 days on the back end?
- Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes6y
@Kevin Boyd right now it’s 3 months no questions asked. The options for payback are up to the bank but I believe most if not all banks are allowing the added terms to be moved to the back of the loan. The law does allow for up to one year though.
- 6yLuke CarlPro MemberRental Property Investor · Tennessee Florida · Member since 2016 · 4k+ posts · 5k+ votes
@Cliff T. I sat on hold for 2 hours for the mortgage I’d be most interested in doing this with. Never was able to speak with anyone. Their website was very clear I wouldn’t qualify for the assistance anyway. At this point my best option is paying my mortgages out of pocket and hoping for the best. The best as of today is that my long term tenants pay rent. We will be fine. Let’s focus on making sure the world is healthy first.
The loan is question is not fanny Freddy. If I can truly get 3 months free now tacked on to the end of my fanny Freddie’s hell yeah. Might as well while I’m still in my 30s.
- Specialist · O'Fallon, MO · Member since 2010 · 148 posts · 46 votes6y
Good evening...Since, about 1994 I've been in the asset management industry. I initially got into the biz via recovery on credit cards. Then the more experience I got the better my opportunities got. In 2001 I started doing recovery work via a 3rd party agency. In February 2004 I found out the agency I accepted employment with never had it in their contract to sell mortgage notes for xyz. Then the other company didn't sell their's but did end up selling theirs. I know it sounds confusing. But in some cases google can be our best friend. I've been documenting my experience since about 2007 when I found out the people wanting to be paid couldn't prove ownership.
I proved this in court. Instead of being made to pay fines as putting fraud into the court knowing it's fraud is supposed to be a $500,000 penalty I was made to be a deplorable. You know being one of America's top asset managers the only way I had to pay to keep my home since they lied depended on me getting an opportunity to get honest business done.
As it really defeats the purpose in having any accredited investor that can spend $150,000 a month on npn or an investor with $10-$50 million per month on deficiency balance notes if you can't get honest biz done!
Needless, to say the attorney that refused to file an adversary when I did my own and put his in with it things went POOF in the East Dist of MO-St. Louis.
Currently, if you put money down to purchase a property it can be up to 30% down. That's to get a loan usually 30 yrs in term on a p/i basis + your taxes+ ins. If when you close on a loan you insure it yourself against default YOU DO some interesting things.
*You INSURE your PRINCIPAL at a discount. (Avoiding Reserves)(TRIPLE A+ RATED)
*You INSURE your DOWN PAYMENT against loss
*You end up with an interest only loan for the lifetime of your loan. Meaning all that principal like 18 yrs WORTH YOU as an INVESTOR keep in YOUR POCKET.
*INTEREST is A YEARLY PAYMENT
* You still gain property appreciation as well
You can only do what you can to protect you. What their offering is short term assistance. Anything that modifies or extends means you owe longer. I've seen things one could never imagine. I respect professionalism as I've always attempted to be one. But unless you want to waste money you don't have I'd get out of any p/i loan and you avoid such catastrophes such as this. As even if a certain percentage get down to paying you should still make enough to pay interest. Which is better than ever chancing default in a cruel world that won't care what your abilities are.
- Specialist · O'Fallon, MO · Member since 2010 · 148 posts · 46 votes6y
This is what they say about the CARES ACT in Texas. I would assume most of the requirements are universal .
https://www.kbtx.com/content/news/Local-bank-to-provide-CARES-Act-loans-to-community-569193501.html - Real Estate Agent · Merritt Island, FL · Member since 2017 · 974 posts · 1k+ votes6y
Originally posted by @Alan Ford:
There is unfortunately a lot of misinformation by supposed experts here on this thread. I strongly urge you all to look at the text of the new CARES act.
Bottom line - if you have a federally backed mortgage (Fannie/Freddie) - you will get forbearance guaranteed with no documentation needed, no penalty, no interest and not affect on your credit.
Here is the relevant text:
Forbearances:
The borrower is entitled to a forbearance for up to 180 days, and this period shall be extended an additional period of 180 days at the request of the borrower. The borrower’s initial or extended forbearance period may be shortened at the borrower’s request. During the potential 360-day forbearance period, no fees, penalties, or interest beyond the amounts scheduled or calculated as if the borrower made timely contractual payments shall accrue on the borrower’s account.
Reciprocally, servicers may not collect any such fees, penalties, or interest during this forbearance period. The only caveats allowing servicers to collect fees, penalties, or interest are that any forbearance request must be made by the borrower and within the covered period.
As an alleged "supposed expert", I'm going to point out that my comment was made based on having already read what you posted. However, this does not clarify if ALL Fannie/Freddie mortgages or if only O/O. There are separate rules for financed multi-units that are nowhere near as lenient, hence the reluctance to assume ALL Fannie/Freddie until that's clarified. Perhaps you know otherwise?
- Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes6y
@Kathy Utiss sorry but you wrote this mountain of information that has literally nothing to do with what we are talking about. Thanks for your resume I guess. Can you comment on the CARES act and the topic ? Thanks
- Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes6y
@Tchaka Owen I have three Fannie Freddy loans - Wells Fargo Gave me three months on all no questions asked. I don’t know what to tell you. This likely doesn’t work for any weird loan schemes I see people talking about.
- Developer · New York City, NY · Member since 2015 · 812 posts · 718 votes6y
If you are having issues already making payment obligations, then you have other things to worry about. I'd not put your lender on notice too quickly if you do not need it. Reason being, they might review your loan or loans after the dust settles and say you are not capitalized enough and call your loan. It's happened in previous recessions, don't exercise that option unless you really need to.
- Specialist · O'Fallon, MO · Member since 2010 · 148 posts · 46 votes6y
Zero coupon treasuries are Triple A Rated, they are issued at a discount and mature in 30 years if those are what you buy to insure your loans. Banks usually use 10 yr treasuries. Letters of credit come in handy as well.
- Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes6y
@Kathy Utiss I literally don’t even know what to say lol. Thanks? I feel like you are just randomly talking about stuff lol.
Regarding the comment about the bank potentially calling your loan. I can’t see how that’s possible when the law clearly says there shall be no penalty or credit impact.
You guys do realize the banks are getting the money from the Fed either way right? Forbearance doesn’t mean they aren’t getting money. The fed is buying MBS by the billions per day.
Bottom line - if you are a Freddy or Fannie loan, call your lender. Worst they can do is say no. Best case - enjoy no payment for a while during the downturn.
- Rental Property Investor · Rockaway, NJ · Member since 2020 · 24 posts · 21 votes6y
@Cliff T. I got off my bank today they were giving me 90 days for parents. And at the end of those days the full money is due upfront. I agree with you not much help here at all. They also suggested at that same time when all the money is due up front if you can’t afford the payment they can readjust the loan and add your owed balance to the backend of your loan amount. That may be an option but unfortunately you’re adding a lot of extra interest to your overall loan value.
- 6yLuke CarlPro MemberRental Property Investor · Tennessee Florida · Member since 2016 · 4k+ posts · 5k+ votes
I’ve been shut down. Again.
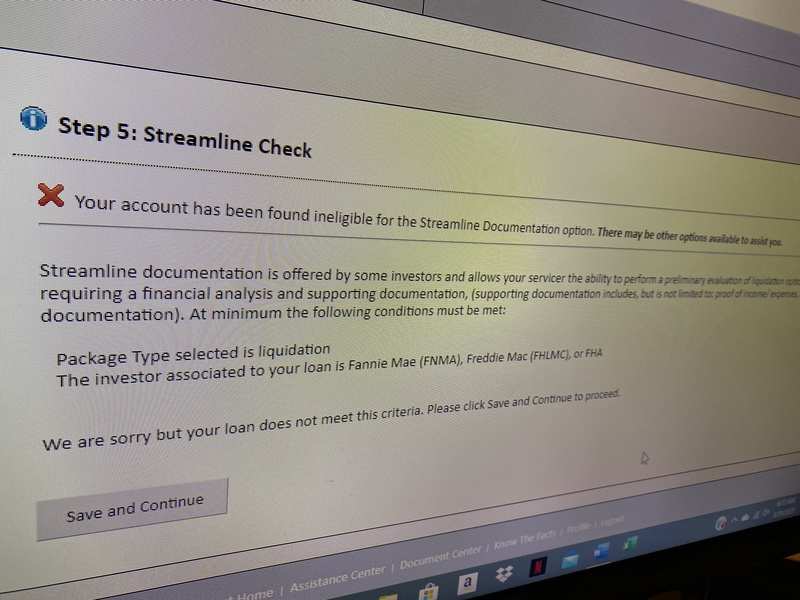
- Rental Property Investor · Member since 2019 · 276 posts · 235 votes6y
All of our lenders have sent us notices that they have a forbearance program of some sort but every single one of them requires payment in full of the months missed at the end of the forbearance term. Pass.
- Real Estate Agent · Merritt Island, FL · Member since 2017 · 974 posts · 1k+ votes6y
Originally posted by @Alan Ford:
@Tchaka Owen I have three Fannie Freddy loans - Wells Fargo Gave me three months on all no questions asked. I don’t know what to tell you. This likely doesn’t work for any weird loan schemes I see people talking about.
I don't know what's behind that, however it likely isn't because of the earlier post. There was a piece about 5 days ago in which a number of banks were doing 3 month delays for CA owners. The noted difference being that BofA was only giving 30 days. That's probably what you're enjoying.
- Investor · Raleigh, NC · Member since 2014 · 38 posts · 30 votes6y
Can anyone find where the CARES Act addresses mortgage forbearance? Despite a number of news articles stating automatic 6 month + additional 6 upon borrower's request, I sifted through it briefly and could not find anything straight from the horses mouth.
Here is a link to Fannie Mae's COVID-19 updates. Likely to be updated next week. A few highlights from the single family lender letter published on 3/18, updated on 3/25:
-loan can be primary, second home or investment property
-servicer is not required to obtain documentation of borrowers hardship (only attestation)
-insight into what payment deferral or loan modification options might look like after forbearance period (looks like there will be options to spread over 60 months)
IMO, as landlords we should take both defensive and offensive measures to manage cash flow. Defensively, we should set aside ample reserves to deal with situations like this. Offensively, we should recognize that today's dollars are far more valuable than tomorrow's dollars. Potentially deferring payments up to 12 months and paying back over the following 60 months could be a pretty sweet deal. Be prepared to pay back as a lump sum if it's required.
Any negative unintended consequences of forbearance would likely be in the realm of obtaining credit down the line. I think the risk is minimal as long as you play by the lender's rules and prepare to pay the accrued balances if needed.
Join the conversationCreate a free account to reply, vote on answers and follow this thread.