Rental Property Investor · San Francisco, CA · Member since 2016 · 215 posts · 42 votes
Just curious if anyone here has gone through the process yet. Everything that I have read thus far states that loan forbearance payments will be due as a lump sump at the end of 30, 60, or 90 days. In other words, you'll need to pay the full payment at end of the forbearance period. That's not very helpful at all and delays the inevitable.
Has anyone successfully reworked their loan terms and instead, find a way to get a lender to extend the term of the loan by 30, 60, 90 days?
Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes
6y
There is unfortunately a lot of misinformation by supposed experts here on this thread. I strongly urge you all to look at the text of the new CARES act.
Bottom line - if you have a federally backed mortgage (Fannie/Freddie) - you will get forbearance guaranteed with no documentation needed, no penalty, no interest and not affect on your credit.
Here is the relevant text:
Forbearances:
Borrowers with a “Federally backed mortgage loan” experiencing financial hardship due to COVID-19 may request forbearance, regardless of delinquency status. To request a forbearance, the borrower must submit a request to his or her loan servicer and affirm that he or she is experiencing financial hardship during the COVID-19 emergency. No documentation other than the borrower’s attestation of financial hardship due to COVID-19 is required.
The borrower is entitled to a forbearance for up to 180 days, and this period shall be extended an additional period of 180 days at the request of the borrower. The borrower’s initial or extended forbearance period may be shortened at the borrower’s request. During the potential 360-day forbearance period, no fees, penalties, or interest beyond the amounts scheduled or calculated as if the borrower made timely contractual payments shall accrue on the borrower’s account.
Reciprocally, servicers may not collect any such fees, penalties, or interest during this forbearance period. The only caveats allowing servicers to collect fees, penalties, or interest are that any forbearance request must be made by the borrower and within the covered period.
Real Estate Agent · Merritt Island, FL · Member since 2017 · 974 posts · 1k+ votes
6y
@Alan Ford - the only difficult thing is your reluctance to understand that what you got was already going on PRIOR to the Stimulus being signed. Not sure how that's not clear to you. Perhaps you should read more.
Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes
6y
@Tchaka Owen I literally just posted the text of the actually senate bill and the citation. Are you blind? You are talking about a CA only program and all sorts of other nonsense. I don’t get it.
It’s like you are dead set against believing for a moment that there could be mortgage relieve in a crisis?
Done responding to you, the text of the bill is there two posts up. Read it or don’t - I could care less.
For the rest of you - If you have a federally backed loan, just call your lender. Again, please note the important of the key fact - Federally backed Loan.
Carrollton, TX · Member since 2015 · 3 posts · 1 vote
6y
We just put our home on 90 days deferred payments with Wells Fargo - they added a simple button on the webpage when you're logged in, takes about 1 minute. Payments are added at the end of the loan and NOT due after the 90 days are up.
Flipper/Rehabber · Colorado Springs, CO · Member since 2015 · 36 posts · 25 votes
6y
@jarobfetters Your capitlizing interest. Which add more cost onto you loan. The principal balance of a loan increases when payments are postponed during periods of deferment or forbearance and unpaid interest is capitalized.
Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes
6y
@Miles McClure not even sure if this is true, but even if it is. That amount of interest amortized over so long is really irrelevant. Not to mention he can just refinance the whole thing later which is what most people do.
Lender · Turlock, CA · Member since 2015 · 46 posts · 33 votes
6y
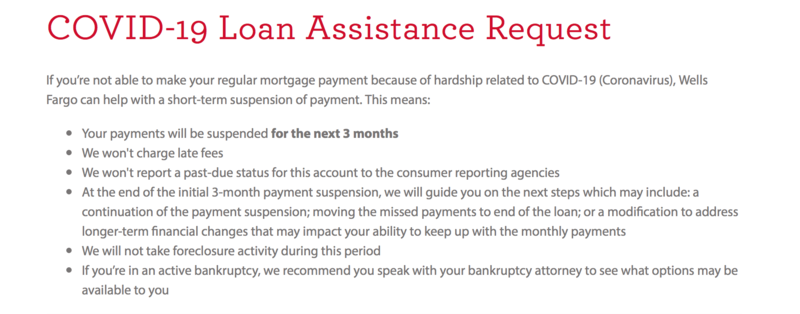
This is straight off my Wells Fargo mortgage online account, however I am still skeptical with the chance of it all being due in a lump sum after 90 days.
Rental Property Investor · Medellin, Colombia · Member since 2016 · 231 posts · 215 votes
6y
@Cliff T. - I applied for the SBA loan and messaged my lender to see what their options were M&T bank. They sent back a message talking about difficult times for owners but it wasn’t clear about their deferments. I will be calling tomorrow and likely sitting on hold for a few hours. Fun!
Rental Property Investor · San Francisco, CA · Member since 2016 · 215 posts · 42 votes
6y
Thanks all for clarifying. For those of you considering loan forbearance, it is critical that you realize that INTEREST IS ACCRUED on your missed payments.
To put numbers on this, on a $1m loan at 3.25% interest, it comes out to $90/day in interest. That's $8100 in INTEREST you have accrued if you keep loan forbearance in place for the full 90 days.
In other words, if you have the means to pay for you loan, you really should not be signing up for loan forbearance. Loan deferment on the other hand is almost always beneficial but not many lenders are offering that right now.
Rental Property Investor · San Francisco, CA · Member since 2016 · 215 posts · 42 votes
6y
@Alan Ford - where are you seeing this? When I log in to my WF account and go through the COVID-19 assistance process, I see the following.. this is loan forbearance and not deferral.
Rental Property Investor · San Francisco, CA · Member since 2016 · 215 posts · 42 votes
6y
@Alan Ford - you should confirm with WF, but what I'm reading from your screenshot is you have loan forbearance for the next 90 days and then you receive deferment on any of those payments. So you are, in effect, accruing interest for the next 90 days. Your monthly payment will then increase at that point to make up for the difference.
Not a bad option they are providing you and glad to see the deferment in writing. But if you have the cash on hand / reserves to make payments now, that's the better route.
Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes
6y
@Cliff T. I think you read it wrong. It’s really simple - no payment for 90 days and then the term of my loan is extended by whatever. And who really cares - that’s like 28 years away. I’ll probably sell it or refi it well before that. On top of that - no credit hit, no penalties or fees. I don’t see the downside to be honest. If there is one please let me know so I figure out what’s best ! I am thinking of going with it for all three of my properties.
Rental Property Investor · San Francisco, CA · Member since 2016 · 215 posts · 42 votes
6y
@Alan Ford I'd highly recommend you chat with your loan officer to get more info on loan forbearance. The more I read about it, the less appealing it is. In particular, the loan modification (e.g. extending your loan terms at the end of the 90 day forbearance) that most banks are offering is not guaranteed -- sounds like consumers may need to "reapply" in some ways similar to a refi (i.e. prove COVID-19 hardship, etc.). Even in the screenshot you provided, the last bullet point clearly says your loan terms may be adjusted if you opt in to the longer-term options. At that point, if you've applied for hardship across all 3 of your loans and have missed payments for 90 days, your interest rate may rise across your entire portfolio.
You also mentioned you're planning to refi down the road... good luck doing that if you have 3 modified loans under your belt due to financial hardship.
There is no such thing as a free lunch. As I mentioned earlier, I think the best advice I have heard across the industry is if you can make your payments, continue to do so. Best of luck.
Rental Property Investor · Temecula, CA · Member since 2020 · 128 posts · 55 votes
6y
@Cliff T. Let’s agree to disagree and leave it at that. If you end up being right me and the other couple hundred thousand Wells Fargo customers will enjoy the class action lawsuit that follows. The letter I received which is signed by the bank is incredibly clear in what it says.
Rental Property Investor · Canton, OH · Member since 2017 · 1k+ posts · 1k+ votes
6y
@Cliff T.
From my experience (outside of FHA loans) every lender is a little different. I have one lender with nearly a dozen loans with who is not offering any assistance. I have a different lender that is offering a 90 day deferment plan, where those 3 months simply get tacked on to the back end of the loan (i.e. they are not due as a lump sum in 90 days). The 1st lender was through a broker, and the 2nd lender was through a small community bank.