Can't pull the trigger because of interest rates??

Can't pull the trigger because of interest rates??

Member since 2023 · 3 posts · 6 votes

I keep on hearing from investors that "I'm waiting for interest rates to go down" or I hear "I need rates to go down for the numbers to make sense". Maybe these investors are saying this because they just got into investing in the past decade where the rates were basically zero or close to it. The past decade of interest rates on a 30 year fix mortgage has never happened before 2008. In the 70s and 80 they were 8, 9, 10, 11, 12, even 18 percent. Now do I think they will continue to reach those levels I don't know I'm not Jerome Powell or the chairman of Chase or BoA. One thing I will say if you are waiting for the interest rates to back down to 2, 3 percent, you might be waiting a long time. All I am saying, is if you are one of those investors that say "I'm waiting for interest rates to go back", you probably need a reality check and do some digging into the history of interest rates. And ask yourself, were we just really lucky in the past decade to be able to lock in a mortgage at 3%. Start to look at the 30 year fixed mortgage rates history graph.

5Reply
78 views

Most Popular Reply

Investor · Austin, TX · Member since 2021 · 9k+ posts · 5k+ votes
3y

Fake investors will say this, if you're not buying right now because of interest rates you are missing out on the biggest opportunity to buy cheap in a long time. 

See this reply in the discussion

30 Replies

Jump to latestLatest
  • Member since 2023 · 8 posts · 7 votes
    3y

    In order for deals to pencil out, we either need to see a decrease in rates (which seems further out rather than sooner) or a decrease in asking prices. Interested to see how creative investors are going to find ways to get deals done.

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    3y

    Neither will have to happen @Zeke Rosenblatt! Investors will have to adjust their expectations. Rates should come down a bit, but that only means upward pressure on prices. 

    The fat days are gone, welcome to the new normal. Talk to a real estate investor in Germany. Cash flow?? - Never heard of that. Their goal is to pay off the property over 30 years, with some help from a tenant. Still beats a savings account!

    Get the best deal you can, while you still can. It does not help to say the deals don't pencil out if at the end of the year you have not met your acquisition goals and prices are up, again. I am in the same boat as everyone else as an investor and I don't like it either. It's frustrating.

    If you think it's hard to find a good duplex, try looking for an apartment complex! While Milwaukee real estate prices are still about 40% lower than the national average, rents keep going up, demand for housing is very strong and: almost nobody is selling. But like I said, welcome to the new normal.

  • Investor · Austin, TX · Member since 2021 · 9k+ posts · 5k+ votes
    3y

    Fake investors will say this, if you're not buying right now because of interest rates you are missing out on the biggest opportunity to buy cheap in a long time. 

  • Member since 2023 · 8 posts · 7 votes
    3y

    @Marcus Auerbach Do you expect lenders to adjust their underwriting requirements? What type of financing options would you recommend in your "Germany" style scenario? 

  • Member since 2019 · 90 posts · 56 votes
    3y
    Quote from @Eliott Elias:

    Fake investors will say this, if you're not buying right now because of interest rates you are missing out on the biggest opportunity to buy cheap in a long time. 

    Perhaps, I’m seeing low inventory in the market I’m in and a lot of “back on market” properties. I’m not sure what the issue is or was but I’m staying put for a bit. Q2 going forward with embarrassing offers and reading through the previous inspection reports.
  • Real Estate Agent · Atlanta, GA · Member since 2020 · 1k+ posts · 1k+ votes
    3y

    @Jackson Risse, as you've essentially summed up, there will ALWAYS be tradeoffs in the real estate space. I concur, the investors who are complaining about interest rates and waiting until they fall do not understand the tradeoffs at all. To those individuals, I ask, remember the market 9-12 months ago when properties would be under contract within 3-4 days 25k-30k over asking with limited contingencies within the offer, some even waiving the due diligence period completely? Do you really want to go back to that hot mess when rates begin to fall? Or would you rather stay active in the market, find a deal that meets your criteria at current rates, and then refinance once rates fall? A strategy that has been utilized time and again by experienced investors. I prefer the latter but that's just my two cents.

  • Lender · Tampa, FL · Member since 2022 · 79 posts · 28 votes
    3y
    Quote from @Jackson Risse:

    I keep on hearing from investors that "I'm waiting for interest rates to go down" or I hear "I need rates to go down for the numbers to make sense". Maybe these investors are saying this because they just got into investing in the past decade where the rates were basically zero or close to it. The past decade of interest rates on a 30 year fix mortgage has never happened before 2008. In the 70s and 80 they were 8, 9, 10, 11, 12, even 18 percent. Now do I think they will continue to reach those levels I don't know I'm not Jerome Powell or the chairman of Chase or BoA. One thing I will say if you are waiting for the interest rates to back down to 2, 3 percent, you might be waiting a long time. All I am saying, is if you are one of those investors that say "I'm waiting for interest rates to go back", you probably need a reality check and do some digging into the history of interest rates. And ask yourself, were we just really lucky in the past decade to be able to lock in a mortgage at 3%. Start to look at the 30 year fixed mortgage rates history graph.


     If you are buying an investment property right now, you can get 2% seller concessions.  This can be used to help buy down the rate.  I recommend doing this on all transactions if you can. Once rates come back down, you will have to get into a bidding war so pick your poison. 

  • Scott TrenchPro Member
    Rental Property Investor · Denver, CO · Member since 2014 · 2k+ posts · 6k+ votes
    3y

    I agree with the overall sentiment. I am still investing in real estate - but on the lending side. Higher rates means better returns for lenders, and the first 25-50% of the risk is taken by the borrower, not the lender. 

    I think that in this environment some of the things that may work are: 

    - Assumable mortgages, especially for house-hackers. Similarly, subject-to deals and seller-financing options will likely find a new heyday. If you can take over existing low-interest rate debt, that's a winner for sure. 

    - Lending - higher returns, more senior position, this is my personal choice in this market. 

    - Buying all cash - if you have the means, and don't care about near-term risk, this can be a great option. 

    - House-hacking - you have to really believe things are going to go down hard for house-hacking to generally not be a better choice than renting or living without tenants subsidizing your housing costs. 

    - "Buying Deep" - if you can find incredible deals, there may still be opportunity.

    This can't last forever, I think that as prices come down in 2023, we will begin a path for good old-fashioned real estate investing deals to resume and average cap rates to move closer to a place where they make sense for investors.

  • Lender · Southwest Georgia · Member since 2017 · 312 posts · 278 votes
    3y
    Quote from @Marcus Auerbach:

    Neither will have to happen @Zeke Rosenblatt! Investors will have to adjust their expectations. Rates should come down a bit, but that only means upward pressure on prices. 

    The fat days are gone, welcome to the new normal. Talk to a real estate investor in Germany. Cash flow?? - Never heard of that. Their goal is to pay off the property over 30 years, with some help from a tenant. Still beats a savings account!

    Get the best deal you can, while you still can. It does not help to say the deals don't pencil out if at the end of the year you have not met your acquisition goals and prices are up, again. I am in the same boat as everyone else as an investor and I don't like it either. It's frustrating.

    If you think it's hard to find a good duplex, try looking for an apartment complex! While Milwaukee real estate prices are still about 40% lower than the national average, rents keep going up, demand for housing is very strong and: almost nobody is selling. But like I said, welcome to the new normal.


     But it doesn't beat a savings account anymore.... that's the point. Deals are not penciling out and there are now alternatives. TINA is dead 

    I don't see free money (Fed funds rates of less than 2%) coming again unless we have another cataclysmic event, but to just buy property that you project will go up in value with ZERO cash flow while carrying all the risks just doesn't make sense. And with the investor pullback being so large I would say the consensus would agree with me. 

  • Member since 2019 · 223 posts · 261 votes
    3y

    Real estate prices are still way up, insurance cost in my area has doubled, maintenance and materials are still very high. Rent in my area has not increased enough to cover theses. Now adding another $200-$300 a month in interest makes deals very hard to make sense. I think that will deter many new investors and existing investors like myself. I'm hoping things will even out with lower home prices and due to few investors and new home purchases rents will continue to increase.

  • Investor · Youngstown, OH · Member since 2017 · 2k+ posts · 2k+ votes
    3y
    Quote from @Jackson Risse:

    I keep on hearing from investors that "I'm waiting for interest rates to go down" or I hear "I need rates to go down for the numbers to make sense". Maybe these investors are saying this because they just got into investing in the past decade where the rates were basically zero or close to it. The past decade of interest rates on a 30 year fix mortgage has never happened before 2008. In the 70s and 80 they were 8, 9, 10, 11, 12, even 18 percent. Now do I think they will continue to reach those levels I don't know I'm not Jerome Powell or the chairman of Chase or BoA. One thing I will say if you are waiting for the interest rates to back down to 2, 3 percent, you might be waiting a long time. All I am saying, is if you are one of those investors that say "I'm waiting for interest rates to go back", you probably need a reality check and do some digging into the history of interest rates. And ask yourself, were we just really lucky in the past decade to be able to lock in a mortgage at 3%. Start to look at the 30 year fixed mortgage rates history graph.

    My owner occupant buyers are driving me nuts. They want to wait for rates to drop, but once they do, they'll complain that there's too much competition, prices are rising too quickly, they have to offer $20k over asking, they have to waive inspections, etc. You can't have it all. 

  • Russell BrazilBusiness Member
    Moderator
    Real Estate Agent · Washington, D.C. · Member since 2012 · 17k+ posts · 30k+ votes
    3y
    Quote from @Zeke Rosenblatt:

    In order for deals to pencil out, we either need to see a decrease in rates (which seems further out rather than sooner) or a decrease in asking prices. Interested to see how creative investors are going to find ways to get deals done.

    You missed the actual solution. Readjusting your expectations to what the market offers today, not what it offered yesterday.
  • Jay ThomasPro Member
    Real Estate Agent · Houston, TX · Member since 2021 · 1k+ posts · 715 votes
    3y

    With the current market conditions, it may seem difficult to get deals done. Fortunately, investors are becoming increasingly creative in finding ways to make their investments pencil out. By either lowering rates or asking prices, investors can still find success in today's market and get deals done. With rising creativity and determination, there is a lot of potential for success in this environment. It will be interesting to see how investors utilize these opportunities to create value for themselves and others.

    Investors should stay positive and use their imaginations as they search for ways to turn their investments into successes. With the right strategies, there is no limit to what can be achieved! The future looks bright for those who persistently seek out innovative solutions to today’s market conditions. Let’s see what kind of amazing deals we can make!

  • John MorganPro Member
    Rental Property Investor · Grand Prairie, TX · Member since 2018 · 2k+ posts · 2k+ votes
    3y

    These curremt interest rates make it hard to be cash flow positive for investors. When interest rates were way higher than this in the 80's, investors still cash flowed. And homes were much more affordable for people buying a primary. Today they aren't affordable so we have to adapt. I bought 5 buy n hold SFR recently because I can still cash flow with these deals and I think RE appreciation and rent will go up in the next 10-20 years. But I'm seeing investors and flippers dropping out like flies in my area now. Good for me because I'm dealing with less competition. But bad for sellers having to lower their expectations for selling their home 40% more than what it was worth just 2 years ago.

  • Investor · Member since 2021 · 29 posts · 19 votes
    3y

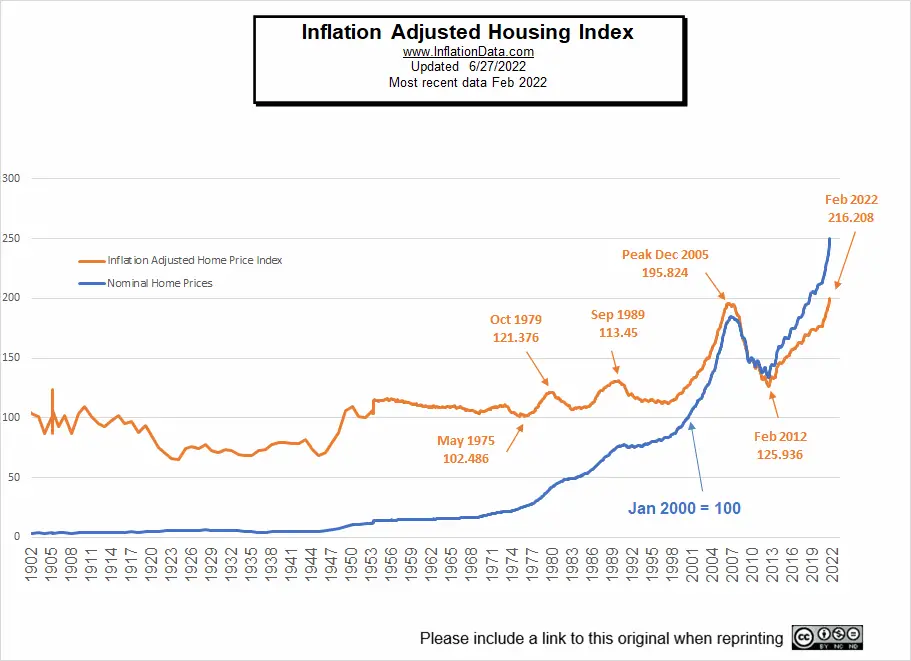
    @Jackson Risse your graph tells half the story and you did include those higher interest rates so here is the graph to compare with yours, this Fred graph shows the inverse with interest rates falling since 1980 as house prices rise. Cant have both high interest rate and high prices something gives. Yes, seems funny that 7% is high but considering house prices and wages lagging behind all other high costs there is no wonder why housing is not affordable to the average wage earner.

  • Property Manager · Leominster, MA · Member since 2022 · 103 posts · 50 votes
    3y

    @Jackson Risse. We are focusing our energy on finding deals earlier in the cycle, the closer we are to the Seller at the original point they decide to sell the more likely we are to get a better price. Our focus is on acquisition cost, its the biggest lever we have some level we can influence.

  • Dan H.Pro Member
    Investor · Poway, CA · Member since 2015 · 7k+ posts · 8k+ votes
    3y

    I am being cautous.  Interest rates at 6.5% is over double what it was a year ago.  Home prices on average have not fallen to place in the same affordability as a year ago.  I am being cautious because I expect further housing price declines.  Why would I purchase today if I expect prices to fall a further 10% without a significant increase to interest rates? Basically, I expect financed properties are at their lowest affordability maybe in history.  Prior to the recent rate increases, the affordabilty was already the worst since at least 2008 due in part to the high price increases of the last couple years (or even the last dozen years).

    Buying 10% below market has a risk that has not existed for the last dozen years (maybe an exception for the very start of Covid where I was also being very cautious).

    I am still looking, but cautious.  I purchased $4M in property (2 properties) in Dec 2021 (a year ago) when interest rates were less than half of the current rate.  I have not purchased since then, but if I found a deal that meets my cautious underwriting, I would purchase.

    Note I am not implying that the rates will necessarily fall to the rates of a year ago, but if it does not we will see property prices decline further.  Regardless if interest rates come down or property values decrease, the financed homes will be more affordable in the future than today.

    Good luck

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    3y
    Quote from @J. Mitchell Bernier:
    Quote from @Marcus Auerbach:

    Neither will have to happen @Zeke Rosenblatt! Investors will have to adjust their expectations. Rates should come down a bit, but that only means upward pressure on prices. 

    The fat days are gone, welcome to the new normal. Talk to a real estate investor in Germany. Cash flow?? - Never heard of that. Their goal is to pay off the property over 30 years, with some help from a tenant. Still beats a savings account!

    Get the best deal you can, while you still can. It does not help to say the deals don't pencil out if at the end of the year you have not met your acquisition goals and prices are up, again. I am in the same boat as everyone else as an investor and I don't like it either. It's frustrating.

    If you think it's hard to find a good duplex, try looking for an apartment complex! While Milwaukee real estate prices are still about 40% lower than the national average, rents keep going up, demand for housing is very strong and: almost nobody is selling. But like I said, welcome to the new normal.


     But it doesn't beat a savings account anymore.... that's the point. Deals are not penciling out and there are now alternatives. TINA is dead 

    I don't see free money (Fed funds rates of less than 2%) coming again unless we have another cataclysmic event, but to just buy property that you project will go up in value with ZERO cash flow while carrying all the risks just doesn't make sense. And with the investor pullback being so large I would say the consensus would agree with me. 


    What is TINA? Zero or even negative cash flow deals can make sense when you adjust your criteria, but it is not about appreciation. It is about paying down debt. For simple math you pay down a mortgage about 3% a year (less in the beginning, more later) and you are typically leveraged 4:1 or 3:1 so that is 9-12% ROI on your down payment. Eventually you will be cash flow positive and over a long enough period of time you will also see appreciation.

    The exuberance of the last years is gone: free money from real estate, traveling the world on ATM style rental properties is no longer viable. In a way we have gone from a gold rush to a more reasonable economic situation - profits are finite now, not infinite. Will that weed out "investors"? Absolutely. You need now money to be an investor.

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    3y
    Quote from @Zeke Rosenblatt:

    @Marcus Auerbach Do you expect lenders to adjust their underwriting requirements? What type of financing options would you recommend in your "Germany" style scenario? 


     Absolutely not, why would lenders do that? They may even tighten their reserve requirements to make sure you can keep a rental property afloat if you loose a few tenants. You always want the best financing you can get. If you can, 30 year fixed, for most of us who have being doing this for a while it's commercial loans anyways, 5y fixed, 25y amortization. More down payment will be key in the future.

  • Lender · Southwest Georgia · Member since 2017 · 312 posts · 278 votes
    3y
    Quote from @Marcus Auerbach:
    Quote from @J. Mitchell Bernier:
    Quote from @Marcus Auerbach:

    Neither will have to happen @Zeke Rosenblatt! Investors will have to adjust their expectations. Rates should come down a bit, but that only means upward pressure on prices. 

    The fat days are gone, welcome to the new normal. Talk to a real estate investor in Germany. Cash flow?? - Never heard of that. Their goal is to pay off the property over 30 years, with some help from a tenant. Still beats a savings account!

    Get the best deal you can, while you still can. It does not help to say the deals don't pencil out if at the end of the year you have not met your acquisition goals and prices are up, again. I am in the same boat as everyone else as an investor and I don't like it either. It's frustrating.

    If you think it's hard to find a good duplex, try looking for an apartment complex! While Milwaukee real estate prices are still about 40% lower than the national average, rents keep going up, demand for housing is very strong and: almost nobody is selling. But like I said, welcome to the new normal.


     But it doesn't beat a savings account anymore.... that's the point. Deals are not penciling out and there are now alternatives. TINA is dead 

    I don't see free money (Fed funds rates of less than 2%) coming again unless we have another cataclysmic event, but to just buy property that you project will go up in value with ZERO cash flow while carrying all the risks just doesn't make sense. And with the investor pullback being so large I would say the consensus would agree with me. 


    What is TINA? Zero or even negative cash flow deals can make sense when you adjust your criteria, but it is not about appreciation. It is about paying down debt. For simple math you pay down a mortgage about 3% a year (less in the beginning, more later) and you are typically leveraged 4:1 or 3:1 so that is 9-12% ROI on your down payment. Eventually you will be cash flow positive and over a long enough period of time you will also see appreciation.

    The exuberance of the last years is gone: free money from real estate, traveling the world on ATM style rental properties is no longer viable. In a way we have gone from a gold rush to a more reasonable economic situation - profits are finite now, not infinite. Will that weed out "investors"? Absolutely. You need now money to be an investor.


     TINA is the acronym for There Is No Alternative. 

    But in that scenario, you are taking a lot of risk for very little return and like I mentioned there are alternatives now. 

    Let's say you bought a $200K house and you put 20% down and financed over 30 years at 6%. At the end of 3 years, you would have paid your mortgage down to $153k, from $160k. So that is a $7k return against your $40K investment over 3 years. That is a whopping 5.83% annual return, with all the risks still there. Plus, you have to work for that. Right now, there are Treasuries that are yielding 4.7% and AAA corporate bonds at 5% where there is no work, and the risk is either zero or extremely low. 

    So why would anyone take all the additional risk in buying new property, because there are more risks, for Net Risk Premium of just over 1%???

    I am not advocating for selling what you have and investing all of into Bonds, but if you are expecting investors with any sense to buy new properties for that skinny of a return, God help em. 

  • Real Estate Broker · Milwaukee, WI · Member since 2016 · 121 posts · 81 votes
    3y
    Quote from @J. Mitchell Bernier:
    Quote from @Marcus Auerbach:
    Quote from @J. Mitchell Bernier:
    Quote from @Marcus Auerbach:

    Neither will have to happen @Zeke Rosenblatt! Investors will have to adjust their expectations. Rates should come down a bit, but that only means upward pressure on prices. 

    The fat days are gone, welcome to the new normal. Talk to a real estate investor in Germany. Cash flow?? - Never heard of that. Their goal is to pay off the property over 30 years, with some help from a tenant. Still beats a savings account!

    Get the best deal you can, while you still can. It does not help to say the deals don't pencil out if at the end of the year you have not met your acquisition goals and prices are up, again. I am in the same boat as everyone else as an investor and I don't like it either. It's frustrating.

    If you think it's hard to find a good duplex, try looking for an apartment complex! While Milwaukee real estate prices are still about 40% lower than the national average, rents keep going up, demand for housing is very strong and: almost nobody is selling. But like I said, welcome to the new normal.


     But it doesn't beat a savings account anymore.... that's the point. Deals are not penciling out and there are now alternatives. TINA is dead 

    I don't see free money (Fed funds rates of less than 2%) coming again unless we have another cataclysmic event, but to just buy property that you project will go up in value with ZERO cash flow while carrying all the risks just doesn't make sense. And with the investor pullback being so large I would say the consensus would agree with me. 


    What is TINA? Zero or even negative cash flow deals can make sense when you adjust your criteria, but it is not about appreciation. It is about paying down debt. For simple math you pay down a mortgage about 3% a year (less in the beginning, more later) and you are typically leveraged 4:1 or 3:1 so that is 9-12% ROI on your down payment. Eventually you will be cash flow positive and over a long enough period of time you will also see appreciation.

    The exuberance of the last years is gone: free money from real estate, traveling the world on ATM style rental properties is no longer viable. In a way we have gone from a gold rush to a more reasonable economic situation - profits are finite now, not infinite. Will that weed out "investors"? Absolutely. You need now money to be an investor.


     TINA is the acronym for There Is No Alternative. 

    But in that scenario, you are taking a lot of risk for very little return and like I mentioned there are alternatives now. 

    Let's say you bought a $200K house and you put 20% down and financed over 30 years at 6%. At the end of 3 years, you would have paid your mortgage down to $153k, from $160k. So that is a $7k return against your $40K investment over 3 years. That is a whopping 5.83% annual return, with all the risks still there. Plus, you have to work for that. Right now, there are Treasuries that are yielding 4.7% and AAA corporate bonds at 5% where there is no work, and the risk is either zero or extremely low. 

    So why would anyone take all the additional risk in buying new property, because there are more risks, for Net Risk Premium of just over 1%???

    I am not advocating for selling what you have and investing all of into Bonds, but if you are expecting investors with any sense to buy new properties for that skinny of a return, God help em. 

    Treasuries offer zero protection against currency debasement. So when you say they get 4.7% and "the risk is either zero or extremely low", sure the risk of outright default is near zero but you're guaranteed to lose purchasing power over time. If you think the United States government is going to pay you back with interest in real terms, you're delusional. After adjusting for the fact that hard assets float against inflation, Real Estate destroys US Treasuries by a mile. Additionally, good luck getting 3:1 or 4:1 leverage on US Treasuries.

  • Investor · Greenville, SC · Member since 2016 · 5k+ posts · 13k+ votes
    3y

    For the members who don't feel that rates matter, please post real deals that help illustrate how they work when the interest rate is at or above the cap rate (or yield, return on cost, unlevered return...whatever you want to call it). All we hear on the forums is about the opportunity in this market with very few real deals being discussed. It's a constant barrage of advertisements and does not help with investing. Cash buyers are having success. There was a recent post from a member on a NNN deal that was a higher cap rate asset class...purchased with only 50% leverage...using a lower rate heloc (6%)...with an interest only payment...that worked. I have a big acquisition in processes; so, I am a buyer but am also interested in how others are getting it done.

  • Severna Park, MD · Member since 2013 · 7k+ posts · 7k+ votes
    3y

    I have bought when interest rates were 12% and I have bought when they were 3% . As long as I got a deal on the property , I dont care what the rates are .  WHY ?   Because rates will do 1 of 2 things over time , they will go up , or they will go down .  If they go up to 8% and I am at 6% I will pat myself on the back . If they go down below 6% I will refinance . Either way I am in the game not sitting on the sidelines waiting . 

    As rates rise , that knocks some buyers out of the market , they have to rent . In my area apartments are renting a 1/1 for $1700 , a 2/1 for $2200 a month . A SFH 2/1 has no problem getting between $1500 and $1900 a month. You could buy a 2/1 SFH in my area 5 years ago for around $ 150K . They are now $275K if you can find one .

    I will pull the trigger on another property at current rates tomorrow , IF I can find a deal , but they are like looking for a needle in a haystack . 

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    3y
    Quote from @Brian Kragerud:

    @Jackson Risse your graph tells half the story and you did include those higher interest rates so here is the graph to compare with yours, this Fred graph shows the inverse with interest rates falling since 1980 as house prices rise. Cant have both high interest rate and high prices something gives. Yes, seems funny that 7% is high but considering house prices and wages lagging behind all other high costs there is no wonder why housing is not affordable to the average wage earner.


    One thing the chart does not consider is that todays homes are easily twice the size of 1960's houses. The number of bathrooms has basically tripled. Many had a single car garage, today a 3 car garage is standard. We require a lot more from a house today. In my market a 1960s home is in fact about half the price of a new construction.

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    3y
    Quote from @J. Mitchell Bernier:
    Quote from @Marcus Auerbach:
    Quote from @J. Mitchell Bernier:
    Quote from @Marcus Auerbach:

    Neither will have to happen @Zeke Rosenblatt! Investors will have to adjust their expectations. Rates should come down a bit, but that only means upward pressure on prices. 

    The fat days are gone, welcome to the new normal. Talk to a real estate investor in Germany. Cash flow?? - Never heard of that. Their goal is to pay off the property over 30 years, with some help from a tenant. Still beats a savings account!

    Get the best deal you can, while you still can. It does not help to say the deals don't pencil out if at the end of the year you have not met your acquisition goals and prices are up, again. I am in the same boat as everyone else as an investor and I don't like it either. It's frustrating.

    If you think it's hard to find a good duplex, try looking for an apartment complex! While Milwaukee real estate prices are still about 40% lower than the national average, rents keep going up, demand for housing is very strong and: almost nobody is selling. But like I said, welcome to the new normal.


     But it doesn't beat a savings account anymore.... that's the point. Deals are not penciling out and there are now alternatives. TINA is dead 

    I don't see free money (Fed funds rates of less than 2%) coming again unless we have another cataclysmic event, but to just buy property that you project will go up in value with ZERO cash flow while carrying all the risks just doesn't make sense. And with the investor pullback being so large I would say the consensus would agree with me. 


    What is TINA? Zero or even negative cash flow deals can make sense when you adjust your criteria, but it is not about appreciation. It is about paying down debt. For simple math you pay down a mortgage about 3% a year (less in the beginning, more later) and you are typically leveraged 4:1 or 3:1 so that is 9-12% ROI on your down payment. Eventually you will be cash flow positive and over a long enough period of time you will also see appreciation.

    The exuberance of the last years is gone: free money from real estate, traveling the world on ATM style rental properties is no longer viable. In a way we have gone from a gold rush to a more reasonable economic situation - profits are finite now, not infinite. Will that weed out "investors"? Absolutely. You need now money to be an investor.


     TINA is the acronym for There Is No Alternative. 

    But in that scenario, you are taking a lot of risk for very little return and like I mentioned there are alternatives now. 

    Let's say you bought a $200K house and you put 20% down and financed over 30 years at 6%. At the end of 3 years, you would have paid your mortgage down to $153k, from $160k. So that is a $7k return against your $40K investment over 3 years. That is a whopping 5.83% annual return, with all the risks still there. Plus, you have to work for that. Right now, there are Treasuries that are yielding 4.7% and AAA corporate bonds at 5% where there is no work, and the risk is either zero or extremely low. 

    So why would anyone take all the additional risk in buying new property, because there are more risks, for Net Risk Premium of just over 1%???

    I am not advocating for selling what you have and investing all of into Bonds, but if you are expecting investors with any sense to buy new properties for that skinny of a return, God help em. 


    Well, in this case and after only 3 years it's actually even worse, because your cost of selling is going to be 6% commission. RE is a long term investment, you have to think at least in decades.

    We have to adjust our expectations (easier for me to say, I live in the Midwest) and with that the number of new investors will drastically decline. BP has probably good numbers on that. I just observe it here on BP that after 2015 or so the number of new investor posts has exploded.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.