Lets all strive to be "Normal Rich"

Lets all strive to be "Normal Rich"

Ryan SpathBusiness Member
Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes

About eight months ago, I wrote a post here about how my goals as a real estate investor have changed.

For years, the goal was accumulation. My original target was 10 doors producing $500 per month each. Eventually we surpassed that goal, and I found myself thinking less about how much more we could acquire and more about what we were actually trying to accomplish.

That led me to set a new goal pay off our primary residence by September 27, 2028, my 45th birthday.

At the time, that felt almost counterintuitive. I'm a real estate investor. We're taught to understand and use leverage. Why would I take capital and use it to pay off relatively inexpensive debt instead of investing it?

But the more I thought about it, the more I realized I wasn't trying to maximize my net worth anymore. I was trying to maximize freedom while minimizing the number of things that could disrupt our family's life.

Recently I came across something that gave me an even clearer picture of what that could look like.

An Arizona real estate agent, Templeton Walker, has been talking on social media about what he calls "Normal Rich."

The idea is pretty simple:

Paid for primary residence.
No debt.
$2 million invested.

His example assumes that $2 million produces a 10% return, or roughly $200,000 per year. At that point, his argument is that you can live a pretty incredible "normal" life. You can own a nice home, drive a nice vehicle, take vacations, spend time with your family, and most importantly, become much more intentional about what you do with your time.

That really resonated with me.

Is $2 million plus a paid off house attainable for everyone? Probably not. But compared with so much of what we see online 100 doors, $10 million net worth, private jets, exotic cars, constantly scaling it feels like a surprisingly attainable target for someone who is willing to work hard, invest consistently, delay gratification, and give it enough time.

It has caused me to modify my own goal again.

The house payoff hasn't changed. September 27, 2028 is still the target, and based on our current earnings and savings rate, we're on track.

What has changed is how I'm thinking about the bigger finish line.

I don't necessarily want the biggest portfolio I can build. I want enough productive assets, a paid-for home, no meaningful debt, and enough income that my family and I can make decisions based primarily on how we want to spend our time rather than how much money those decisions produce.

Maybe that's $2 million. Maybe the number ends up being different for us. And because much of our wealth is in real estate, our version probably won't look exactly like someone else's.

But I really like the concept.

At some point, the goal has to change from building more to building enough.

I'm curious what everyone else thinks. Do you have an actual "enough" number, or are you still focused on accumulating as much as possible?

12Reply
1,010 views

Most Popular Reply

Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
3w

We have entered a time of unprecedented economic and social uncertainty. And while I am an optimist by nature, we have so many growing bubbles, the question is just which one get's pricked first.

Good news is real estate is not one of them despite all the complaining about affordability. AI is the obvious one, national debt another one (not only the US by the way, this is a global problem), car loans (30% have now negative equity - smells like 2008) 

Impact on RE: The problem is the difference between wealth and money. Wealth is not liquid, but for most people it's 20x or more bigger than cash. And wealth is leveraged. The danger is in the 20x factor: if something pricks the buddle (like higher interest rates) people have to liquidate assets to get access to cash to meet their debt obligations, which drives down asset prices, which prompts more liquidations - this could be something stupid like car loans. But it can tip the next domino, and the next - until it affects your tenants.

With all that stress testing your real estate portfolio is important:

- how many vacancies can you sustain?
- how long can you support it with cash reserves if you go slightly negative
- what are your options at that point
- what about compounding adverse effects, like higher vacancy + higher rates + capex

See this reply in the discussion

26 Replies

Jump to latestLatest
  • Jimmy LieuBusiness Member
    Real Estate Agent · Columbus, OH · Member since 2019 · 3k+ posts · 2k+ votes
    3w
    Quote from @Ryan Spath:

    About eight months ago, I wrote a post here about how my goals as a real estate investor have changed.

    For years, the goal was accumulation. My original target was 10 doors producing $500 per month each. Eventually we surpassed that goal, and I found myself thinking less about how much more we could acquire and more about what we were actually trying to accomplish.

    That led me to set a new goal pay off our primary residence by September 27, 2028, my 45th birthday.

    At the time, that felt almost counterintuitive. I'm a real estate investor. We're taught to understand and use leverage. Why would I take capital and use it to pay off relatively inexpensive debt instead of investing it?

    But the more I thought about it, the more I realized I wasn't trying to maximize my net worth anymore. I was trying to maximize freedom while minimizing the number of things that could disrupt our family's life.

    Recently I came across something that gave me an even clearer picture of what that could look like.

    An Arizona real estate agent, Templeton Walker, has been talking on social media about what he calls "Normal Rich."

    The idea is pretty simple:

    Paid for primary residence.
    No debt.
    $2 million invested.

    His example assumes that $2 million produces a 10% return, or roughly $200,000 per year. At that point, his argument is that you can live a pretty incredible "normal" life. You can own a nice home, drive a nice vehicle, take vacations, spend time with your family, and most importantly, become much more intentional about what you do with your time.

    That really resonated with me.

    Is $2 million plus a paid off house attainable for everyone? Probably not. But compared with so much of what we see online 100 doors, $10 million net worth, private jets, exotic cars, constantly scaling it feels like a surprisingly attainable target for someone who is willing to work hard, invest consistently, delay gratification, and give it enough time.

    It has caused me to modify my own goal again.

    The house payoff hasn't changed. September 27, 2028 is still the target, and based on our current earnings and savings rate, we're on track.

    What has changed is how I'm thinking about the bigger finish line.

    I don't necessarily want the biggest portfolio I can build. I want enough productive assets, a paid-for home, no meaningful debt, and enough income that my family and I can make decisions based primarily on how we want to spend our time rather than how much money those decisions produce.

    Maybe that's $2 million. Maybe the number ends up being different for us. And because much of our wealth is in real estate, our version probably won't look exactly like someone else's.

    But I really like the concept.

    At some point, the goal has to change from building more to building enough.

    I'm curious what everyone else thinks. Do you have an actual "enough" number, or are you still focused on accumulating as much as possible?
    Really like this perspective, Ryan. I think there’s a point where adding more doors can also mean adding more management, risk, and things competing for your time, so defining what “enough” looks like is important. My view of buy-and-hold investing has always been that the portfolio should eventually give you more choices, not just become another job you have to keep feeding. I also wouldn’t get too attached to the 10% return assumption since actual investment returns can vary quite a bit, but the bigger idea still holds. If your home is paid off, your expenses are manageable, and your investments reliably support the lifestyle you want with a healthy margin, continuing to accumulate just for the sake of a bigger number may not add much to your quality of life. I think the better “enough” number is probably based on your family’s annual spending and desired margin of safety rather than a universal net-worth target.

  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    3w

    I look at my goals slightly differently. I am not about a specific dollar figure or amount or number of doors etc. My goal is to do what I love and try to avoid as much stress as possible. The former i feel i am there, the latter - well that has its ups and downs as real estate can be stressful

    7e investments53 Reviews
    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      Fair enough. I agree it can be stressful. I guess this is why I am personally wanting a lean portfolio that covers the lifestyle.

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    3w

    We have entered a time of unprecedented economic and social uncertainty. And while I am an optimist by nature, we have so many growing bubbles, the question is just which one get's pricked first.

    Good news is real estate is not one of them despite all the complaining about affordability. AI is the obvious one, national debt another one (not only the US by the way, this is a global problem), car loans (30% have now negative equity - smells like 2008) 

    Impact on RE: The problem is the difference between wealth and money. Wealth is not liquid, but for most people it's 20x or more bigger than cash. And wealth is leveraged. The danger is in the 20x factor: if something pricks the buddle (like higher interest rates) people have to liquidate assets to get access to cash to meet their debt obligations, which drives down asset prices, which prompts more liquidations - this could be something stupid like car loans. But it can tip the next domino, and the next - until it affects your tenants.

    With all that stress testing your real estate portfolio is important:

    - how many vacancies can you sustain?
    - how long can you support it with cash reserves if you go slightly negative
    - what are your options at that point
    - what about compounding adverse effects, like higher vacancy + higher rates + capex

    • Flipper/Rehabber · CA · Member since 2023 · 1k+ posts · 1k+ votes
      3w
      Quote from @Marcus Auerbach:

      We have entered a time of unprecedented economic and social uncertainty. And while I am an optimist by nature, we have so many growing bubbles, the question is just which one get's pricked first.

      Good news is real estate is not one of them despite all the complaining about affordability. AI is the obvious one, national debt another one (not only the US by the way, this is a global problem), car loans (30% have now negative equity - smells like 2008) 

      Impact on RE: The problem is the difference between wealth and money. Wealth is not liquid, but for most people it's 20x or more bigger than cash. And wealth is leveraged. The danger is in the 20x factor: if something pricks the buddle (like higher interest rates) people have to liquidate assets to get access to cash to meet their debt obligations, which drives down asset prices, which prompts more liquidations - this could be something stupid like car loans. But it can tip the next domino, and the next - until it affects your tenants.

      With all that stress testing your real estate portfolio is important:

      - how many vacancies can you sustain?
      - how long can you support it with cash reserves if you go slightly negative
      - what are your options at that point
      - what about compounding adverse effects, like higher vacancy + higher rates + capex


       There was far more economic uncertainty in the late 70s early 80's, we've arrived at the weak men part. Americans have far higher standard of living than ever before. A nation of consumers clamoring for cheap, easy & fast. A nation of people on a1c's & ssri's lol

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      Thanks for shaing your perspective.

      The stress tests you mention are what I am in the process of actively figuring out. This is currently a moving target as I am an active realtor, have business interests, so the RE income is a bonus. I am in a KW Wealth group and one thing that I have been challenged to do is hold more dry powder. So this is something I am currently working on, I also agree about the leverage. This is also on my mind somewhat. I know a couple folks in my area that are older 60's and have 8-15 properties paid for and are happier than a pig in mud lol.

      Appreciate you taking the time to respond and your insight.

    • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
      3w
      Quote from @Alan F.:
      Quote from @Marcus Auerbach:

      We have entered a time of unprecedented economic and social uncertainty. And while I am an optimist by nature, we have so many growing bubbles, the question is just which one get's pricked first.

      Good news is real estate is not one of them despite all the complaining about affordability. AI is the obvious one, national debt another one (not only the US by the way, this is a global problem), car loans (30% have now negative equity - smells like 2008) 

      Impact on RE: The problem is the difference between wealth and money. Wealth is not liquid, but for most people it's 20x or more bigger than cash. And wealth is leveraged. The danger is in the 20x factor: if something pricks the buddle (like higher interest rates) people have to liquidate assets to get access to cash to meet their debt obligations, which drives down asset prices, which prompts more liquidations - this could be something stupid like car loans. But it can tip the next domino, and the next - until it affects your tenants.

      With all that stress testing your real estate portfolio is important:

      - how many vacancies can you sustain?
      - how long can you support it with cash reserves if you go slightly negative
      - what are your options at that point
      - what about compounding adverse effects, like higher vacancy + higher rates + capex


       There was far more economic uncertainty in the late 70s early 80's, we've arrived at the weak men part. Americans have far higher standard of living than ever before. A nation of consumers clamoring for cheap, easy & fast. A nation of people on a1c's & ssri's lol

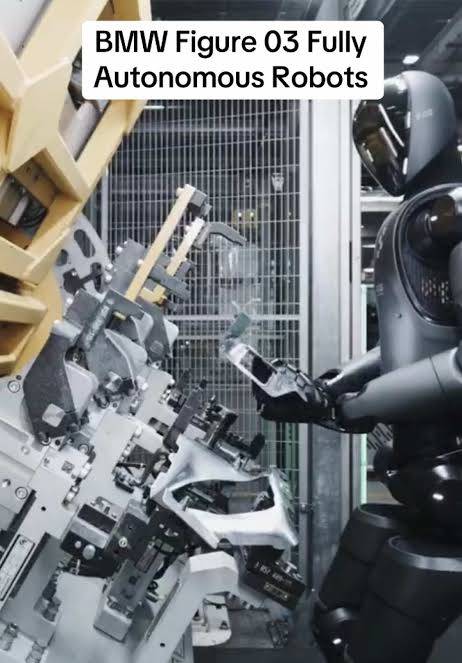
      Easy times make soft man, yes. Inflation was high, Paul Volcker had to cut deep to fix that. But what he did not have to contend with was labor replacement by AI. Looks like we are getting away with a black eye in 2026 for the entry level white collar job market. Still hurts, but the economy lives. Just like the internet, we are in wave one and expectations are overhyped, but not wrong: they just arrive 5 years later. And at that time we will have to also contend with massive manual labor replacement. 

      Actual picture from BMW's plant in Spartanburg, SC - they have 350 Figure 3 models runnig test assembly.

  • Joe PryorBusiness Member
    Real Estate Broker · Oklahoma City · Member since 2026 · 9 posts · 8 votes
    3w

    I completely agree and the fact you are doing that at your age is special. We paid off two 3.5% 15 year loans when I turned 75. I argued to my wife that you do not pay off low rates and you use the leverage. She argued that besides high net worth and good health, what about psychology? That is our third important goal which has been about international travel. I realized how important it was for her and we paid them off. Imagine my surprise as to how this affected me positively. So we had two rights but as a couple we agreed to help each other. By helping her I also helped myself. Congratulations on your success.

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      Thanks for your input. I have been in new rooms with new people and it is changing the way I am thinking about wealth. I appreciate you sharing your personal experience.

  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    3w

    OP. Believe I may have responded to this same type of post by you before. @Marcus Auerbach noted the multiple many dominoes that will fall and just a question of when. Normal Stress tests won't cover these. I expect 15% inflation/interest rates in the next 5 years. I have been wrong the last 5 years.

    1- never pay your house off. Lowest interest rate, longest term, lowest downpayment, can't take during a bankruptcy. My wife wanted to pay it off, so we paid it off. Luckily, it is not that large of a component of our overall wealth.

    2- We have approached wealth in 3 waves:

    A. Near term- cash equivalents. We chose 5 years living plan. We don't worry about the Stock market or other actions in the world. We gain liquidity, but lose returns, but that is a known loss. This is also cushion should we want to jump back in and take advantage of any market or property shortcomings.

    B. Midterm- say 5 to 20 years. Real Estate fills that niche for us. Self-Storage, Country Subdivision lots, Cash flow and Equity buildup.

    C. Long Term- Stock markets, Teak Plantation. Low maintenance since we are not trying to hit home runs. High risk at the moment, but not from a historical standpoint. We don't plan to ever use this money, so it has to grow and outperform inflation, Insurance and Property taxes.

    3- Realize your math can fluctuate. But Income Taxes, Property taxes, Insurance, Inflation need to impact your figures more.

    4- Age- your 45. Kids, College, Weddings, life, health insurance, etc. Your living expenses will be higher than a 65 and up.

    5- Risk Management

    A. Product prune properties and assets.

    B. Debt to me will be our greatest asset and "highest return". Trying for as much long-term debt as possible, versus 5-year commercial balloon terms. Have SBA 20-year term at 3.5% and now doing an addition hopefully with SBA 20-year terms at 6.5%. Participating bank is 10 years then 5/5 balloons. Fixe rates. Once we get this addition done. Will go back to our other commercial debt and see what else I can move over to SBA loans. My thesis is both normal Inflation, and the FED/Treasury/Government will push overall inflation to over 20% for the next 20 years. Debt will be free. Again, my crystal ball has been wrong for the last 5 years. Luckily, I'm a Baby Boomer. SS, Medicare/Medicare are in full bloom. This is part of the $140T unfunded debt, and not part of the $40T debt. So, forget the Crystal Ball, don't need it.

    C. Real estate stress test. Since your viewing $2mm, let's say in RE assets with no debt. Hopefully say $300,000 of that is Cash Equivalents. Stress test both your Revenue side. For your type of asset can you push rental rates to keep up with inflation at 5/10/15/20%???? Expense side- Insurance/Property Taxes- 5/10/15/20% annual growth rates? Capex on your type of assets- specific replacements- roof/HVAC/interior/driveways/sidewalks/etc. Our 2,100 sqft all brick house with full basement cost $135,000 in 1992. Just replaced the walk out porch 15 x 20 cedar with stairs for $45,000. Nothing special. What is your Capex breakpoint? Where is your break point for your type of assets? Will your RE asset grow in value and keep up with inflation? What will those neighborhoods look like in 20 years?

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      Thanks for the reply, I espically like this : C. Real estate stress test. Since your viewing $2mm, let's say in RE assets with no debt. Hopefully say $300,000 of that is Cash Equivalents. Stress test both your Revenue side. For your type of asset can you push rental rates to keep up with inflation at 5/10/15/20%???? Expense side- Insurance/Property Taxes- 5/10/15/20% annual growth rates? Capex on your type of assets- specific replacements- roof/HVAC/interior/driveways/sidewalks/etc. Our 2,100 sqft all brick house with full basement cost $135,000 in 1992. Just replaced the walk out porch 15 x 20 cedar with stairs for $45,000. Nothing special. What is your Capex breakpoint? Where is your break point for your type of assets? Will your RE asset grow in value and keep up with inflation? What will those neighborhoods look like in 20 years?...I definetly have some homework to do!

  • Shiloh LundahlPro Member
    Rental Property Investor · Gilbert, AZ · Member since 2016 · 3k+ posts · 4k+ votes
    3w

    @Ryan Spath I'm going to go all religious on you. I hope that's OK and I hope you're not offended. I think it would be great to get to a point where I have been successful enough in life to where I'm able to take care of my needs and my family's needs and then just be content. But it makes me think of the parable of the talents. 

    The master gave a man 1 talent (which will be money in this case), and another man 2 talents, and the last man 5 talents. Then many years pass, and the master comes to see what they've done with their talents. The man who received 5 talents was able to double it and he now had 10 talents, and the master said that he was a good and faithful servant. The man who received 2 talents also double it and the master said the same thing to him. The man who received only 1 talent hid it away because he was afraid that he would lose it, and that the master would be mad. When the master found this out the master said to him that he was a slothful and unwise servant. 

    The way I interpret this parable is as follows. if I'm given two talents, or five talents, or one talent, it doesn't matter. What matters is that I double what I'm given. Or in other words, I'm a good steward over that which I am given, and that I multiply it to the best of my ability. let's say I was given five talents, and I can take care of my family comfortably with only seven talents, I wouldn't really need to put forth more effort to earn the additional three talents because I'm well taken care of. But I fear that I would be a slothful and unwise servant. If I've been given a talent or ability to create wealth, and I don't maximize that ability than I feel that I am not living up to the potential that I've been blessed with and that I am not being a wise steward. 

    There are things that may become required of me at some moment in time that may require a lot of money. I don't know what these things are, but I don't want to get to that moment and not have the money that I may need, that I could've had if I had been maximizing my talents. So I get conceptually the allure of taking care of oneself and one's family, but I feel what may be required of me at some future time may go beyond that. And that is what pushes me beyond the goal of taking care of myself and my family. 

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      @Shiloh Lundahl Its interesting you wrote this the day you did, Im reading a book its "The King is coming" by John Bevere. I read a chapter going along these lines "A man going on a journey, who called his servants and entrusted to them his property. To one he gave five talents, to another two, to another one, to each according to his ability." This same day I went to the treasure valley men's conference. The first speaker was talking about retirement and how this is not biblical. What you have written, what I read that day, and what I heard/learned at the men's conference really spoke to me. Im going to pray on all this.....

  • Rental Property Investor · Joliet, IL · Member since 2013 · 98 posts · 47 votes
    3w

    This sounds very similar to my own journey, both in real estate and in how I think about wealth today.

    For a long time, I was focused on building the portfolio. At some point, the question changed from “How much more can I accumulate?” to “How much is enough to create the income, flexibility, and security I actually want?”

    Where I struggle a little with the “Normal Rich” example is the $2 million invested producing $200,000 per year.

    A 10% long-term return may be achievable with a moderately aggressive portfolio, but I would not want to plan my lifestyle around spending the full 10%. Markets do not deliver returns evenly. One event like 2001–2002 or 2008 can reduce a portfolio by 25% or more at exactly the wrong time.

    For me, “Normal Rich” would probably require either a larger investment balance, a lower planned withdrawal rate, or other dependable sources of cash flow.

    That is one reason real estate still fits into my version of the equation. I am increasingly less interested in maximizing the number of properties I own and more interested in converting the equity I already have into durable income with limited debt and plenty of flexibility.

    I really like the underlying idea, though.

    At some point, more stops being the objective. Enough becomes the objective.

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      Appreciate your insight. I know the 10% returns are high, as mentioned I just used this as an example from someone else's view point.

  • Real Estate Broker · AZ · Member since 2026 · 3 posts · 0 votes
    3w

    🏆This is LIFE💪😁🦋

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    3w

    @Ryan Spath all paid off is overrated. I know a number of LL in their 60s still working on that and living frugal, despite 10+ million net worth. Inflation is a reason to HAVE debt, and we are totally going to have more inflation (oil prices + energy cost + national debt + bond market + AI automation: everything points to inflation) 

    But paying properties off from cashflow is nuts: that's like using a spoon instead of a shovel. If you want to do that, better to fold in half, sell half and pay off the other half. Or just maintain a (lower) LTV and harvest equity every year.

    Especially in light of the inflation @Henry Clarkis expecting: double digit inflation feels a little dramatic to expect, but when you look at the macro economics and read Ray Dalio as far as where the US empire is on it's life cycle - hard to rule out. And in that case fixed rate debt is working massively in your favor. I think there is also some value in concentrating debt in a part of your portfolio and having the other part free and clear: in makes it a lot easier to borrow in an emergency situation than against a property that already has a loan on it, even if it is only 20% LTV.

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      Thanks for your insight. Good point on the inflation is the reason we have debt, I agree witht his 100%. I need to clarify what no debt means, consumer debt, cars, boats, and the like. My current goal is to pay off my primary. I still have debt on the rentals. The idea behind this is to take some chips off the table. I have been very risk seeking in my 42 years of life when it comes to finances, always doubling down in business, levering up in RE. Now, married with two children, my mindset has begin to shift. I still plan on actively working, and who know if I need to buy more RE due to tax implications I may, Just want to consider taking a few chips off the board thats all.

  • Flipper/Rehabber · CA · Member since 2023 · 1k+ posts · 1k+ votes
    3w

    The national debt is indeed very concerning, but Dalio (aka perma-bear) is a bit dramatic.

    Fed chairmans Burns & Miller where both post war Keynesians & contributed to the inflation of 70's, Volcker should've just torn of the band aid. Throttling long term inflation drags it out, like J-pow was doing. Its encouraging that Warsh is capitulating.

    AI is definitely effecting entry level desk jobs, but that's mostly menial work.

    Med tech robotics is hiring alot, here. Ive been around automation for a long time now & the bark is generally worse than the bite. Capitol equipment sales guys are pretty happy lol

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      I was having this conversation with a college friend this past weekend, It will be interesting to see how the AI job loss / more efficient economy goes...

  • Joe PryorBusiness Member
    Real Estate Broker · Oklahoma City · Member since 2026 · 9 posts · 8 votes
    3w

    I disagree a bit on paying it off. We do have high net worth and we owe nothing. Our passive income is strong so we are at a different point of life as I am 78 but still working real estate investors. I will say this to younger investors. If you get on the right side of inflation you win. Think about holding a property for 10 years. You are borrowing expensive dollars and since the dollar may be worth 74 cents after ten years of inflation you are paying back in cheaper dollars. The lender can't change your terms so buying a $250,000 property and using leverage is a key to long term success and not sitting on money that is losing value. Remember on long term holds you need multiple properties to offset vacancy when you have it. I normally think 5 or more puts you in a good position still having positive cash flow.

  • Real Estate Consultant · Melbourne, FL · Member since 2019 · 185 posts · 106 votes
    3w

    I built a business past $1M a year and still had days it owned every minute of me. That changed the score pretty fast. Paid off house, enough invested and control of your time sounds a lot richer than another 50 doors you don't need.

    • Ryan SpathBusiness Member
      OP
      Real Estate Agent · Boise, ID · Member since 2017 · 553 posts · 370 votes
      3w

      Amen to this, it changes perspective for me when we think about what really matters. thanks for sharing

  • Rental Property Investor · Cleves · Member since 2023 · 132 posts · 82 votes
    2w

    hi, i’ll be good with $30 million in equity, $25K per month.

  • Garrett KeithPro Member
    New to Real Estate · Dubuque, Dubuque Iowa · Member since 2026 · 32 posts · 18 votes
    2w

    Hi Ryan,

    We've actually talked about something similar to this before. I completely agree. Money isn't the end goal, or it shouldn't be. It's what it can do for us. It's a resource, and it's meant to serve us, not the other way around.

    I don't have an exact number in mind. But I know what I want my day to day life to look like, and for now that's enough to keep me moving in that direction.

    1 Timothy 6 says "the love of money is a root of all kinds of evils." That passage is dealing with false teachers and true contentment. It also says we brought nothing into this world and can't take anything out of it, and "if we have food and clothing, with these we will be content." It's not the amount of units you have, the massive amount of equity you have built up, or the large cash flow you have coming in each month. All that to say, money isn't the purpose of man. The purpose of man is to glorify God and enjoy Him forever. God can be greatly glorified in how we invest and use real estate, and in how we use our time and money.

    Time is a resource you can't buy. If your portfolio can provide for you and your family while also freeing up your time, you're already rich, whether the number is $2 million or something else entirely.

    And to everyone in the comments saying this isn't the most efficient way to invest, they're missing the point. This was never about making the most money. It's about making the most of your money. Reread Ryan's post.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.