Housing crash deniers ???
Most Popular Reply
Greg ScottPro Member
Rental Property Investor · SE Michigan · Member since 2014 · 4k+ posts · 6k+ votesThe market may correct, but I firmly believe there won't be a crash. The reason is simple, equity.
Before 2008 people with no income could get liars loans and buy much more real estate than they could afford. We heard stories of cleaning ladies buying multiple million dollar homes. When home prices starting falling, the whole thing collapses like a house of cards because nobody had any equity. They couldn't sell and get out. We had cascading foreclosures creating a downward spiral.
Recently, prices have been surging. Given the laws passed after the Great Recession, appraisals and lending is highly restricted. Appraisals have not been keeping up with prices and lenders won't lend above appraised value. We sold a house in 2021 and in one day had 20 offers. Several of them had acceleration clauses stating they would pay more than anyone else up to $X. Both of them waived any financing contingency because they KNEW the house wouldn't appraise for what they were offering. They had to make up the difference with cash. Those people have a ton of equity in their homes. If they had to sell, they might take a haircut, but they aren't going to get foreclosed.
There is no house of cards here to come tumbling down.
2904 Replies
- Member since 2022 · 485 posts · 216 votes3y
Quote from @Bruce Woodruff:
Quote from @Michael Wooldridge:
Also Florida gets about 25,000 people a year from California, expected to increase. The sun 'n fun, ocean and outdoor lifestyle make it an easy transition for those looking to go from Blue to Red. That's a quarter of a million people every decade.....it will have a definite impact on the housing market and prices...
Eventually sure. but it’s a drop in the bucket today. once median home prices go above the median national number sort of like those big west coast towns that got massive transplants. We might have an issue.
Anyway Like I said in the original post I’ve predicted West Coast vs East Coast. Jobs resiliency which we are seeing and stagnation not massive deflation in the market. So far my forecast seems to be more on track.
- 3yDan H.Pro MemberInvestor · Poway, CA · Member since 2015 · 7k+ posts · 8k+ votes
Quote from @Carlos Ptriawan:
Dan, please correct me if I'm wrong. I guess the biggest employer in San Diego is the US Naval base, right?
Do you know how they could afford to live in San Diego with such high costs/rent ? Is there gov. subsidy/housing for them?I suspect you are correct on the navy being the biggest employer (but not certain).
Even though I worked on the navy base for 6 years, I am far from an expert on military compensation. I am sure any navy/ex-navy would have better knowledge in this area.
This is what I believe to be true. There is military supplied housing (often on base, but not always) and housing not supplied by the military. If you choose housing not supplied by the military you get a housing allowance. The housing allowance varies by location so high housing cost markets like San Diego have a higher housing allowance than low cost areas like Dayton (but Dayton is Air Force and not navy, but it still works as an example).
If I have anything incorrect, I take no offense at having anyone correct the info.
- Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @Michael Wooldridge:
Quote from @Bruce Woodruff:
Quote from @Michael Wooldridge:
Also Florida gets about 25,000 people a year from California, expected to increase. The sun 'n fun, ocean and outdoor lifestyle make it an easy transition for those looking to go from Blue to Red. That's a quarter of a million people every decade.....it will have a definite impact on the housing market and prices...
Eventually sure. but it’s a drop in the bucket today. once median home prices go above the median national number sort of like those big west coast towns that got massive transplants. We might have an issue.
Anyway Like I said in the original post I’ve predicted West Coast vs East Coast. Jobs resiliency which we are seeing and stagnation not massive deflation in the market. So far my forecast seems to be more on track.
Florida is not going to crash for another decade becoz home price is $406k , Miami is $562k ; it's still healthy. Middle class income is 55-60k.
Also September Zillow HI is out. Even San Jose market is already stabilizing.
Diff between July-August is -45k
Diff between August-Sep is -2k
It's already stabilizing even in the worst market, market only drops $100k. - Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Had a very busy day. what happened today with the Fed? Still getting caught up.
Fed did a mini pivot today by injecting liquidity. The bond is stabilizing. ECB going to tighten on other ends next week.
The balance sheet of the Fed at this moment is similar to Q3 2020. - Realtor · Gatlinburg · Member since 2020 · 1k+ posts · 957 votes3y
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Had a very busy day. what happened today with the Fed? Still getting caught up.
Fed did a mini pivot today by injecting liquidity. The bond is stabilizing. ECB going to tighten on other ends next week.
The balance sheet of the Fed at this moment is similar to Q3 2020.Do you have link to the liquidity injection?
- Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @John Carbone:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Do you have link to the liquidity injection?
try google reverse repo
- Realtor · Gatlinburg · Member since 2020 · 1k+ posts · 957 votes3yI don’t see anything today?
Quote from @Carlos Ptriawan:
Quote from @John Carbone:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Do you have link to the liquidity injection?
try google reverse repo
- Member since 2022 · 485 posts · 216 votes3y
Quote from @Carlos Ptriawan:
Also September Zillow HI is out. Even San Jose market is already stabilizing.
Diff between July-August is -45k
Diff between August-Sep is -2k
It's already stabilizing even in the worst market, market only drops $100k.That certainly matches with my way of thinking on Florida.
Glad to see cali stabilize a bit. I still think depending on fed reactions next 3 months we could still see some more dips and adjustments out West but my general feeling is as long as inflation continues it’s current trend. We will get into more of a flatline in the beginning of the year, nationally, with some slight raises sometime in the 2nd half as rates and announcement of rate changes come out. time will tell.
As to the fed change today, @Carlos Ptriawan, I’m with @John Carbone, I don’t see any changes today - at least in the US.
- Realtor · Gatlinburg · Member since 2020 · 1k+ posts · 957 votes3y
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Also September Zillow HI is out. Even San Jose market is already stabilizing.
Diff between July-August is -45k
Diff between August-Sep is -2k
It's already stabilizing even in the worst market, market only drops $100k.That certainly matches with my way of thinking on Florida.
Glad to see cali stabilize a bit. I still think depending on fed reactions next 3 months we could still see some more dips and adjustments out West but my general feeling is as long as inflation continues it’s current trend. We will get into more of a flatline in the beginning of the year, nationally, with some slight raises sometime in the 2nd half as rates and announcement of rate changes come out. time will tell.
As to the fed change today, @Carlos Ptriawan, I’m with @John Carbone, I don’t see any changes today - at least in the US.
I would have expected 10 year treasury to collapse below 4 if the fed did a mini pivot today. Still holding on to 4 handle.
- Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
As to the fed change today, @Carlos Ptriawan, I’m with @John Carbone, I don’t see any changes today - at least in the US.
It's not in the form of rate changes but stabilization of liquidity, that's the first step to avoid any crashes/collapses. But nonetheless, it's equal to a minuscule QE. Between four-five weeks from today, the trend changes will be more obvious.
- Realtor · Gatlinburg · Member since 2020 · 1k+ posts · 957 votes3y
@James Hamling seems like my call is coming right on que here. Seasonal adjustments claims are proving to be a myth. Short term 12-18 month 20-30 percent drops and then prices skyrocket higher like you claim, you are just a year to two too early .
US Homebuilder Confidence Collapses In October, Future Sales Hope Hits Decade-LowsIt appears delusion and hope can only last so long - even when one's salary depends on it - as US homebuilder confidence crashed to COVID lockdown lows in October after refusing to see what everyone else was seeing more months.. and what homebuyers were clearly feeling as prices soared along with mortgage rates and devastated affordability for most Americans. Against expectations of a small drop from 46 in September to 43 in October, the headline confidence index crashed to 38 - its lowest since the nadir of COVID-lockdown panic (that was worse than the weakest forecast of all economists surveyed)...
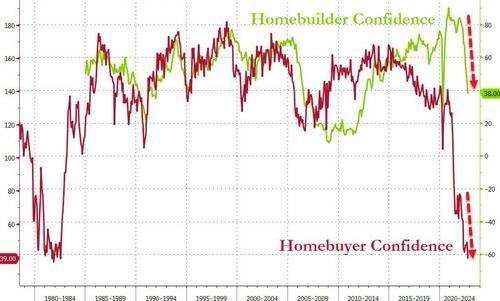
Source: Bloomberg
This the 10th straight monthly decline in homebuilder confidence - the longest losing streak since data began in 1985.
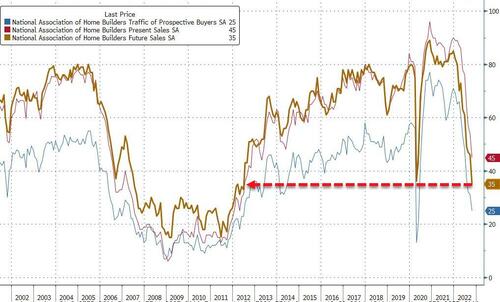
Under the hood, the report’s measure of future sales slid 11 points to 35, the lowest since 2012, while indexes of current sales and prospective buyer traffic weakened to the softest levels since May 2020.

- Member since 2019 · 7k+ posts · 4k+ votes3yThis is for you , CA Realtors think 2023 Price would be slightly below median price of 2021 (in Zillow it already happened), good to read btw.
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
2023 CALIFORNIA HOUSING FORECAST
2016
2017
2018
2019
2020
2021
2022p
2023f
SFH Resales
(000s)
417.7
424.9
402.6
398
411.9
444.5
359.2
333.4
% Change
2.0%
1.7%
-5.2%
-1.2%
3.5%
7.9%
-19.2%
-7.2%
Median Price
($000s)
$502.3
$537.9
$569.5
$592.4
$659.4
$786.7
$831.5
$758.6
% Change
5.4%
7.1%
5.9%
4.0%
11.3%
19.3%
5.7%
-8.8%
Housing
Affordability
Index*
31%
29%
28%
31%
32%
26%
19%
18%
30-Yr FRM
3.6%
4.0%
4.5%
3.9%
3.1%
3.0%
5.2%
6.6%
- Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @John Carbone:
@James Hamling seems like my call is coming right on que here. Seasonal adjustments claims are proving to be a myth. Short term 12-18 month 20-30 percent drops and then prices skyrocket higher like you claim, you are just a year to two too early .
US Homebuilder Confidence Collapses In October, Future Sales Hope Hits Decade-Lows
What's funny is how come their confidence is all time low but their gross profit margin is highest at record LOL
- Realtor · Gatlinburg · Member since 2020 · 1k+ posts · 957 votes3y
Quote from @Carlos Ptriawan:
Quote from @John Carbone:
@James Hamling seems like my call is coming right on que here. Seasonal adjustments claims are proving to be a myth. Short term 12-18 month 20-30 percent drops and then prices skyrocket higher like you claim, you are just a year to two too early .
US Homebuilder Confidence Collapses In October, Future Sales Hope Hits Decade-Lows
What's funny is how come their confidence is all time low but their gross profit margin is highest at record LOL
I think because forward looking they know what’s coming. record gross profit from all the cheap money until now with locked in debt rates that will be going up with the debt rolling off at higher rates. Recent construction sold over summer I know builders 100 percent profit. Not so much now.
- Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @John Carbone:
Quote from @Carlos Ptriawan:
Quote from @John Carbone:
@James Hamling seems like my call is coming right on que here. Seasonal adjustments claims are proving to be a myth. Short term 12-18 month 20-30 percent drops and then prices skyrocket higher like you claim, you are just a year to two too early .
US Homebuilder Confidence Collapses In October, Future Sales Hope Hits Decade-Lows
What's funny is how come their confidence is all time low but their gross profit margin is highest at record LOL
I think because forward looking they know what’s coming. record gross profit from all the cheap money until now with locked in debt rates that will be going up with the debt rolling off at higher rates. Recent construction sold over summer I know builders 100 percent profit. Not so much now.
I'm mildly neutral for next year as the mortgage rate is going back to 6.5% next year and these homebuilders are selling $300k-$500k home price only.
- Member since 2022 · 485 posts · 216 votes3y
Quote from @John Carbone:
Quote from @Carlos Ptriawan:
Quote from @John Carbone:
@James Hamling seems like my call is coming right on que here. Seasonal adjustments claims are proving to be a myth. Short term 12-18 month 20-30 percent drops and then prices skyrocket higher like you claim, you are just a year to two too early .
US Homebuilder Confidence Collapses In October, Future Sales Hope Hits Decade-Lows
What's funny is how come their confidence is all time low but their gross profit margin is highest at record LOL
I think because forward looking they know what’s coming. record gross profit from all the cheap money until now with locked in debt rates that will be going up with the debt rolling off at higher rates. Recent construction sold over summer I know builders 100 percent profit. Not so much now.
If I was a home builder I’d be negative too because the whole market is going to stagnate. The major difference is though that some think houses will go cheaper vs many of us think sales will ust be down as people wait out the 1 year shift.
Time will tell who is right. But not really a surprise on builders. Next year is going to be a slow year for them
- 3yGreg R.Investor · Dallas, TX · Member since 2016 · 887 posts · 1k+ votesOPOk, I get this, but what kind of impact do think this will have on rates? Seems like rates are likely not going to go up to 8-10%, but certainly not down to the 3's or 4's. From talking to some of my lender contacts they seem to think rates will stabilize somewhere in the 5-6's.
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Had a very busy day. what happened today with the Fed? Still getting caught up.
Fed did a mini pivot today by injecting liquidity. The bond is stabilizing. ECB going to tighten on other ends next week.
The balance sheet of the Fed at this moment is similar to Q3 2020. - 3yGreg R.Investor · Dallas, TX · Member since 2016 · 887 posts · 1k+ votesOPI know we've covered this many times already, just want to clarify your definition of correction and crash. A correction will take prices back to pre-bubble values, and a crash would take values below pre-bubble values?
Quote from @Carlos Ptriawan:
This is for you , CA Realtors think 2023 Price would be slightly below median price of 2021 (in Zillow it already happened), good to read btw.Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
2023 CALIFORNIA HOUSING FORECAST
2016
2017
2018
2019
2020
2021
2022p
2023f
SFH Resales
(000s)
417.7
424.9
402.6
398
411.9
444.5
359.2
333.4
% Change
2.0%
1.7%
-5.2%
-1.2%
3.5%
7.9%
-19.2%
-7.2%
Median Price
($000s)
$502.3
$537.9
$569.5
$592.4
$659.4
$786.7
$831.5
$758.6
% Change
5.4%
7.1%
5.9%
4.0%
11.3%
19.3%
5.7%
-8.8%
Housing
Affordability
Index*
31%
29%
28%
31%
32%
26%
19%
18%
30-Yr FRM
3.6%
4.0%
4.5%
3.9%
3.1%
3.0%
5.2%
6.6%
- Member since 2019 · 1 post · 1 vote3y
price are already down almost 25% in my sought after South Bay suburban zip. With the MBS market on fire premiums to the 10 yr will broaden beyond what anyone here has experienced. Purchase mortgages are going to 9% if not higher. new mortgage payments for same loan are double from the 2% days. I see 40% valuation compression from Q421 peak. Fed is hell-bent on bringing down shelter cost given it's 40% of PCE
- Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @Greg R.:
Ok, I get this, but what kind of impact do think this will have on rates? Seems like rates are likely not going to go up to 8-10%, but certainly not down to the 3's or 4's. From talking to some of my lender contacts they seem to think rates will stabilize somewhere in the 5-6's.Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Had a very busy day. what happened today with the Fed? Still getting caught up.
Fed did a mini pivot today by injecting liquidity. The bond is stabilizing. ECB going to tighten on other ends next week.
The balance sheet of the Fed at this moment is similar to Q3 2020.Rates would be high 5 to mid 6 between 2023-2024.
We will no longer see 3% rates anymore. I think high 5 we could have good balanced market. - Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @Greg R.:
I know we've covered this many times already, just want to clarify your definition of correction and crash. A correction will take prices back to pre-bubble values, and a crash would take values below pre-bubble values?Quote from @Carlos Ptriawan:
This is for you , CA Realtors think 2023 Price would be slightly below median price of 2021 (in Zillow it already happened), good to read btw.Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
2023 CALIFORNIA HOUSING FORECAST
2016
2017
2018
2019
2020
2021
2022p
2023f
SFH Resales
(000s)
417.7
424.9
402.6
398
411.9
444.5
359.2
333.4
% Change
2.0%
1.7%
-5.2%
-1.2%
3.5%
7.9%
-19.2%
-7.2%
Median Price
($000s)
$502.3
$537.9
$569.5
$592.4
$659.4
$786.7
$831.5
$758.6
% Change
5.4%
7.1%
5.9%
4.0%
11.3%
19.3%
5.7%
-8.8%
Housing
Affordability
Index*
31%
29%
28%
31%
32%
26%
19%
18%
30-Yr FRM
3.6%
4.0%
4.5%
3.9%
3.1%
3.0%
5.2%
6.6%
Nope, watch this table, basically in 2020 and 2021 and 2022 we have Two Sigma deviation moving up, In 2022-2023 we have negative 1 Sigma deviation, as result If we smoothed the price line to the old classic 2*Inflation of 6% appreciation per yeara, in 2023 we see the same home price
as predicted by CA realtors. There's no crash it's just reversion to the mean complexity.2018 2019 2020 2021 2022 2023 Median Price
($000s)$502.30 $537.90 $569.50 $592.40 $659.40 $786.70 $831.50 $758.60 % Change 5.40% 7.10% 5.90% 4.00% 11.30% 19.30% 5.70% -8.80% If 6% appreciation $627.94 $665.62 $705.56 $747.89 - 3yGreg R.Investor · Dallas, TX · Member since 2016 · 887 posts · 1k+ votesOPGot it, I agree. Seems like consensus is that 5.5-6.5 is the likely range, so seems reasonable to think rates will stabilize at 6%. With that, most of the market behavior that we're seeing now is based on Sep data - which are rates that were locked in July-August. We're not going to see the full impacts on 6-7% rates until December-ish.
Quote from @Carlos Ptriawan:
Quote from @Greg R.:
Ok, I get this, but what kind of impact do think this will have on rates? Seems like rates are likely not going to go up to 8-10%, but certainly not down to the 3's or 4's. From talking to some of my lender contacts they seem to think rates will stabilize somewhere in the 5-6's.Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Quote from @Michael Wooldridge:
Quote from @Carlos Ptriawan:
Had a very busy day. what happened today with the Fed? Still getting caught up.
Fed did a mini pivot today by injecting liquidity. The bond is stabilizing. ECB going to tighten on other ends next week.
The balance sheet of the Fed at this moment is similar to Q3 2020.Rates would be high 5 to mid 6 between 2023-2024.
We will no longer see 3% rates anymore. I think high 5 we could have good balanced market.
I'm just net getting where the optimism is coming from. We're seeing pretty significant shifts in the market already, and this is only with data from Sep - which has rates that were locked quite a bit prior. - Member since 2019 · 7k+ posts · 4k+ votes3y
Quote from @Greg R.:
I'm just net getting where the optimism is coming from. We're seeing pretty significant shifts in the market already, and this is only with data from Sep - which has rates that were locked quite a bit prior.From Zillow as it's very accurate and having real-time updates.
Two aspects :- home active inventory is almost zero growth MoM now with negative listing remaining negative MoM
- in Zillow most home sold in Sep has price in upper 5% , in July August it was noticeable -10 - 15% ranges
In the worst market (San Jose) we see stabilizing price between August-September data, for crash to happen August-Sep should reduce more than prev. mnth, it didn't happen. Crazy, the market is front-running Fed actions LOL. - 3yGreg R.Investor · Dallas, TX · Member since 2016 · 887 posts · 1k+ votesOP
Quote from @Carlos Ptriawan:
Quote from @Greg R.:
I'm just net getting where the optimism is coming from. We're seeing pretty significant shifts in the market already, and this is only with data from Sep - which has rates that were locked quite a bit prior.From Zillow as it's very accurate and having real-time updates.
Two aspects :- home active inventory is almost zero growth MoM now with negative listing remaining negative MoM
- in Zillow most home sold in Sep has price in upper 5% , in July August it was noticeable -10 - 15% ranges
In the worst market (San Jose) we see stabilizing price between August-September data, for crash to happen August-Sep should reduce more than prev. mnth, it didn't happen. Crazy, the market is front-running Fed actions LOL.Couple thoughts on this...
I know inventory had no growth, but demand has also tanked. I need to get updated stats, but even with the lack of new listings last time I checked (in DFW), the months supply of inventory increased. Therefore the low level of new listings was greater than the amount of sales, creating a net-positive impact on inventory.
I don't think it's been enough time to evaluate value decrease. How could have values stabilized in Aug-Sep when a lot of home are lingering and seeing big price decreases. I'm seeing a lot of that in DFW. I don't think the data is going to reflect what's happening in the market until Dec/ Jan.
I'm of the mindset that this is going to be a slow-motion car crash. I don't think that a month or two is going to have a crazy impact, no cliff in sight. Let 5-6 months of 6+ rates sink in to see the full impact on values. I don't see them leveling out for a while. I think it's going to be a slow, steady decrease in values as long as we have rates at or above 6. - Member since 2022 · 485 posts · 216 votes3y
Quote from @Greg R.:
Couple thoughts on this...Quote from @Carlos Ptriawan:
Quote from @Greg R.:
I'm just net getting where the optimism is coming from. We're seeing pretty significant shifts in the market already, and this is only with data from Sep - which has rates that were locked quite a bit prior.From Zillow as it's very accurate and having real-time updates.
Two aspects :- home active inventory is almost zero growth MoM now with negative listing remaining negative MoM
- in Zillow most home sold in Sep has price in upper 5% , in July August it was noticeable -10 - 15% ranges
In the worst market (San Jose) we see stabilizing price between August-September data, for crash to happen August-Sep should reduce more than prev. mnth, it didn't happen. Crazy, the market is front-running Fed actions LOL.
I know inventory had no growth, but demand has also tanked. I need to get updated stats, but even with the lack of new listings last time I checked (in DFW), the months supply of inventory increased. Therefore the low level of new listings was greater than the amount of sales, creating a net positive impact on inventory.
I don't think it's been enough time to evaluate value decrease. How could have values stabilized in Aug-Sep when a lot of home are lingering and seeing big price decreases. I'm seeing a lot of that in DFW. I don't think the data is going to reflect what's happening in the market until Dec/ Jan.
I'm of the mindset that this is going to be a slow-motion car crash. I don't think that a month or two is going to have a crazy impact, no cliff in sight. Let 5-6 months of 6+ rates sink in to see the full impact on values. I don't see them leveling out for a while. I think it's going to be a slow, steady decrease in values as long as we have rates at or above 6.Demand falling was expected That's the belief most of us have is that most people will sit tight. If demand falls and it stagnates we are less likely to see a massive "crash" / adjustment.
I do think it's a little early but the other reason people see some positive is if inflation continues to slow and demand/rate increases slow - when the entire east coast has not had a negative impact there is reason to think it's just a small correction overall through the next 6 months.
Everything you and most here are pointing to is primarily West Coast towns impacted by rates the most. If things are starting to slow down, even if more pain is coming, there's a lot of the US that has just had slower demand but not necessarily any major change. So thats the reason to say it might not be too bad.
I've seen a lot of analysts point to hyper-regionalized, and it almost always is, but it feels like this is going to be more true to an extreme.


