Austin Market Report - September 2026
September changed the picture somewhat for the Austin-area housing market. Pending contracts fell below last year's levels for the first time in 2026, while new listings increased. Prices, meanwhile, remained fairly stable.
Here's the September snapshot for the 5-county Austin metro:
Closed sales: 2,449 (-6.5% year over year)
Pending sales: 2,222 (-5.9%)
New listings: 3,785 (+7.9%)
Median sold price: $415,360
Average sold price: $567,222
Months of inventory: 5.3 (up from 4.9 in August)
Buyer Demand Weakens
Pending sales declined 5.9% year over year, the first month in 2026 that contracts fell below last year's levels.
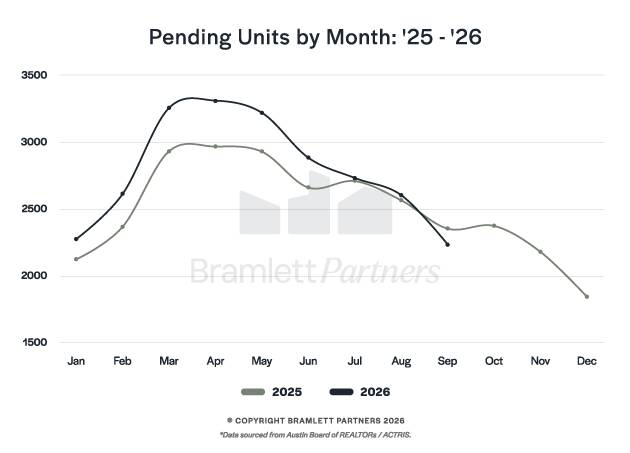
Some seasonal decline is expected, but this year's drop was considerably steeper than last year's. Pending sales dropped 14.4% from August, compared with roughly 6% over the same period last year. Since pending contracts typically precede closings by several weeks, this points toward softer sales activity heading into the final months of the year.
More Listings, Fewer Contracts
New listings increased 7.9% year over year, reversing the pattern we saw in August, when new listings were down.
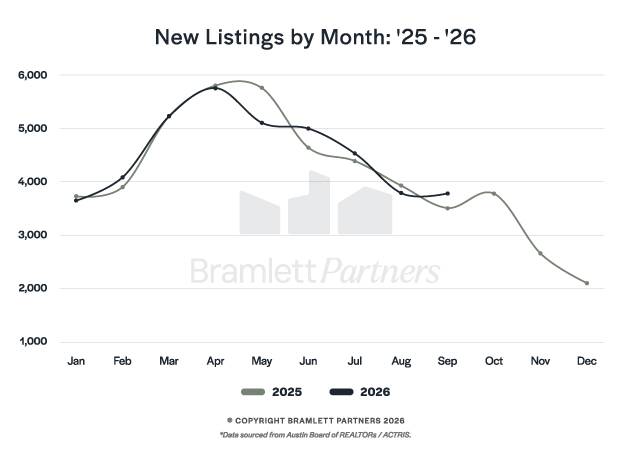
With new listings rising and contracts falling, months of inventory increased from 4.9 in August to 5.3 in September. Interestingly, that's still below the 5.5 months recorded a year ago. By traditional measures, we're approaching the inventory levels associated with a balanced market, but we're not seeing an extraordinary buildup of supply.
Prices Remain Relatively Stable
September's average sold price was $567,222, while the median was $415,360. Both edged up slightly from August, following two consecutive months of declines.

These figures suggest some near-term stability, although average and median sale prices are influenced by the mix of homes selling and aren't necessarily reliable measures of appreciation or depreciation for comparable properties.
For now, the more pronounced change in the market appears to be in transaction activity rather than prices.
Mortgage Rates Add Pressure
Mortgage rates climbed sharply through September and into October. Freddie Mac's national 30-year fixed average reached 7.4% on October 8, its highest level since November 2023. The Fed also raised its benchmark interest rate by a quarter point in September.
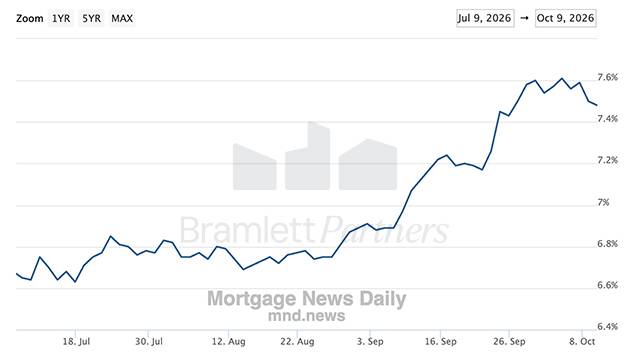
For perspective, a buyer putting 20% down on a $415,000 home would pay roughly $310 more per month in principal and interest at 7.4% than at the 5.98% average recorded in February. That's a meaningful change in affordability, particularly for first-time buyers and investors financing purchases.
My Take
September's numbers are clearly softer, but I don't think they support an overly pessimistic interpretation either. Closed sales declined 6.5% year over year, yet year-to-date dollar sales volume remains 5.2% ahead of 2025. Inventory is higher than in August but slightly lower than a year ago. And prices are holding relatively steady despite weaker demand.
For buyers, the slowdown should create additional negotiating opportunities, particularly on properties that have been sitting. For sellers, realistic pricing is increasingly important as we move into the slower fall and winter months.
For investors, I continue to think Austin is a market where the individual deal matters much more than broad appreciation assumptions. Financing costs remain challenging, and purchases need to make sense based on today's numbers rather than anticipated rate cuts or a quick return to strong appreciation.
The main change from August is that demand has weakened while new listings have increased. That's worth watching, particularly with mortgage rates back above 7%. For now, though, the evidence points more toward slowing activity than a significant decline in prices.
As always, real estate is hyperlocal. If anyone is looking at a specific Austin-area property, neighborhood, or investment, I'm happy to help think through the numbers and strategy.