Buying property-All Cash
Member since 2021 · 38 posts · 20 votes
It seems that purchasing property in all cash would have the best outcome for investments. The owner would not have a mortgage. The owner would have to pay property taxes. Buying with all cash gives the owner the option to lease or live in the property. Buying assets in all cash can increase savings over time. Overall, this is the most secure and reliable form of real estate investing. 🏠👍
For most people starting out all-cash is not an option. Another way of looking at this is how much appreciation did you give up while saving to do the transaction all-cash. In economics this is called an "opportunity cost."
Show me your actual 1099 and property address and I'll plug in the numbers today and see if buying in cash would be better than putting it in the S&P 500 and we'll see who has the last laugh.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Since your (@KS) experience seems to be only in the world of "all cash buys", and not in the world of leveraged buys,...have you ever heard the expression" you don't know what you don't know"?
All cash buys are the will always give you your lowest return since the actual cost to the REI is just the cash they put in. If you pay all cash, you are paying full price for the property. If you pay with leverage, your total cost is only the down payment,...and the rest is paid buy the tenant...as long as you have positive cash flow. If you don't have positive CF, then the negative CF part is also cash contributed by the REI, which adds to the cost.
The main goal of the CF, is to recover your cost (the DP). Once that happens, and as long as you have positive CF, you have what amounts to a free property. The equity guild up, and added CF are your profit sources, which continue to add up. Remember, once you recover you cost (cash you put in), you have no money in the deal anymore, but you continue to benefit financially, even after you have no money in the game.
Now, how do you do that with the Stock Market?
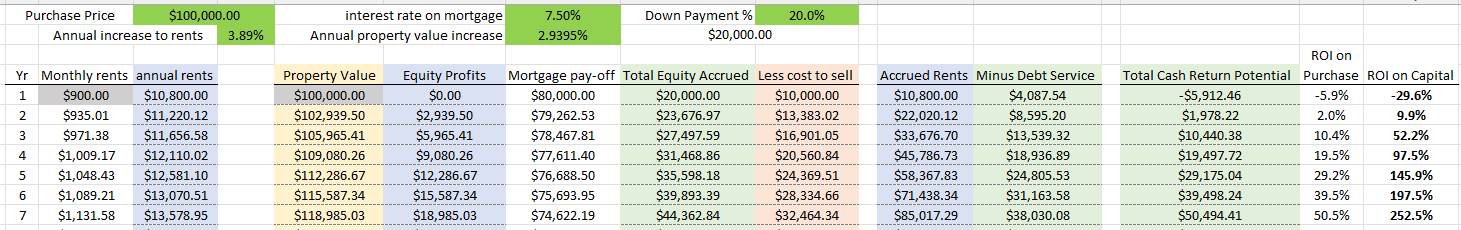
Buy a $100k property, put down $20k, and your CF only needs to recover $20k. Buy $100 stock (or whatever paper you want to buy), you pay $100k for it. That means you dividends have to recover $100k (if the stock pays cash dividends).
Here is the math's to spell it out in "crayola":
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
It's the most conservative investing strategy, but will take the most time to build wealth.

Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Since your (@KS) experience seems to be only in the world of "all cash buys", and not in the world of leveraged buys,...have you ever heard the expression" you don't know what you don't know"?
You mean:
The Dunning-Kruger effect describes a cognitive bias wherein individuals with low ability, expertise, or experience in a particular area overestimate their knowledge or competence. This phenomenon explains how people might be unaware of their lack of knowledge while simultaneously believing they are more knowledgeable than they actually are.
I hate the phrasing "you don't know what you don't know". Instead just use knowledge gaps, unforseen variables or blind spots etc.
Now to answer your question, yes in fact, since as you already know having owned a house, tax returns and 1099s, I was easily able to figure out how many houses I would need to beat the market at 25% down. I believe it was around 4. But other youtubers have done this math and came out with up to 9 properties or similiar. No thank you, I'd rather just put more money into the market. So to answer your question, yes. Yes I do understand what you're saying. Do you understand any of my arguments against leverage that I have made?
Not trying to be mean but I'm pretty sure you're not reading my posts or comprehending them because I'm actually not advocating for purchasing all cash in fact, I'm saying DON"T purchase all cash. Have you not been getting that this whole time? I'm not even arguing against your super basic leveraged position. I have a mortgage just like you do. But I still prefer index funds for all the aforementioned points I made. If the OP is like me which he sounds like he is, then he should take my advice as I've been there, done that and did it during the good times. Buying cash now even at high interest rates, may be a worse idea now than it would have been 10 years ago.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!

It seems that purchasing property in all cash would have the best outcome for investments. The owner would not have a mortgage. The owner would have to pay property taxes. Buying with all cash gives the owner the option to lease or live in the property. Buying assets in all cash can increase savings over time. Overall, this is the most secure and reliable form of real estate investing. 🏠👍
Alot of people would disagree with you, but I am in the minority and personally follow this philosophy with my residential rentals because it hardens them against a severe recession and the risk of losing the property if and when rents fall too low to support a mortgage.
And my father in law is essentially retired and did so after paying off all his rental mortgages to own them free and clear. His rentals are now a reliable source of steady and recurring income (which is invaluable for a retired person but also a small % few have...beyond a tiny Social Security check).

Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!
if you cannot see the difference, then index funds are definitely your correct path.
>250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference.…I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market?
Or in 2014 you could have purchased 1 property at 80% LTV (10 years ago 80% LTV was easily available even on duplex to quad, but today in not SFR you would likely use 75% LTV) for 1.25m. Even if the index fund doubled the RE appreciation, due to the leverage, the RE return from appreciation would have 2.5 times the unleveraged stock return. 1 property, leveraged. I will say the index fund would require less effort, thought, etc.
now if you add a value add to the RE (requiring more effort, thought, etc), you could have in short period extracted the $250k and repeated it if desired. If it is not your cup of tea (because value adds are work), take the extracted $250k and put it in the index fund. Now you have both and a more diversified position than either index fund or RE alone.
i have no idea why you keep using your unleveraged example as proof. Over 80% of initial purchases use financing (and this is significantly lower than before the rates rose; it was approaching 90% a couple of years ago). It is my belief, but I have never seen any stats, that over 50% of cash purchases are either 1) not actual cash as HML, private money, heloc on different asset all count as cash at purchase 2) are short term cash plays such as would be done by a flipper or BRRRR. they buy in cash, but in the near term the RE will be financed. So your purchase and its performance is not using methods that are in alignment with most purchases. I earlier debunked the 6 properties statement. Not sure who you are listening to there but they clearly did not put forth much thought about it.
Your all cash purchase is on topic for this thread. You do a good job of showing why all cash in most markets will not be the best option. Your experience has zero applicability to leveraged purchases, value adds, other types or RE assets other than residential, etc.. What I am finding challenging is why this is difficult for you to understand.
You pose your examples as to why RE investing does not work even though you did things different than the majority of RE purchasers. I pose my experience using leverage as the counter experience. It happens that at least some of our experience is in the same market. I show it is definitely possible. I have done well enough in RE to be retired from w2 and to have given away more than 50% of my income in 2022 and 2023. RE has been good to me, but I never claim residential RE is passive and especially value adds are not passive.
Best wishes
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!
No, your not a Troll trolling away what so ever. Ya just like to sit on a Real Estate Investment site and freak out on long winded childish rants of how REI is so dumb/horrible and Wall Street is where it's at....
Yes, all those 401k bazillionaires, lol....
Anyone wanna try the Wallmart test? Walk in a wallmart, notice the aged greeter, cashier etc.? Ask em, if they did there stocks, bonds, mutual funds like good lil sheeple? 9:10 is a resounding yes. Yeah, that's how well that works out.
Good day to you Trolly-McTrollerson.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!
Real estate is better for none of the reasons that were mentioned. Some do apply, but that's not why it'll be superior.
Real estate will be superior because the opportunity knocking on the door is the ongoing devaluation of the USD relative to any real asset class with limited supply. In regards to that impact on society, it's going to be imperative to function. The convergence of that will make REI more sound than when a fat ****ing monkey could buy a cash flowing LTR 10 years ago, and claim it's sound cause of the meager cash flow.
Then add the fact it's devaluation of almost any fiat/monetary currency. And realize how sound real assets are to the structure of society. You get an exponentially better opportunity & reason to invest.
Now, there will be headwinds-- climate change, physical capex to maintain physical structures,human beings, etc. But if you're looking at it properly, the backward dated views are almost irrelevant to the future of what real estate will be forced to do. That's opportunity--sure it's speculation too but so is any investing.
Go into detail about what happened with the tree picture.
The owner owns the land, they have “title.”
Side note: Person owns land title.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!
Real estate is better for none of the reasons that were mentioned. Some do apply, but that's not why it'll be superior.
Real estate will be superior because the opportunity knocking on the door is the ongoing devaluation of the USD relative to any real asset class with limited supply. In regards to that impact on society, it's going to be imperative to function. The convergence of that will make REI more sound than when a fat ****ing monkey could buy a cash flowing LTR 10 years ago, and claim it's sound cause of the meager cash flow.
Then add the fact it's devaluation of almost any fiat/monetary currency. And realize how sound real assets are to the structure of society. You get an exponentially better opportunity & reason to invest.
Now, there will be headwinds-- climate change, physical capex to maintain physical structures,human beings, etc. But if you're looking at it properly, the backward dated views are almost irrelevant to the future of what real estate will be forced to do. That's opportunity--sure it's speculation too but so is any investing.
Go into detail about what happened with the tree picture.
Regarding the tree picture, the same thing happened last year. You can see all the neighbors trees in the distance are also cracked and falling. The trees freeze over when it's cold then the wind breaks them off. The new investor bought it for. $325k. Rents for $1800 rents or 21,600/year. Here are the typical expenses, plus or minus.

This does not include capital expenses for the 15 years I had it like roof, $25k in renovations, HVAC x3, fence x4, unrooting trees x4. Regardless, the rule is around 1% of the value of the home so subtract $7,200/year inlcuding general maintenance. I'm not going to pull the exact numbers I have but the new owner is looking at this.
Here it was, listed on Redfin

Monthly payment = ~$2,600. Rent is only $1800. You can see it's negative cashflow before adding the aforementioned expenses.
So for everyone ever on BP that says "do you know anything about leverage bruh, just buy 10 with 10% down and cashflow bruh. Well this is what you refer to experts calling the "average" home. It falls within this average middle class familiy orientated home that saw average appreciation. You would need 55% down payment to cover this mortgage. You'll need an additional $300/month in expenses or $600/month if you include capital gains expenses. This ~35% expense to rent ratio is considered average efficiency so nothing unusual there. More if you include the sale costs assuming you don't 1031 exchange like I had to and everyone will end up doing so one day. One should keep all this in mind when leveraging themselves and do the proper math. Of course I was cashflowing because I paid cash a long time ago (to the OPs credit) but what BP members fail to understand is that I demonstrated what a good 1% rule home back then, looks like today. Not 15 years ago. You can't leverage with this property. When people just pull 5-10% down payment out of their butt, then they must be talking about very few zip codes left in the US where you can do that but it's a hustle, takes renovation skills, cold calling etc. That's why for the OP, I say just invest in the broad stock market and retire with millions in 20 years. That's good enough for monst people. The example above will keep you poor in 20 years.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!
Real estate is better for none of the reasons that were mentioned. Some do apply, but that's not why it'll be superior.
Real estate will be superior because the opportunity knocking on the door is the ongoing devaluation of the USD relative to any real asset class with limited supply. In regards to that impact on society, it's going to be imperative to function. The convergence of that will make REI more sound than when a fat ****ing monkey could buy a cash flowing LTR 10 years ago, and claim it's sound cause of the meager cash flow.
Then add the fact it's devaluation of almost any fiat/monetary currency. And realize how sound real assets are to the structure of society. You get an exponentially better opportunity & reason to invest.
Now, there will be headwinds-- climate change, physical capex to maintain physical structures,human beings, etc. But if you're looking at it properly, the backward dated views are almost irrelevant to the future of what real estate will be forced to do. That's opportunity--sure it's speculation too but so is any investing.
Go into detail about what happened with the tree picture.
Regarding the tree picture, the same thing happened last year. You can see all the neighbors trees in the distance are also cracked and falling. The trees freeze over when it's cold then the wind breaks them off. The new investor bought it for. $325k. Rents for $1800 rents or 21,600/year. Here are the typical expenses, plus or minus.
This does not include capital expenses for the 15 years I had it like roof, $25k in renovations, HVAC x3, fence x4, unrooting trees x4. Regardless, the rule is around 1% of the value of the home so subtract $7,200/year inlcuding general maintenance. I'm not going to pull the exact numbers I have but the new owner is looking at this.
Here it was, listed on Redfin
Monthly payment = ~$2,600. Rent is only $1800. You can see it's negative cashflow before adding the aforementioned expenses.
So for everyone ever on BP that says "do you know anything about leverage bruh, just buy 10 with 10% down and cashflow bruh. Well this is what you refer to experts calling the "average" home. It falls within this average middle class familiy orientated home that saw average appreciation. You would need 55% down payment to cover this mortgage. You'll need an additional $300/month in expenses or $600/month if you include capital gains expenses. This ~35% expense to rent ratio is considered average efficiency so nothing unusual there. More if you include the sale costs assuming you don't 1031 exchange like I had to and everyone will end up doing so one day. One should keep all this in mind when leveraging themselves and do the proper math. Of course I was cashflowing because I paid cash a long time ago (to the OPs credit) but what BP members fail to understand is that I demonstrated what a good 1% rule home back then, looks like today. Not 15 years ago. You can't leverage with this property. When people just pull 5-10% down payment out of their butt, then they must be talking about very few zip codes left in the US where you can do that but it's a hustle, takes renovation skills, cold calling etc. That's why for the OP, I say just invest in the broad stock market and retire with millions in 20 years. That's good enough for monst people. The example above will keep you poor in 20 years.
Your example is a terrible rental. If that comes into my inbox it gets 1 second look before going on to the next option. It is such a poor rental option that it does not warrant thinking 1 second about the numbers.
I expect that property to be purchased by an owner occupant who could be happy there and is not paying rent to a LL.
If you purchased that property as an investment property (versus a home to Live in), i am confident you did not do a thorough underwriting. There is no way a thorough underwriting ever shows that property as a good investment opportunity compared to other RE purchase options.
Best wishes
Just to clear up that post in case you didn't catch it all, I made it clear that I purchased this over 15 years ago following the 1% rule. The example I'm giving you now is for the new owner who I also mentioned is an investor. I know because the new owner listed it for rent as soon as he closed on it. Whether it's good or bad is not really the point as this is an example of the average home which was once affordable, is not affordable any more making the deals harder to find without a hustle, renovation or collecting rents with a shot gun in C- to D neighborhoods if that's your thing. It's just not as easy as saying, buy 10 properties with 10% down as everyone schools me on how leverage works but most of SoCal, FL and TX that I have looked at, are about 50% down to break even. I know the game has changed but if it wasn't for BP misinformation or the hype around RE with all the videos, radio ads, shows etc, the new investor of this home would probably have passed.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!
Real estate is better for none of the reasons that were mentioned. Some do apply, but that's not why it'll be superior.
Real estate will be superior because the opportunity knocking on the door is the ongoing devaluation of the USD relative to any real asset class with limited supply. In regards to that impact on society, it's going to be imperative to function. The convergence of that will make REI more sound than when a fat ****ing monkey could buy a cash flowing LTR 10 years ago, and claim it's sound cause of the meager cash flow.
Then add the fact it's devaluation of almost any fiat/monetary currency. And realize how sound real assets are to the structure of society. You get an exponentially better opportunity & reason to invest.
Now, there will be headwinds-- climate change, physical capex to maintain physical structures,human beings, etc. But if you're looking at it properly, the backward dated views are almost irrelevant to the future of what real estate will be forced to do. That's opportunity--sure it's speculation too but so is any investing.
Go into detail about what happened with the tree picture.
Regarding the tree picture, the same thing happened last year. You can see all the neighbors trees in the distance are also cracked and falling. The trees freeze over when it's cold then the wind breaks them off. The new investor bought it for. $325k. Rents for $1800 rents or 21,600/year. Here are the typical expenses, plus or minus.
This does not include capital expenses for the 15 years I had it like roof, $25k in renovations, HVAC x3, fence x4, unrooting trees x4. Regardless, the rule is around 1% of the value of the home so subtract $7,200/year inlcuding general maintenance. I'm not going to pull the exact numbers I have but the new owner is looking at this.
Here it was, listed on Redfin
Monthly payment = ~$2,600. Rent is only $1800. You can see it's negative cashflow before adding the aforementioned expenses.
So for everyone ever on BP that says "do you know anything about leverage bruh, just buy 10 with 10% down and cashflow bruh. Well this is what you refer to experts calling the "average" home. It falls within this average middle class familiy orientated home that saw average appreciation. You would need 55% down payment to cover this mortgage. You'll need an additional $300/month in expenses or $600/month if you include capital gains expenses. This ~35% expense to rent ratio is considered average efficiency so nothing unusual there. More if you include the sale costs assuming you don't 1031 exchange like I had to and everyone will end up doing so one day. One should keep all this in mind when leveraging themselves and do the proper math. Of course I was cashflowing because I paid cash a long time ago (to the OPs credit) but what BP members fail to understand is that I demonstrated what a good 1% rule home back then, looks like today. Not 15 years ago. You can't leverage with this property. When people just pull 5-10% down payment out of their butt, then they must be talking about very few zip codes left in the US where you can do that but it's a hustle, takes renovation skills, cold calling etc. That's why for the OP, I say just invest in the broad stock market and retire with millions in 20 years. That's good enough for monst people. The example above will keep you poor in 20 years.
Your example is a terrible rental. If that comes into my inbox it gets 1 second look before going on to the next option. It is such a poor rental option that it does not warrant thinking 1 second about the numbers.
I expect that property to be purchased by an owner occupant who could be happy there and is not paying rent to a LL.
If you purchased that property as an investment property (versus a home to Live in), i am confident you did not do a thorough underwriting. There is no way a thorough underwriting ever shows that property as a good investment opportunity compared to other RE purchase options.
Best wishes
You must not be paying attention. I litterally made it clear that I purchased this over 15 years ago following the 1% rule. The example I'm giving you now is for the new owner who I also mentioned is an investor. I know because the new owner listed it for rent as soon as he closed on it.
@Mark Cruse using a loan will just prolong your return on investment.
Let's check what math says about this:
A property at $100k, with $1k rents. That would be 100 months or 8.33 years.
OR, $25k down (the investment made) $1k rents minus $544 debt service = $456. $25k/$456 = 54.82 or 4.56years.......
4.56 years seems a LOT faster an investment return than 8.33.......
I am getting an ever stronger sense that you chose the conclusion Eric, and are just pressing that assumed conclusion regardless of facts presented that prove different.
The math is clear, use of leveraged funds significantly amplifies returns.
Here's one youtube link of many showing that renting is better. Buying cash can only be worse considering that cash can be invested at way higher than the average rate of appreciation of 3%. But this question continues to be asked over and over again when it's a pretty simple answer. If you have the money and don't care that you'll lose 900k in a decade from not investing that cash into the market instead. Then buy cash. It's your money. I'm not saying to buy with a mortgage either as the video states, this is bad investment advice as well for the average american at this moment in time (unless you're starting a family and can afford it). Leveraging yourself could also take a lot of properties like 10? just to beat the market according to another video breakdown so I also don't trust the leverage guys. If you're the type of person that has to ask this question, then just put your money in the market and wipe your hands and be done with it. Try VOO (S&P 500) or similar dividend fund which doesn't make sense but some people like the psychological feeling of monthly "rent" like checks. And remember, you can average down during a 50% crash. But when real estate crashed 50% during the great recession, nobody averaged down, it's called foreclosure. And don't forget to max your 401k matching. I've already earned about 100k in just a few years of maxing with my employers 5% match. Don't fall for the RE hype.
Why are you here K S.? I mean, other than to Troll? I don't see anything but Trolling here and hilarious levels of misinformation.
How about a Reality Check, shall we....
Real world scenario, one I just looked at. Brand new build, so no maint or cap-x for years making #'s simpler to flesh out. $340k on buy, market rent's $2,700mnth. I know this is market rent because I already lease others at this in this community of this exact floor plan.
I have $32,400 annual revenue. Minus HOA, P.tax, insurance and all operational expenses I have $26,950 OR in % I have a 7.9% COC.... Already, without anything else, I just beat most everything in "the market"......
BUT, I ALSO get appreciation which assuming really long hold is 2.9% as shown as median as averaged out over many decades. That's another $9,860 in my pocket putting us now at 10.8% ROI.
But wait, it get's BETTER.... because rents are not static, rents go up at about 4.5% annual.....
It's laughable, LAUGHABLE, to try and compare index funds too REI.
And what does one do in an '08' style "collapse", duh, ya DON'T sell, ya RENT IT OUT! Because guess what happened in '08' when OVER-LEVERAGED fools were suffering there accountability of dumb financial actions? Yeah, they became TENANTS! Rents shot through the roof as the demand exploded! So hummm let's see, what to do what to do, rent's going up 20%+ annual OR I can sell at huge discount, what to do, what to do...... ya RENT it out! And within a few years, like magic all equity is back and then some.
And now biggest problem is the property is such a cash-cow that ya don't ever want to let it go.
Ah the classic troll accusation to bring more credence to your own argument so you don't have to bring as much substance to your own. Your excessive use of ALL CAPS shows your overly emotional investment to a very low stakes situation. I'm surprised you haven't been banned yet with your condescending attitude towards other peoples experiences which only derails the integrity of the subject matter and exposes your own maturity level.
And to answer your question, I'm here responding because I have purchased 7 properties in all cash over the years making my personal experience a perfect fit to answer this particular subject as I have first hand experience and can provide actual value to the subject. What's laughable, I mean LAUGHABLE, is your theoretical example from the interweb when I brought receipts using my actual tax statements and 1099s.
Secondly, the OP or other questioner has expressed gratitude for my wisdom on this subject.
I notice in every thread you respond to, you brag about your own personal success in order to lift your fragile ego so I'll mention that I also recently purchased a condo with a 7.6% COC return in San Diego last year. But even at 10% with appreciation as you stated, that doesn't beat the 13% the S&P 500 did over the last decade. Sorry but 13% beats 10% even with the perks. What most don't realize is that 13% is compounding. Your cash on cash return does not compound. You realize that correct? It's always 7.9% on your principal no matter how much appreciation you gain, but the S&P 500 compounds. As you make an additional $25/year in rent appreciation, your HOA + Property taxes + maintenance + these new insurance premiums + lawsuit risks, will consume your $25/year increase. I know because I've owned a house for 20 years. I know macro economics is important so anyone can search the internet and come up with their own theories on the subject or a more favorable example and that's great, but this is just my personal experience. Your mileage may vary. But to call someone a troll is a cheap shot exposing your own inability to acknowledge others experiences and exposes your emotional maturity level. Reported!
Your experience is relevant to the OP’s posts about all cash purchase but your responses do not cover other options or discounts them and in some instances your response has some incorrect stats
I will address some directly:
- RE fell between 20% and 33% during the Great Recession (GR) not the 50% you claim. Look it up.
- when stocks fell during the Great Recession so did the dividends. In most RE markets rents did not decline (there are definitely exceptions such as Detroit, Las Vegas, etc., but most markets rents did not fall significantly). This implies the cash flow in most markets did not take a hit. We had units in San Diego at the GR. We did not lower any rents.
- RE in last decade has appreciated more than 2.9%. So 13% S&P over last decade should be compared with RE over last decade and not longer term historical that would include the GR in S&P number but include it in the RE number. Deceiving comparison.
- the op is talking unleveraged and unleveraged RE does not significantly outperform broad based stock markets often (meaning it occurs rarely). But at 80% LTV the return from RE appreciation is 5x the RE appreciation rate. This virtually always whoops the broader stock market.
- you discuss no compounding and I can see this argument for unleveraged purchases but if I use fixed financing leverage, I fix a large portion of my expense and in effect I get some compounding effect. In Ca this is further magnified due to prop 13 resulting in virtually fixed property tax. If rent goes up, but the majority of my expense is fixed I do compound the rent increase at the same percentage that my expenses are fixed.
- RE has option of value add. I suspect a fairly large percentage of RE investors are using value adds to magnify returns.
- in RE I can pulled out appreciation gain without paying taxes at that time. I can do similar via margin with stocks but margin has more risk.
- in RE I can use 1031 to not pay gains tax upon sale. I with I could do that with stocks.
- in RE I can depreciate the holding and if desired I can accelerate my depreciation. This makes it possible to virtually eliminate taxes for sophisticated investors. I pay virtually no taxes on my RE earnings. Good luck doing this with stocks without RE.
I do think your experience is relevant to this thread. It makes the same argument for not purchasing unleveraged as I advocate. Your example of poor returns from unleveraged RE (with no value add) might be similar return to other RE investors that do not use leverage and do not have a value add. I suspect s&p will often out produce the return of RE that is purchased unleveraged and without a value add.
However, I wanted to present the leveraged side of purchasing RE and other potential benefits of investing in RE.
I also advocate against unleverage RE investing in most RE markets (possible exception for high cash flow, low appreciating, local markets).
Best wishes
1) True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
3) True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
4) 1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Second, 1031 exchange is just shifting money around not avoiding taxes on usable cash. I sold a house last year and needed the money to build another house so I have to take the tax hit. And the government will recapture 25% of those tax deductions I took over 18 years which is way more than if I cash out my stocks or accept dividens. In fact, I could be taxed at 0% if accepting less than 45k/year or similiar.
I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen. In fact, if you sell like I did, you'll end up paying 65k in taxes for a 325k home sale which is I think what I came up with. This does not include the 25k rehab in order to sell at full price, the agent fees and whatever else I forgot. And everyone will need to sell their house at some point like in my case, not 1031 exchange forever. Lastly, you can get a loan using your 401k funds to purchase a house. So you can go from stock to house, but you can't go from house to stock without taking a huge tax hit.
So the market for the win here as far as liquid cash and the ability to reduce your taxes to $0 in some cases as well as some shifting of funds around and getting a home loan against your accounts without a tax hit.
>True, real estate fell 33% on average, but the average is made up of both the lows and highs meaning some major cities like in SoCal and Austin for example saw a much higher decline than 33%. Also, if BP members are going to use the best appreciating locations in their pro RE examples, then you must use those same locations when drawing the opposite conclusion.
Or you site the range of expert averages (I can find legit references that indicate as low as 20% and as high as 33%). What I would not do it state a number outside the expert range such as a 50% decline (that you used) and attempt to pass that off as the normal decline. I think most people understand that there will be those that experience both better and worse than the average.
>2) According to chatgpt whether true or not, rent decreased by up to 10% and dividend payouts decreased by 20%. Insignificant enough to not sway me in any direction. But what makes this less of a great example you used, is the fact that you lost hundreds of thousands of dollars in equity/net worth and possibly forclosed on some properties like most Americans did at that time. However, no mainstream index fund like the VOO or some dividend index, got forclosed on. In fact, you just average down in the market causing a much better recovery than continuing to keep those San Diego homes you had. And I'm pretty sure you didn't keep them assuming you purchased pre 2009. You can't average down on foreclosures.
There are so many things in this one post
When a source states up to, they are talking worse case. Not average or usual case. My experience in our 10 rentals (3 areas) was no decline in rental income.
The only way you get foreclosed on RE is missing payments which usually implies leveraged purchase. If I buy stocks levered (I.e. margin) they foreclose even if I have not missed payment. They will sell your holdings if they fall in value below a certain value. Is there a difference? Yes, because if my house looses value but is still generating cash as would be the case if rents have not fallen (which was the case on our 10 units in 3 different markets) I get to keep them without needing to infuse additional capital. Note that under same conditions as margin purchase, I would have been required to sell these cash positive units.
If rents do not go down then the only reason for foreclosure would be if over leveraged. We had no foreclosures and still own 7 of those 10 units. We sold 2 in gulf shores because they got hit back to back years by hurricanes (sometimes wish we kept them) and the other because it was our lone property in that market and was not doing as well as locaL properties.
Note if I was in the s&p500 at GR (which I was), it lost 48% between aug 2008 and mar 2009. Note this is far greater loss than the total average RE decline from the GR.
Seeing I had no foreclosures, I did equivalent to dollar cost average as we were coming out of the GR. I pretty much purchased a property per year starting at the depreciated price after GR and stopping in Dec 2021 (purchased $4m that month). I have made some offers since Dec 2021, but have not purchased as the rates do not have underwriting that shows my high expectations on return.
>True that RE also averaged higher than 3-4% in the last decade from our artificially created boom and corrupt politicians and government, but thats where the market shines, VOO or whatever index, is the same for everyone. But the majority of people purchase "average" real estate properties and does not reflect the an increase in HOA, insurance, gas, electric, taxes, management and maintenance. So while the top 15% of investors strike the location jackpot, most are not and that appreciation has also been eaten up by the afforementioned. Not entirely, but it's not all gravy.
I am not sure why it matters the cause of the price increase or why you think the increase in RE prices derives from different economics than the rise in stock Prices. I suspect we can agree both benefitted from low rates.
I used the average appreciation recognizing the average will have some above and below the average. The average does not only represent the top 15%. If your point is some markets have done much worse than others (including worse than mine), I think that is understood.
>1031: I think there's a misconception here. First off, in some brokerage accounts, you can move money around index funds without incurring a taxable event i.e VTSAX to VTI or something or withint a 401k or Roth and completely change your funds much like a 1031 Exchange.
Are you sure you are in a taxable account? I will need to ask my investment advisors. Definitely you cannot do this in a taxable account purchasing individual stocks.
Certainly Roth accounts have no gains tax regardless if used to purchase stocks or RE.
> I bet most people didn't know that probably not even you. You can't take 45k/year out in real estate via a cash out or HELOC or home sale. NOT gona happen.
I am not sure what you are saying but assure you I have extracted a lot more than $45k/year from my properties (but $0 in last 2 years). I suspect near 10x that amount (likely have averaged near $450k). Why do you think you cannot do it? What is preventing one from doing it other than they need to have at least $60k equity gain (At 75% LTV)? This equity gain can be from value add, appreciation and/or equity paydown. For me to do 10x that amount I need $600k of equity gain per year which I have done for at least the last 6 years.
>everyone will need to sell their house at some point like in my case, not 1031 exchange forever.
Definitely not true that everyone has to sell. People die all the time holding RE and when they do, the value of the RE gets re-based at current value and the gains are never taxed. Wouldn’t that be sweet for stocks in a taxable account? This is almost too good to be true. So the plan is keep and/or 1031 until I die, then have all gains and depreciation magically ripped away via the current tax laws. Good luck accomplishing that with stocks that are not in a Roth.
Best wishes.
By now you should recognize if you make up data on my market 1) I will call you out and provide correct info 2) that if you need to make up info to make your case, then you do not really present a good arguments.
>Those 2005-2007 properties in SoCal have just recently and finally hit there previous peaks,
This is so wrong. Here are some real years that markets surpassed previous high
- Los Angeles: 2018
- Orange County: 2016
- Ventura county: 2020
- San Bernardino: 2020
- riverside: 2020
- San Diego: 2020
- Santa Barbara: 2018
Each of these markets are far higher today than their high from prior to Great Recession. Many (I suspect all) of these counties including my San Diego market are over 50% higher than the high prior to GR. your made up stats demonstrate a weak argument because why make up stats if you do not need to make them up to try to make your case? https://www.laalmanac.com/economy/ec37.php
>If it takes actively investing in 4-10 properties to beat the returns of the gold standard S&P 500 for instance, is that worth it to you? That's a fat no!.
I agree it would not be worth it. Good thing that virtually all my RE has produced infinite return and every one of my current holdings has done far better than the return of the S&P 500. I personally would not choose to purchase residential RE unless my underwriting shows far greater than double the historical return of the S&p500. Good thing virtually all my purchases have infinite return and have been worth the effort of residential RE (that I have never claimed is passive).
The more you post, the more I understand why an index fund that requires no thought is the best choice for you. RE investing is not for everyone. Invest in your index funds; it appears to be the right choice for you.
Best wishes
To keep saying real estate is better than the broad market is not an argument. To say that I must not understand the concept of real estate simply because I prefer the broad market in most situations and have talked about the benefits, is an ad hominem attack. Attacking me instead of the argument. You have not shown data on your actual investments going back but I have and I have compared them both leveraged and unleveraged.
I have to address this infinite returns talk. So my index fund doubles and I cash out my original investment and my new position continues to return dividends or gains. That's infinite returns. Infinite returns is not some RE only thing. And infinite returns does not mean your return is beating the broad stock market either.
Lets compare infinite returns in RE to the broad stock market. In RE, it's not infinite returns if you're pulling a 10% investment loan out. You better make sure your're investing those gains in something else that returns more than the amount you're borrowing. In stocks, I can just cash out and pay whatever capital gains tax is. So they have their pros and cons I guess but they're both infinite and is not unique to RE. But once you're in RE, that money is trapped forever. I still have a cash out at a 6% interest rate only because I got lucky with the timing. Say good buy to those days.
For those that are watching and just want something they can retire from in 20 years, please type 250,000 in the S&P History calculator from 2012 to 2024 and see that 250k invested 10 years ago is worth $1,200,000 today. Sorry but no 250k condo or house paid in cash 10 years ago is worth $1.2M today and even if you leveraged yourself, it would take a lot of these homes to make up that difference. . Edit: My rental below has trippled since my last purchase over 15 years ago but after all expenses after the sale including taxes, recapture, renovations, agent fees etc, I believe I would need to leverage 6 of these homes to beat the market. 6 of these below. Actively investing in 6 of these homes just to beat the passive broad stock market? And this was the good times, the 1% rule times. Now, you guys are f-ucked. Enjoy!
Real estate is better for none of the reasons that were mentioned. Some do apply, but that's not why it'll be superior.
Real estate will be superior because the opportunity knocking on the door is the ongoing devaluation of the USD relative to any real asset class with limited supply. In regards to that impact on society, it's going to be imperative to function. The convergence of that will make REI more sound than when a fat ****ing monkey could buy a cash flowing LTR 10 years ago, and claim it's sound cause of the meager cash flow.
Then add the fact it's devaluation of almost any fiat/monetary currency. And realize how sound real assets are to the structure of society. You get an exponentially better opportunity & reason to invest.
Now, there will be headwinds-- climate change, physical capex to maintain physical structures,human beings, etc. But if you're looking at it properly, the backward dated views are almost irrelevant to the future of what real estate will be forced to do. That's opportunity--sure it's speculation too but so is any investing.
Go into detail about what happened with the tree picture.
Regarding the tree picture, the same thing happened last year. You can see all the neighbors trees in the distance are also cracked and falling. The trees freeze over when it's cold then the wind breaks them off. The new investor bought it for. $325k. Rents for $1800 rents or 21,600/year. Here are the typical expenses, plus or minus.
This does not include capital expenses for the 15 years I had it like roof, $25k in renovations, HVAC x3, fence x4, unrooting trees x4. Regardless, the rule is around 1% of the value of the home so subtract $7,200/year inlcuding general maintenance. I'm not going to pull the exact numbers I have but the new owner is looking at this.
Here it was, listed on Redfin
Monthly payment = ~$2,600. Rent is only $1800. You can see it's negative cashflow before adding the aforementioned expenses.
So for everyone ever on BP that says "do you know anything about leverage bruh, just buy 10 with 10% down and cashflow bruh. Well this is what you refer to experts calling the "average" home. It falls within this average middle class familiy orientated home that saw average appreciation. You would need 55% down payment to cover this mortgage. You'll need an additional $300/month in expenses or $600/month if you include capital gains expenses. This ~35% expense to rent ratio is considered average efficiency so nothing unusual there. More if you include the sale costs assuming you don't 1031 exchange like I had to and everyone will end up doing so one day. One should keep all this in mind when leveraging themselves and do the proper math. Of course I was cashflowing because I paid cash a long time ago (to the OPs credit) but what BP members fail to understand is that I demonstrated what a good 1% rule home back then, looks like today. Not 15 years ago. You can't leverage with this property. When people just pull 5-10% down payment out of their butt, then they must be talking about very few zip codes left in the US where you can do that but it's a hustle, takes renovation skills, cold calling etc. That's why for the OP, I say just invest in the broad stock market and retire with millions in 20 years. That's good enough for monst people. The example above will keep you poor in 20 years.
Your example is a terrible rental. If that comes into my inbox it gets 1 second look before going on to the next option. It is such a poor rental option that it does not warrant thinking 1 second about the numbers.
I expect that property to be purchased by an owner occupant who could be happy there and is not paying rent to a LL.
If you purchased that property as an investment property (versus a home to Live in), i am confident you did not do a thorough underwriting. There is no way a thorough underwriting ever shows that property as a good investment opportunity compared to other RE purchase options.
Best wishes
You must not be paying attention. I litterally made it clear that I purchased this over 15 years ago following the 1% rule. The example I'm giving you now is for the new owner who I also mentioned is an investor. I know because the new owner listed it for rent as soon as he closed on it.
You should write a book. The property marked all the check boxes of that time so your opinion on what makes a good investment back then was not the standard 15-20 years ago. So you're wrong. When speaking to average investors like me or the OP, speak from the perspective that most of us don't get deals in their inbox like you mentioned. Must be nice.
Edit: Telling me that my property was a bad investment 15-20 years ago is like me telling you that you failed as a stock investor because you didn't beat the S&P 500.