Hard Money Lender Xpress Loans 911
Colorado Springs, CO · Member since 2020 · 6 posts · 6 votes
Has anyone ever worked with the hard money lender Xpress Loans 911?
Did they help close any of your deals? I have one where they are looking to help finance $500.5K but I need to pay a $4995 commitment fee. Any thoughts? I'm nervous about doing this. Need some guidance...
No offense but this is crazy stupid.. no one charges 1 point up front just for a commitment fee .. its just not done like this in the industry.
Yes, the NC Commissioner of Banks & Others were notified long before a complaint was lodged with the BBB.
Bob, your no merit comment just flew out the window.
Better Business Bureau Tue, Nov 24 at 2:09 PM
Complaint ID#: 582073
Business Name: Xpress Loans 911 LLC
BBB Comments / Request:
11/24/2020- ELMR. Your concerns may be best handled by the regulatory agency below:\par NC Commissioner of Banks\par 4309 Mail Service Center\par Raleigh, NC 27699-4309 \par 919-733-3016\par https://www.nccob.gov/public/ConsumerInformation/Complaints/CIFileComplaint.aspx
Do Hard Money Lenders need to be licensed?
Hard money lenders offer loans that your bank cannot. They lend based (mostly) on collateral instead of credit scores. ... Hard Money Lenders generally need to be licensed in each state- typically via the Department of Real Estate, and one person associated with the lending needs their Real Estate Broker License.
Do Hard Money Lenders need to be licensed? (licenselogix.com)
Thanx for showing up Bob.
Ben while I agree with those who think the advanced fee lending companies have business practices that are simply not done by most of the top HML.
U are confusing the owner occ loan with the business purpose loan.. Owner occ loans in every state need state license and NMLS registration that is a given.
However the majority of states allow business purpose NON OWNER occ loans without any license.. there are about 12 states that you need to have a license.. I can name a few off the top of my head.. OR CA NV TN come to mind .. So you need to understand the difference between the two loans. And the license in the states that require HML to be licensed is ONLY for 1 to 4 units.. if its 5 units and up or strip center or bare land etc.. no license required. At least its that way in OR for sure.. So this is very state specific . Being Oregon based when i was active I had all the licenses .. my # is 157464 that's the NMLS registration number.. YOu need a state license to get one of those .. if you pop that into the system you can see my history and the fact that my CE is current but I am not active at this time.
so bottom line I suspect for the loans that 911 was doing and if they have any clue.. they are working in states that allow the non owner occ without a license.. Still think the big advance fee is BS though and those that pay it simply dont know they should not be paying it and shopping around.
To do the types of loans being discussed here let's understand one thing, in North Carolina a business offering loans has to be registered with the state and post a bond payable to the state.
Chapter 66, Article 20
https://www.ncleg.net/EnactedL...
>>> § 66-111. Remedies.
(a) If a loan broker uses any untrue or misleading statements in connection with a loan brokerage contract, fails to fully comply with the requirements of this Article, fails to comply with the terms of the contract or any obligation arising therefrom, or fails to make diligent effort to grant a loan to or procure a loan on behalf of the prospective borrower, then, upon written notice to the broker, the prospective borrower may void the contract, and shall be entitled to receive from the broker all sums paid to the broker, and recover any additional damages including attorney's fees.
(b) Upon complaint of any person that a loan broker has violated the provisions of this Article, the superior court shall have jurisdiction to enjoin that defendant from further such violations.
(c) The remedies provided herein shall be in addition to any other remedies provided for by law or in equity.
(d) The violation of any provisions of this Article shall constitute an unfair practice under G.S. 75-1.1. (1979, c. 705, s. 1.) <<<
Search for Xpress Loans 911 LLC
Ben, I just read through the NC NMLS requirements on the NMLS site.. It appears to me that license is required only for own occ resi loans.
I know there is a lot of confusion with this license stuff.. When i first started in Oregon I thought I was exempt then I had my first state audit ( mandatory for every broker) and they specifically asked what type of loans I was doing.. and of course we were doing loans on fix and flip SFRS all over the country and I thought because it was business purpose ( like the state of Washington) we were exempt.. NOPE.. So I told the auditor we made no loans.. she described the above to me and said to me would you like to change your statement now.. and I said YUP. If that's the case here in Oregon we made 400 loans LOL.. so I got a poor rating first Audit.. Then I just had to follow a few rules.. ( I had the license).. and all was good.
But I cant find any exemption for non owner occ in a quick google Search of NC laws.. So for me I would get on the phone with the regulators and ask them specifically this should be a very quick conversation your either exempt like 911 is saying or your not and subject to full licensure U can google the 12 states that require it.. I guess I should do that and See if NC is on the list.. And laws change to..
However one thing is abundantly clear you filed a complaint with the state they WILL follow up and let you know if there is a violation or not.
There was a very big HML company from Washington that was doing loans in Oregon with no license and they did 100 mil or so .. kind of astonishing they did not know the laws at their size.. State gave them cease and desist but only fined them 30k and don't do it again. or get a license I will say they probably spent another 20 to 50k in legal fee's as they would have had to go in for a full blown in person examination at the state Capital. However I knew borrowers who were able to come at them with claims of loans made illegally and the lender accepted payoffs with all interest payments being credited towards principal.. If the borrower was smart enough to figure it out.
In your case you never got a loan and are a victim of an advance fee brokerage.. Or should I Say had a bad experience with an advanced fee brokerage.. Do post again when the state makes a determination if this company or any HML needs to be licensed.
One thing I read in the regs is an individual for their personal portfolio is exempt if they make 5 or less loans in a year or have 5 or less in their portfolio.. this tends to be the rules in most states it allows private folks to use their IRA money to make a few loans as alternatives to other real estate investments.
What these unscrupulous so called lenders know is that we are in a Corona-19 Pandemic.
CONSUMER BEWARE!
here is the Oregon rules from NMLS
Who does not need this license?Your company may be exempt from the Oregon Mortgage Lending Licensing requirements if you are any of the following:A financial institution, as defined in ORS 706.008.A financial holding company or a bank holding company, as defined in ORS 706.008, and you do no more than control a subsidiary or affiliate, as described in 12 USC 1841, and do not engage in the business of a mortgage banker or broker. An attorney licensed in this state who negotiates mortgage banking loans or mortgage loans in the ordinary course of business, unless the business of negotiating mortgage banking loans or mortgage loans constitutes substantially all of the attorney’s professional activity.A person who, as seller of real property, receives one or more mortgages or deeds of trust as security for a separate money obligation.An agency of any state or of the United States.A person who receives a mortgage or deed of trust on real property as security for an obligation payable on an installment or deferred payment basis and arising out of materials furnished or services rendered in the improvement of that real property or any lien created without the consent of the owner of the real property.A person who funds a mortgage banking loan or mortgage loan which has been originated and processed by a licensee or by an exempt person and who does not maintain a place of business in this state in connection with funding mortgage banking loans or mortgage loans, does not directly or indirectly solicit borrowers in this state for the purpose of making mortgage banking loans or mortgage loans and does not participate in the negotiation of mortgage banking loans or mortgage loans. For the purpose of this subparagraph, “negotiation of mortgage banking loans or mortgage loans” does not include setting the terms under which a person may buy or fund a mortgage banking loan or a mortgage loan originated by a licensee or exempt person.A nonprofit federally tax exempt corporation certified by the United States Small Business Administration and organized to promote economic development within this state whose primary activity consists of providing financing for business expansion.A person who makes a loan secured by an interest in real estate with the person’s own moneys, for the person’s own investment and who is not engaged in the business of making loans secured by an interest in real estate
So its very clear a license is required on any 1 to 4 unit regardless.
IN NC there is no definition like this which would lead someone to think the business purpose loans could be exempt.
What these unscrupulous so called lenders know is that we are in a Corona-19 Pandemic.
CONSUMER BEWARE!
this is the list of the states that are KNOWN to require licenses for non owner occ 1 to 4 units.
Business Purpose Residential Mortgage Loans
People often refer
to non-owner occupied business purpose residential mortgage loans as
commercial loans. Again, that is not what I am referring to above on
this page, however if you are interested in doing non-owner occupied
business purpose residential mortgage loans, the following states may
require licensing:
Alabama, Arizona, California, Colorado,
Florida, Idaho, Illinois, Louisiana, Michigan, Minnesota, Nevada, New
Jersey, North Dakota, Oregon, Rhode Island, South Dakota, Texas, Utah,
and Vermont
What these unscrupulous so called lenders know is that we are in a Corona-19 Pandemic.
CONSUMER BEWARE!
here is a good website to get some info on who needs licenses this company is a license training company so they would know.
https://www.integritymortgagel... this is worth reading.. But again its very state specific and the only way to confirm is with your state Mortgage license division.. And as you said if you have indeed filed a complaint you will get your answer.
Just a friendly reminder
(1) Ben Marine is NOT a client of Xpress Loans He was NEVER a CLIENT OF XPRESS LOANS He has NO business dealings with Xpress Loans
(2) Ben Marine NEVER PAID an advance fee to Xpress Loans
(3) Ben Marine is NOT his actual NAME
(4) The subject property that Ben Marine is talking about is NOT even in North Carolina therefore North Carolina law does not apply
"One thing I read in the regs is an individual for their personal portfolio is exempt if they make 5 or less loans in a year or have 5 or less in their portfolio.. this tends to be the rules in most states it allows private folks to use their IRA money to make a few loans as alternatives to other real estate investments." - @Jay Hinrichs
Jay - This rule has allowed me to use my self-directed IRA and ROTH funds on real estate filps in Portland OR.
With mania level housing prices, surprised people on BiggerPockets don't talk about this strategy more often, e.g. lend 2nd position note recorded via Trust Deed. The trend is to flip SFH out of state. In my opinion, this is way riskier for a novice then doing short term notes on a local flip.
Well folks, Robert Edward Berg, should stop.
As it's been said, when one finds themselves in a hole they should stop digging.
Send me a request if you want me to post "Loan Broker" rules/laws from the other 48 US states, North Carolina and South Carolina have now been posted on this thread.
Code of Laws - Title 34 - Chapter 36 - Loan Brokers (scstatehouse.gov)
South Carolina Code of Laws
Unannotated
Title 34 - Banking, Financial Institutions and Money
CHAPTER 36
Loan Brokers
SECTION 34-36-10. Definitions.
As used in this chapter, unless the context otherwise requires:
(1) "Advance fee" means any consideration which is assessed or collected, prior to the closing of a loan, by a loan broker.
(2) "Borrower" means a person obtaining or desiring to obtain a loan of money, a credit card, or a line of credit.
(3) "Department" means the Department of Consumer Affairs.
(4) "Loan broker" means any person who:
(a) for or in expectation of consideration arranges or attempts to arrange or offers to fund a loan of money, a credit card, or a line of credit;
(b) for or in expectation of consideration assists or advises a borrower in obtaining or attempting to obtain a loan of money, a credit card, a line of credit, or related guarantee, enhancement, or collateral of any kind or nature;
(c) acts for or on behalf of a loan broker for the purpose of soliciting borrowers; or
(d) holds himself out as a loan broker.
A "loan broker" does not include any bank or savings and loan association, trust company, building and loan association, credit union, consumer finance company, retail installment sales company, securities broker-dealer, real estate broker or salesperson, attorney, Federal Housing Administration or Veterans Administration approved lender, credit card company, installment loan licensee, mortgage loan broker registered under Chapter 58, Title 40 and acting within the scope of its certificate of registration, or insurance company, who is licensed by and subject to regulation or supervision of any agency of the United States, the South Carolina Board of Financial Institutions, or other agency of this State and is acting within the scope of the license; and also does not include subsidiaries of licensed or chartered consumer finance companies, banks, or savings and loan associations.
(5) "Principal" means any officer, director, partner, joint venturer, branch manager, or other person with similar managerial or supervisory responsibilities for a loan broker.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
SECTION 34-36-20. Prohibited behavior; advance fees; false, misleading, fraudulent, or deceptive acts.
No loan broker shall:
(1) assess or collect an advance fee from a borrower to provide services as a loan broker.
(2) make or use any false or misleading representations or omit any material fact in the offer or sale of the services of a loan broker or engage, directly or indirectly, in any act that operates or would operate as fraud or deception upon any person in connection with the offer or sale of the services of a loan broker, notwithstanding the absence of reliance by the buyer.
(3) make or use any false or deceptive representation or conceal a material fact in its business dealings with the borrower or with the department.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
SECTION 34-36-30. Principal responsible for acts of brokers and brokers' agents or employees.
Each principal of a loan broker may be sanctioned for the actions of the loan broker, including the loan broker's agents or employees acting in the course of business of the loan broker.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
SECTION 34-36-40. Department oversight; orders and acts to effect compliance.
(A) The department may investigate the actions of any person for compliance with this chapter.
(B) The department may request a hearing before the Administrative Law Court for an order requiring a loan broker to cease and desist if it is determined that the loan broker has violated, is violating, or will violate a provision of this chapter, a regulation promulgated by the department, or a written agreement entered into with the department.
(C) The department may request a hearing before the Administrative Law Court for an order requiring a loan broker to refund or reimburse any advance fee or any other fee taken in violation of Section 34-36-20 or taken as a result of a false, misleading, or deceptive representation as described in Section 34-36-20. Such an order may, but need not, be sought by the department in conjunction with a cease and desist order pursuant to subsection (B).
(D) The department may request a contested case hearing before the Administrative Law Court seeking the imposition of a civil administrative fine on behalf of the department against any person found to have violated any provision of this chapter, any regulation promulgated by the department, or any written agreement entered into with the department, in any amount not to exceed five thousand dollars for each violation.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992; 2005 Act No. 128, Section 2, eff July 1, 2005.
Effect of Amendment
The 2005 amendment, in subsections (B), (C) and (D), added the references to hearings before the Administrative Law Court and made conforming amendments.
SECTION 34-36-50. Investigations and examinations to determine violations; obtaining evidence; witnesses and subpoenas; confidentiality; injunctions and other means of enforcement; cooperation with other enforcement agencies.
(A) The department may make investigations and examinations upon reasonable suspicion within or outside of this State as it considers necessary to determine whether a person has violated or will violate any provision of this chapter or any regulation promulgated hereunder.
(B) The department may gather evidence regarding any broker if the department has reasonable suspicion the loan broker has violated or will violate any provision of this chapter or any regulation promulgated under it. The department may administer oaths, examine witnesses, and issue subpoenas.
(C) The department may issue subpoenas for witnesses whose evidence is deemed material to any investigation or examination commanding the witnesses to be or appear before the department at a time and place named and to bring those books, records, and documents as may be specified or to submit the books, records, and documents for inspection. The subpoenas may be served by an authorized representative of the department.
(D) In the event of substantial noncompliance with a subpoena or subpoena duces tecum issued by the department, the department may petition the circuit court of the county in which the person subpoenaed resides or has its principal place of business for an order requiring the person to appear and fully comply with the subpoena. The court may also grant injunctive relief restraining a violation of this chapter and may grant that other relief, including, but not limited to, the restraint, by injunction or appointment of a receiver, of any transfer, pledge, assignment, or other disposition of the person's assets or any concealment, alteration, destruction, or other disposition of subpoenaed books, records, or documents, as the court deems appropriate until the person has fully complied with the subpoena or subpoena duces tecum and the department has completed its investigation or examination. Costs incurred by the department to obtain an order granting, in whole or in part, the petition for enforcement of a subpoena or subpoena duces tecum must be taxed against the subpoenaed person, and failure to comply with the order is a contempt of court.
(E) Witnesses are entitled to the same fees and mileage as they may be entitled by law for attending as witnesses in the circuit court, except where the examination or investigation is held at the place of business or residence of the witness.
(F) The material compiled by the department in an investigation or examination under this chapter is confidential until the investigation or examination is complete or final action by the department is otherwise taken. The investigation or examination is not deemed complete if the department has submitted the material or any part of it to any law enforcement agency or other regulatory agency for further investigation or for the filing of a criminal or civil prosecution and the investigation and prosecution have not been completed or become inactive. This confidentiality provision shall not prohibit:
(1) the disclosure of investigative material in investigations that are otherwise final if the material submitted to the other law enforcement agency is not directly related to loan brokering business; or
(2) the disclosure of such material as is public information after civil or criminal prosecution is filed.
(G) The department shall cooperate with and assist other state or federal agencies in enforcing applicable regulation of loan brokers to the extent such cooperation and assistance does not violate this chapter or the public policy of this State. The department may authorize such state or federal agencies to represent it for the purpose of administering oaths, examining witnesses, or issuing subpoenas under this chapter.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
SECTION 34-36-60. Actions to enjoin violations; impounding of property; appointment of receiver or administrator; order of restitution.
(A) In addition to other remedies set forth in this chapter, whenever the department determines, from evidence satisfactory to it, that any person has engaged, is engaged, or is about to engage in an act or practice constituting a violation of this chapter or a regulation promulgated hereunder, the department may bring action in the name and on behalf of the State against the person and any other person concerned in that practice in violation of this chapter to enjoin the person or persons from continuing the violation. In the court proceedings, the department may apply for and on due showing is entitled to have issued, the court's subpoena requiring the appearance of any defendant and his employees or agents to testify or give evidence concerning the acts or conduct or things complained of in the application for injunction, and requiring the production of documents, books, and records that may appear necessary for the hearing of the petition.
(B) In addition to all other means provided by law for the enforcement of any temporary restraining order, temporary injunction, or permanent injunction issued in the court proceedings, the court shall have the power, upon application of the department, to impound and to appoint a receiver or administrator for the property, assets, and business of the defendant, including, but not limited to, the books, records, documents, and papers appertaining thereto. The receiver or administrator, when appointed and qualified, shall have all powers and duties as to custody, collection, administration, winding up, and liquidation of this property and business as is from time to time conferred upon him by the court. In the action, the court may issue orders and decrees staying all pending suits and enjoining any further suits affecting the receiver's or administrator's custody or possession of this property, assets, and business, or in its discretion may with the consent of the chief administrative judge of the circuit, require that all these suits be assigned to the circuit court judge appointing this receiver or administrator.
(C) In addition to any other remedies provided by this chapter, the department may apply to the court hearing this matter for an order of restitution whereby the defendants in the action must be ordered to make restitution of those sums shown by the department to have been obtained by them in violation of any of the provisions of this chapter. The restitution, at the option of the court, must be payable to the administrator or receiver appointed pursuant to this section or directly to the persons whose assets were obtained in violation of this chapter.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
SECTION 34-36-70. Violations; penalties.
Any person violating any provision of this chapter is guilty of a misdemeanor and, upon conviction, must be punished by a fine not exceeding five thousand dollars or by a term of imprisonment not exceeding one year, or both. Each violation of this chapter constitutes a separate offense.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
SECTION 34-36-80. Violation constitutes unfair trade practice; actions for damages; remedies additional to those otherwise provided.
(A) A violation of this chapter shall constitute an unfair trade practice under Chapter 5, Title 39, and individual borrowers or prospective borrowers injured by violations of this chapter have an action for damages as set forth in Section 39-5-140.
(B) Any borrower injured by a violation of this chapter may bring an action against the surety bond or trust account, if any, of the loan broker.
(C) The remedies provided under this chapter are in addition to any other procedures or remedies for any violation or conduct authorized by law.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
SECTION 34-36-90. Department responsible for administration and enforcement of chapter; authority to promulgate regulations.
(A) The department is responsible for the administration and enforcement of this chapter.
(B) The department is authorized to promulgate those regulations necessary to implement and administer the provisions of this chapter.
HISTORY: 1992 Act No. 452, Section 1, eff June 15, 1992.
Just a friendly reminder
(1) Ben Marine is NOT a client of Xpress Loans He was NEVER a CLIENT OF XPRESS LOANS He has NO business dealings with Xpress Loans
(2) Ben Marine NEVER PAID an advance fee to Xpress Loans
(3) Ben Marine is NOT his actual NAME
(4) The subject property that Ben Marine is talking about is NOT even in North Carolina therefore North Carolina law does not apply
I just paid them $3000 and I’m reading these now and getting very worried. They’re so in a hurry to collect the money that it looks really fishy.
I haven't checked this thread in 4 months, and it looks like I missed some fireworks!
Also, anyone who read the few earlier replies from the newly created account 4 months ago of Robert Berg (the account got deleted since then), will note that Robert's grammar is exceptional now. Looks like he took some typing lessons from Jill Berg, with his new account created in NOV.
Check out his rant to @Jay Hinrichs at the top of page 4, to see just how far he has come along.
This entire thread is by no means a joy to read, but there are quite a few lessons to be learned.
I don’t know why people are not calling out this company all over the internet for the fraud they are! They have gone ahead to generate fake reviews for themselves online, which is what my partner saw and called them, but I’ll head out to every site they have those fraudulent reviews and call them out. XPRESS LOANS 911 IS A FRAUDULENT COMPANY!!! Listen, before I came on here, I had already unfortunately paid them $3,000 because my partner did not do due diligence. Infact, up until today, we have not signed any of their documents so the money they took from is not under any mutual agreement of non being non-refundable. We practically sent them the funds on Friday pending signing the request on Monday following, and when I found out they were fraudulent, I called immediately to cancel and request our money back but they refused and were even trying to get us to send them a balance of $7,000 to sign up for a property we had already lost to another buyer. Meaning we should give them $9,995 even though we don’t have any property in the works to buy. Who does that?
Since it wasn’t a signed contract between us, we have gone ahead to report to all the authorities, fortunately, our local police is very diligent in investigations and we’re cooperating with them to fish these criminals out, but it doesn’t end there for me!
They may think $3,000 is small money but if they don’t return my money by the end of this week, My $3,000 will be the last they’d ever scam anyone in peace.
They picked the wrong person this time. I won’t even as much as call or text them but you’ll hear the way they’d end up soon. Even Karma will be so embarrassed for them.
@NA NA Thank you for keeping up posted on this. I am actually curious where it goes. The NC sos filings you posted have Jill as the registered agent but the address listed for the registered agent is owned by another individual and has never been owned by the Berg's or a business/trust in the past 10 years. Not sure who they got to take on the liability. Crazy story and sad to see they are still taking people's money. @Oma Albert
@Oma Albert How did you pay them? Have you tried to put a stop payment on the transfer? Report it to your bank as fraud and they will also do their own investigation while working to get your money back.

@Ryan
@Ryan Blake, my partner paid them through Zelle, we have reported it as fraud to the bank and also alerted the police. For some reason, Chase may just be shielding this criminals; there account is with chase and my partner used a chase account to transfer with Zelle. Chase was hesitant to flag it as fraud until we got the police involved.
@Oma Albert I know you have learned this. This is for everyone else. A legitimate hard money lending company will NOT use zelle, paypal, or other pay apps to collect a payment. It will need to be a wire with a receipt of transfer. Pay apps are commonly used by fraudulent groups because it is easy to have money funnel to accounts in other countries that have anonymity protection. At that point the money is lost. Hence most scams ran out of India involve whatsapp or other pay apps.
My wife used Zelle too, I believe she sent them $3,100.00 before I caught this scam. Also, they would not release any records or documents concerning the transaction which they alleged she could access online, she couldn't as they blocked the account.
So, if they've scammed you and you have documents file a complaint here:
Consumer Inquiries and Complaint Information (nccob.gov)
I've heard back from the NC Commissioner of Banks that office directed me to contact the NC Department of Justice as the NCCB doesn't have jurisdiction.
I haven't done that however, their attorney Ayelet Faerman sent me a threatening email to remove my content from Bigger Pockets or we would face a federal lawsuit.
I asked their attorney to have her clients issue a full refund as it is reasonably believable that XPRESS LOANS should not be charging non-refundable upfront fees in connection with any loan.
My wife and I both have excellent credit, and my wife should not have been steered into a "hard money loan" by Xpress Loans.
My wife went behind my back and conducted the transaction in question with Xpress without consulting with me.
When I contacted Robert Berg and asked him for all of the loan documents he knew or should have reasonably known that I had a Power of Attorney granted to me by my wife. When my wife tried to download the loan documents she had been blocked.
Also, my wife sent them a copy of the Lease on the property she tried to leverage for a loan which I have managed for over 18 years, wherein the Lease clearly states my name and "AGENT."
As an aside, I'm a US Marine Corps veteran that suffers with PTSD.
Hey Bob, issue a full refund that money you received is unearned. No services were completed.
It's not the questions, it's the answers.
I suggest to you and allege that Xpress Loans 911 LLC may be operating in a gray area of the law, no regulations/no oversight in relation of their advance loan commitment fees and other loan practices described by myself and others on this forum.
Xpress Loans LLC has been forced to answer questions.
The Saga Continues.
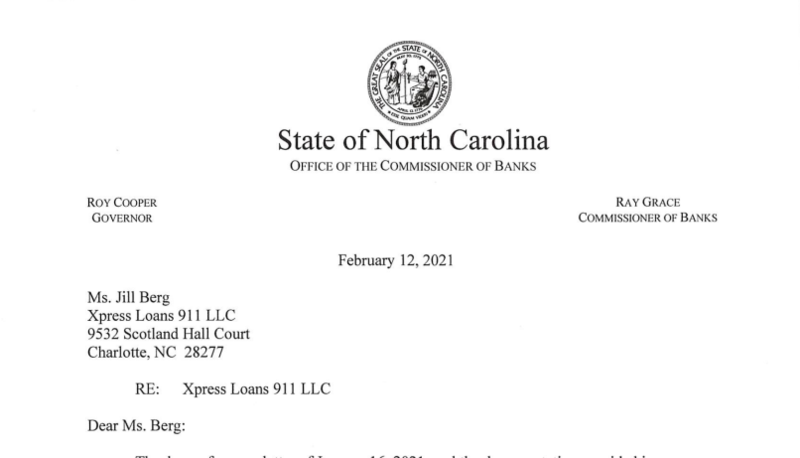
Is Xpress Loans 911 LLC non-refundable, paid in advance loan commitment fees sometimes collected from borrowers via Zelle... Legal or not legal, as it appears Xpress operates within a gray area of the law, no regulations/no oversight?
Asking for a friend.
@NC_Governor @JoshStein_ @JoeBiden @KamalaHarris @SpeakerPelosi @SenSanders @LeaderHoyer @WhipClyburn @JoeCrowleyNY @RepJerryNadler @RepAdamSchiff @JacksonLeeTX18 @repbenraylujan @RepJeffries @RepMaxineWaters @RepSwalwell @SenSchumer @AOC @RashidaTlaib @RepPressley @IlhanMN @BarackObama @BillClinton @TomPerez @TulsiGabbard @SenWarren @harrisonjaime @AndrewYang @PeteButtigieg @TomSteyer @amyklobuchar @DevalPatrick @JohnDelaney @MichaelBennet @MikeBloomberg @HillaryClinton @ABC @AP @BostonGlobe @CBS @CBSNews @chicagotribune @CNN @CNNPolitics @dailybeast @Forbes @FoxNews @Gannett @latimes @MSNBC @NBCNews @nytimes @Reuters @sfchronicle @thehill @USATODAY @washingtonpost @WashTimes @WSJ @allinwithchris @andersoncooper @brithume @ByronYork @chrislhayes @DanRather @DavidFrum @RealDLHughley @Eugene_Robinson @gtconway3d @Jennifer44040 @JoeNBC @JoyAnnReid @Lawrence @LouDobbs @maddow @mitchellreports @Morning_Joe @paulkrugman @soledadobrien @TheLastWord @TheRevAl @senatemajldr @GOPLeader @RepDevinNunes @Jim_Jordan @RandPaul @VP @WhiteHouse @LindseyGrahamSC @SenatorTimScott @RepRalphNorman @tedcruz @RepDougCollins @SenThomTillis @GOPChairwoman @WalshFreedom @MittRomney
@NA NA @Oma Albert U guys really need to check out the American Greed episode on Remington financial
and then check out Ingrid Robinson and the FBI agent who took them down.. Ingrid has a very good website for fraudulent pump and dump due diligence lenders like these folks appear to be based on your posts.
@Ryan
@Ryan Blake, my partner paid them through Zelle, we have reported it as fraud to the bank and also alerted the police. For some reason, Chase may just be shielding this criminals; there account is with chase and my partner used a chase account to transfer with Zelle. Chase was hesitant to flag it as fraud until we got the police involved.
NEVER PAY WITH ZELLE PAY PAL OR ANY OTHER OF THESE ON LINE THINGS.. YOU SHOULD ONLY PAY VIA WIRE TO A REPUTABLE TITLE AND ESCROW COMPANY NEVER TO THE LENDER THAT IS JUST NOT DONE IN THE INDUSTRY . YOUR LEARNING NOW BUT FOR ANYONE READING THIS THREAD SENDING MONEY TO A LENDER SIMPLY IS NOT DONE YOUR GOING TO LOSE IT.
I agree that the money they received is unearned and fraudulent. In my case, we hadn’t signed any of their documents to validate the non refundable clause they had, my partner had only made a deposit and when he handed me the documents to review, I saw inconsistencies that flagged the company as fraudulent and in less than 24 hours, I had called them asking for a refund and stating that we will not be signing or proceeding with them.
One of their agents had the guts to say that they had signed the documents on our behalf to expedite the process. Who does that?
@NA NA please reach out to me as my partner and I are willing to join in the suit on this fraudulent company/group of people. We have made reports to our local authorities in the State and they’re already investigating. These people should not be allowed to keep defrauding innocent citizens of their hard earned money.
