I threatened to stop paying escrow to my new lender. It worked!

I threatened to stop paying escrow to my new lender. It worked!

Rental Property Investor · Boise/Portland · Member since 2017 · 709 posts · 742 votes

Two months ago, I completed a REFI to lower my rate and increase cashflow. Within two weeks of closing, my lender sold the note to a large lender based in Florida which I’d never heard of. I was shocked to read ABYSMAL reviews from hundreds of people who had complained about the particular lender, and they weren’t shy about using some colorful language. The primary issue is the lender is repeatedly negligent about paying taxes and insurance from the escrow they're collecting with the mortgage payments.

Before my first payment was due, I emailed the new lender and included copies of the complaints I’d read online. I told them in no uncertain terms that I would place the house on the market, sell it, do an Exchange, and find another lender if they did not allow me to self-pay the taxes and insurance. Surprisingly they agreed.

QUESTION: Has anyone experienced a lender agreeing to waive the collection of escrow payments AFTER the loan docs have been signed which stipulate escrow payments will be collected?

1Reply
127 views

Most Popular Reply

Theresa HarrisPro Member
Member since 2019 · 15k+ posts · 11k+ votes
6y

I'm in Canada, but with one mortgage the bank messed up and didn't pay property taxes.  We got it fixed, but after that I changed it so I paid not them.  It wasn't a problem, I just went to the bank and had it changed...for free.

See this reply in the discussion

25 Replies

Jump to latestLatest
  • Rental Property Investor · Doylestown, PA · Member since 2008 · 1k+ posts · 1k+ votes
    6y

    @Matthew McNeil - Wow!  Did you have to sign any additional or revised loan docs?  Who's the lender?  You can message me if you don't want to post in the forum.

  • Developer · Boise, ID · Member since 2020 · 173 posts · 198 votes
    6y

    @Matthew McNeil First of all Nice Work! We have all had an experience with a bad debt servicer. Just be careful and follow up with something in writing while, because while this may look and sound good at first glance , you are going to want to get everything in writing. The reality is your loan docs stipulate that you will pay these things through escrow and if you do not you would be in default of the documents you signed. And as we all know it stated many times in the hundreds of pages of documents that you signed that failure to pay will result in default. We also know that while you are very keenlyaware of what is happening with all your properties, most servicers are not. Communication from one department to another could break down and you could find yourself in a world of hurt!

    I am wanting to hear how this resolves its self so keep me posted, just document everything.

  • Theresa HarrisPro Member
    Member since 2019 · 15k+ posts · 11k+ votes
    6y

    I'm in Canada, but with one mortgage the bank messed up and didn't pay property taxes.  We got it fixed, but after that I changed it so I paid not them.  It wasn't a problem, I just went to the bank and had it changed...for free.

  • Investor · Leander, TX · Member since 2016 · 299 posts · 402 votes
    6y

    No problem with self pay with any of my lenders. 


    I actually self pay all my insurance premiums in full at the beginning of the year for a discount with my insurance company because I bundle. 

    It takes a little effort with the lenders, because they are not used to clients doing this and you have to make sure they are not still taking money out for insurance with your monthly payments. I still want them to take money out and hold in escrow for the taxes.

    I had one lender after I communicated to them that I was going to be paying my insurance in full for the year up front and that I no longer wanted them to hold money in escrow for insurance, close the whole escrow account including the money held for taxes, and they sent me back all the money that was escrow, in which I had to send right back saying I still wanted them to hold money for taxes.

    It took a few phone calls to get that through to them.

  • Rental Property Investor · Northern, CA · Member since 2012 · 5k+ posts · 5k+ votes
    6y

    I had a mortgage with an escrow account set up where the lender missed making my insurance payment multiple times. I finally just called them up and asked what their criteria/process was to cancel the escrow account and let me make my own insurance/property tax payments. They explained what it was and I subsequently canceled the escrow account and began making my own payments.

    It was actually pretty easy. My guess would be that other lenders have a similar process for being able to cancel your escrow account. At the end of the day, they just want the insurance and property tax paid (regardless of who pays it). 

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    6y
    Originally posted by @Kyle J.:

    I had a mortgage with an escrow account set up where the lender missed making my insurance payment multiple times. I finally just called them up and asked what their criteria/process was to cancel the escrow account and let me make my own insurance/property tax payments. They explained what it was and I subsequently canceled the escrow account and began making my own payments.

    It was actually pretty easy. My guess would be that other lenders have a similar process for being able to cancel your escrow account. At the end of the day, they just want the insurance and property tax paid (regardless of who pays it). 

    seem to recall if you let the lender/servicer pay tax's and insurance you also get a few bps off of the rate..  ???  so if you do that get the lower rate then cancel this service.. i wonder how that works.. I can see the lenders side they want to make sure these things are done instead of chasing after borrowers who don't pay and then they have to put force placed insurance on the property etc..  

    my last loan I did and I only have one loan total.. but I chose to pay my own tax's and insurance up front as I found with impounds they usually are sitting on a fair bit of your money..  One time i paid off a loan and my escrow account had 9k in it.. they never got it to me I forgot about it until someone was checking with lost funds in Oregon and noted i had 9k sitting there LOL.. which i applied for and got back but 5 or 6 years later :)  

  • Rental Property Investor · Northern, CA · Member since 2012 · 5k+ posts · 5k+ votes
    6y

    For what it's worth, I just did a refi on a different property last month, and that lender gave me the option of escrow account or no escrow account.  They didn't seem to care one way or the other (and no discount for picking one option over the other unfortunately). 

    I ended up picking no escrow account to keep things simple and so I knew the insurance and property taxes would get paid.  :)

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    6y
    Originally posted by @Kyle J.:

    For what it's worth, I just did a refi on a different property last month, and that lender gave me the option of escrow account or no escrow account.  They didn't seem to care one way or the other (and no discount for picking one option over the other unfortunately). 

    I ended up picking no escrow account to keep things simple and so I knew the insurance and property taxes would get paid.  :)

    things seems to have changed a bit..  vis a vi the discount offered for full service loans.

    you OK with the fires are you in Sonoma county/  I am watching the fire maps and man that is going through all my old stomping grounds 

    especially hwy 29 from Calistoga to Middle town.. there is OLD growth forest up there in the palisades and Robert Luis Stevenson Park my first recollections of driving that road were in the mid 60s.. 

  • Rental Property Investor · Northern, CA · Member since 2012 · 5k+ posts · 5k+ votes
    6y

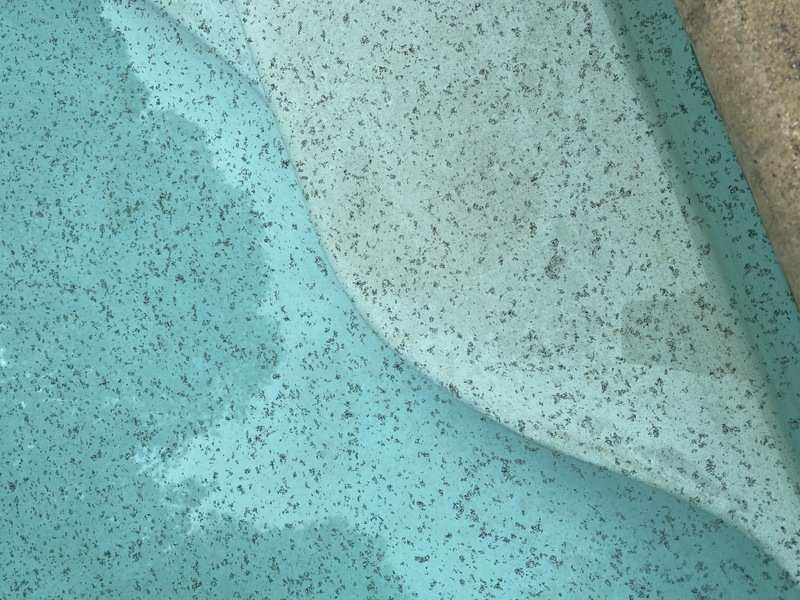
    @Jay Hinrichs  Yes, the smoke/ash is pretty bad.  Check out this photo I woke up to one day of ash in my pool (it's like it's snowing some days, except it's ash):
  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    6y
    Originally posted by @Kyle J.:

    @Jay Hinrichs  Yes, the smoke/ash is pretty bad.  Check out this photo I woke up to one day of ash in my pool (it's like it's snowing some days, except it's ash):

    I started my career in real estate sales in Lake Mendo Sonoma county and a few one offs in Napa.. I did land sales so i have driven and been around so much of this terrain not just the main roads but back in the boonies .. not to mention being based at Lampson ( airport just south of Lakeport)  in my early flying days.. AS we know there have always been the brush fires.. I remember when one started in Ukiah and burnt over to Lakeport and took out 90% of cow mountain area.. but the majority of that was just low brush chaparral.. now its in the old growth forests and that is a tragedy.

    Not to mention all the folks that are losing their homes.  I lived at Silverado for a decade so many of my old buds there got burnt out and many left as they were too old to rebuild.. changed a lot of the dynamics of the membership there.

  • Rental Property Investor · Napa, CA · Member since 2016 · 69 posts · 75 votes
    6y

    @Jay Hinrichs


    Do you recall the Hanley fire? It’s was in 1964, it burned from Calistoga to Santa Rosa. Basically the same burned area as the 2017 Tubbs fire. Between the Valley fire in 2015, the Tubbs fire in 2017 and now the Glass fire, Mt St Helena is pretty much completely burned. The fuel loading was so heavy up on the mountain, I would be surprised if the old growth forest survives. 

  • WorldWide · Member since 2016 · 1k+ posts · 1k+ votes
    6y

    if you're over 20% equity and in good standing, there is no reason for them not to agree. i cancelled mine as soon as i hit that on my primary. don't need to prepay a nanny to do this for me. Suntrust was horrid thruout that process, tho. Been thinking about refinancing with a local CU lately. 

  • Rental Property Investor · Portland OR · Member since 2018 · 2k+ posts · 3k+ votes
    6y

    You can self pay T&I for residential mortgages,  but not for commercial loans, I dont think - commercial side is pretty conservative right now as they are ALSO asking for anywhere from 9-18 months of PI,TI reserves too!~  that adds up soo fast....  I have over 300k sitting in reserve accounts right now....  yay feds hating PDX!

  • Russell BrazilBusiness Member
    Moderator
    Real Estate Agent · Washington, D.C. · Member since 2012 · 17k+ posts · 30k+ votes
    6y

    If your less than 80% ltv, escrow is optional.

  • Investor · USA · Member since 2015 · 168 posts · 243 votes
    6y

    Lenders take whether having escrow account as a risk factor(not sure whether make sense or not).  In several cases I did not want escrow accounts, but they told me I need to pay more fees if no escrow accounts.  Many lenders allow you to cancel the escrow accounts after a period of time, mostly one or two years. I once tried to cancel several escrow accounts from two lenders, one lender allowed me to cancel  after one year, another lender needed to wait for two years.   For the first lender, I just emailed them and told them that I want to cancel the escrow accounts and they canceled them immediately. For the second lender I had to call them and they sent me the cancel escrow account documents, I signed and sent back then the accounts were cancelled. So different lenders handle differently. 

  • Rental Property Investor · Boise/Portland · Member since 2017 · 709 posts · 742 votes
    6y
    Originally posted by @Salvatore Lentini:

    @Matthew McNeil - Wow!  Did you have to sign any additional or revised loan docs?  Who's the lender?  You can message me if you don't want to post in the forum.

    Hi Salvatore. The lender is Lakeview Loan Servicing. I wasn't required to sign additional or revised docs.  Following is a paste from the email I received from their Oversight Manager;

    "We have approved your request to waive the escrow account as an exception. There are some regulations surrounding that process which require a 10-day waiting period. Therefore, we entered the request today and unless you change your mind within that 10-day waiting period, we will process the waiver once the waiting period expires on or after October 9th. We cannot adjust the payment to remove escrow from the monthly payment until the waiting period has expired and the waiver is fully complete."

    I plan to wait and see how this unfolds going into the next month.


  • Rental Property Investor · Boise/Portland · Member since 2017 · 709 posts · 742 votes
    6y
    Originally posted by @Shannon Robnett:

    @Matthew McNeil First of all Nice Work! We have all had an experience with a bad debt servicer. Just be careful and follow up with something in writing while, because while this may look and sound good at first glance , you are going to want to get everything in writing. The reality is your loan docs stipulate that you will pay these things through escrow and if you do not you would be in default of the documents you signed. And as we all know it stated many times in the hundreds of pages of documents that you signed that failure to pay will result in default. We also know that while you are very keenlyaware of what is happening with all your properties, most servicers are not. Communication from one department to another could break down and you could find yourself in a world of hurt!

    I am wanting to hear how this resolves its self so keep me posted, just document everything.


    Shannon. Good advice! I'll make sure I get everything in writing and stay on top of this.
    Noted regarding your "default" advice.  I certainly don't want that to happen simply because I trusted they'd accommodate my demands regarding the escrow. 

    I'll provide an update as this unfolds....  Regards.

  • Rental Property Investor · Boise/Portland · Member since 2017 · 709 posts · 742 votes
    6y
    Originally posted by @Kyle J.:

    For what it's worth, I just did a refi on a different property last month, and that lender gave me the option of escrow account or no escrow account.  They didn't seem to care one way or the other (and no discount for picking one option over the other unfortunately). 

    I ended up picking no escrow account to keep things simple and so I knew the insurance and property taxes would get paid.  :)

    Kyle, I've been given the option to self-pay escrow on other loans. This one in particular, however, would not allow that as was very clearly detail in the loan documents. Thus, my reason for making this post. I'm going to move forward carefully to make sure they document their agreement allowing me to self-pay aside from an email.  And, I'll continue to pay the escrow until I'm assured in writing. Otherwise, I don't want them to come back on claiming a default as was mentioned above by Shannon.

  • Investor · Arlington, VA · Member since 2017 · 37 posts · 9 votes
    6y

    I asked my lender this morning about escrow vs no-escrow and here's the response I got:

         You can waive escrows but typically there is a .25% (of loan amount) cost

    I received this note during a Q&A w/lender before applying for a loan (w/20% down payment), so not sure how it would fare after loan docs have been signed.

  • Rental Property Investor · Frisco, TX · Member since 2020 · 18 posts · 18 votes
    6y

    @Matthew McNeil wow sounds great

  • Rental Property Investor · Boise/Portland · Member since 2017 · 709 posts · 742 votes
    6y
    Originally posted by @Russell Brazil:

    If your less than 80% ltv, escrow is optional.

    LTV on that property is 64%. I was not given an escrow option. I'll push for it next time. Another learning notch in my RE experience.

  • Rental Property Investor · Boise/Portland · Member since 2017 · 709 posts · 742 votes
    6y
    Originally posted by @Shannon Robnett:

    @Matthew McNeil First of all Nice Work! We have all had an experience with a bad debt servicer. Just be careful and follow up with something in writing while, because while this may look and sound good at first glance , you are going to want to get everything in writing. The reality is your loan docs stipulate that you will pay these things through escrow and if you do not you would be in default of the documents you signed. And as we all know it stated many times in the hundreds of pages of documents that you signed that failure to pay will result in default. We also know that while you are very keenlyaware of what is happening with all your properties, most servicers are not. Communication from one department to another could break down and you could find yourself in a world of hurt!

    I am wanting to hear how this resolves its self so keep me posted, just document everything.

    Shannon, regarding my “threat” to stop paying Escrow to the lender that bought my loan after I completed a REFI. You asked for an update.

    The Lender formally “closed” Escrow and mailed me supportive hard copy documentation. The monthly mortgage amount was recalculated to show that I would only be paying principal and interest. Furthermore, they gave me a full refund on the Escrow I paid at Closing. So, it worked out to my benefit without hassle.  Cheers!

  • Rental Property Investor · Boise/Portland · Member since 2017 · 709 posts · 742 votes
    6y
    Originally posted by @Shamit S.:

    I asked my lender this morning about escrow vs no-escrow and here's the response I got:

         You can waive escrows but typically there is a .25% (of loan amount) cost

    I received this note during a Q&A w/lender before applying for a loan (w/20% down payment), so not sure how it would fare after loan docs have been signed.

    Hi Shamit. Turns out that it worked to my benefit after I demanded they comply with my request. See my response to Shannon below.  Cheers!

  • Real Estate Broker · Portland, OR · Member since 2019 · 4k+ posts · 2k+ votes
    6y

    "Has anyone experienced a lender agreeing to waive the collection of escrow payments AFTER the loan docs have been signed which stipulate escrow payments will be collected?"

    Yeah, if you've been a good borrower for a year and the LTV drops.

    However, banks can sell the debt (read the assignment clause in your mortgage) to whoever has the money and wants to service it.

    In any case, it's worth a call emphasizing your good performance and increased value of the property.

  • Developer · Boise, ID · Member since 2020 · 173 posts · 198 votes
    6y

    That is the best deal you  could ask for!!!

Join the conversationCreate a free account to reply, vote on answers and follow this thread.