SubjectTo deal - my first deal

SubjectTo deal - my first deal

Investor 路 Austin, TX 路 Member since 2023 路 12 posts 路 9 votes

Hi, fam. I'm a newbie investor and found a SubjectTo deal here in Texas. I'm super keen to dive into the deal (it'll be my first investment deal), however, I've never done this before. 

Is there anything I need to be aware of in this deal? 
Should I use my real estate agent on this deal, even though I found it? It may be worth having him along for the ride to make sure it's a clean deal.

Should I consult with an attorney?

Do I still get an inspection period in SubTo deals?

How much earnest money should I commit to?

If the loan is an FHA loan, am I meant to move into the home?

So many questions lol. Any help is appreciated, cheers.

-AJ

2Reply
31 views

Most Popular Reply

Attorney 路 Austin, TX 路 Member since 2014 路 888 posts 路 759 votes
2y

Buy sub-2 and then what?

Many sellers, desperate to get out of the house/loan, will thank you today. But in 3-5 years, after you make on-time payments and their credit is improved because of it, they will want to buy another house. The loan on the one they sold you will still show up and underwriters won't let them with the DTI ratios. Now they will try to pressure you into refinancing by messing with your relationship with their lender.

If none of that happens, but there's an insured loss, making a claim will be challenging. Even with a PoA, underwriters and banks can throw up hurdles requiring the seller's cooperation.

If, after reading all that and others' posts, you are still interested, I can walk you through the process if you need it.

See this reply in the discussion

12 Replies

Jump to latestLatest
  • Investor 路 Scottsdale Austin Tuktoyaktuk 路 Member since 2021 路 4k+ posts 路 4k+ votes
    2y
    Quote from @Aj Ulloa:

    Hi, fam. I'm a newbie investor and found a SubjectTo deal here in Texas. I'm super keen to dive into the deal (it'll be my first investment deal), however, I've never done this before. 

    Is there anything I need to be aware of in this deal? 
    Should I use my real estate agent on this deal, even though I found it? It may be worth having him along for the ride to make sure it's a clean deal.

    Should I consult with an attorney?

    Do I still get an inspection period in SubTo deals?

    How much earnest money should I commit to?

    If the loan is an FHA loan, am I meant to move into the home?

    So many questions lol. Any help is appreciated, cheers.

    -AJ

    Buy using Subject To and sell on Lease Option which I explain at 

    https://www.biggerpockets.com/forums/311/topics/1141313-subj...

    If you understand the requirements, it keeps you legal and out of trouble. 

    .

  • Wholesaler 路 Orange County 路 Member since 2022 路 31 posts 路 29 votes
    2y

    I will buy it off you LOL. This is my main business module at the moment. I have two subject to closings next week, one is an FHA in OK the other a VA in AZ. Also Have locked up 3 others this week, all subject to! Send me a message, I am more than happy to walk you through the transaction and answer any questions.

    To answer the few you asked...

    1. A good attorney that has done these before yes, an attorney not familiar with them no. 

    2. Yes, if the contract says so. It is no different then a cash deal in terms of terms with emd, option, inspection. 

    3.I usually start at 1k if I am working with an agent and go up to 1% of purchase price if needed, if direct to seller you can start at $100 and if they question it you can tell them you do volume and prefer not to have 20k out in EMD with all your deals at once so you start low

    4. No, it does not matter 

  • Investor 路 Austin, TX 路 Member since 2021 路 9k+ posts 路 5k+ votes
    2y

    Do not close the deal if you don鈥檛 know what you鈥檙e doing. That is a huge risk for you and the seller to take on. I have closed many subject to deals in Killeen and I鈥檓 happy to help if you need it.

  • Attorney 路 Austin, TX 路 Member since 2014 路 888 posts 路 759 votes
    2y

    Buy sub-2 and then what?

    Many sellers, desperate to get out of the house/loan, will thank you today. But in 3-5 years, after you make on-time payments and their credit is improved because of it, they will want to buy another house. The loan on the one they sold you will still show up and underwriters won't let them with the DTI ratios. Now they will try to pressure you into refinancing by messing with your relationship with their lender.

    If none of that happens, but there's an insured loss, making a claim will be challenging. Even with a PoA, underwriters and banks can throw up hurdles requiring the seller's cooperation.

    If, after reading all that and others' posts, you are still interested, I can walk you through the process if you need it.

  • Jay HurstBusiness Member
    Lender 路 Dallas, TX 路 Member since 2017 路 1k+ posts 路 1k+ votes
    2y
    Quote from @Jerel Ehlert:

    Buy sub-2 and then what?

    Many sellers, desperate to get out of the house/loan, will thank you today. But in 3-5 years, after you make on-time payments and their credit is improved because of it, they will want to buy another house. The loan on the one they sold you will still show up and underwriters won't let them with the DTI ratios. Now they will try to pressure you into refinancing by messing with your relationship with their lender.

    If none of that happens, but there's an insured loss, making a claim will be challenging. Even with a PoA, underwriters and banks can throw up hurdles requiring the seller's cooperation.

    If, after reading all that and others' posts, you are still interested, I can walk you through the process if you need it.


     There are going to be some enterprising attorney's making a LOT of money (especially in Texas with its very strong homestead protections) making a lot of money off the Pace Morby/guru boom in a few years. 

    Hurst Real Estate, INC4.989 Reviews
  • Wholesaler 路 Orange County 路 Member since 2022 路 31 posts 路 29 votes
    2y
    Quote from @Jerel Ehlert:

    Buy sub-2 and then what?

    Many sellers, desperate to get out of the house/loan, will thank you today. But in 3-5 years, after you make on-time payments and their credit is improved because of it, they will want to buy another house. The loan on the one they sold you will still show up and underwriters won't let them with the DTI ratios. Now they will try to pressure you into refinancing by messing with your relationship with their lender.

    If none of that happens, but there's an insured loss, making a claim will be challenging. Even with a PoA, underwriters and banks can throw up hurdles requiring the seller's cooperation.

    If, after reading all that and others' posts, you are still interested, I can walk you through the process if you need it.


    Hey Jerel, Very great insight and valid points to mention. One thing I wanted to mention is the existing mortgage can actually be wiped 100% off of the sellers DTI if you use a 3rd party servicing company that can show proof another entity is responsible for those payments. Usually we can wipe off 75% in 3 months and 100% in 12 months by doing so. The DTI is really only a concern in the short term but even then we can still get around it with lease agreements or working with one of my lenders who offers conventional loans with 3% down

  • Jay HurstBusiness Member
    Lender 路 Dallas, TX 路 Member since 2017 路 1k+ posts 路 1k+ votes
    2y
    Quote from @Jack Lander:
    Quote from @Jerel Ehlert:

    Buy sub-2 and then what?

    Many sellers, desperate to get out of the house/loan, will thank you today. But in 3-5 years, after you make on-time payments and their credit is improved because of it, they will want to buy another house. The loan on the one they sold you will still show up and underwriters won't let them with the DTI ratios. Now they will try to pressure you into refinancing by messing with your relationship with their lender.

    If none of that happens, but there's an insured loss, making a claim will be challenging. Even with a PoA, underwriters and banks can throw up hurdles requiring the seller's cooperation.

    If, after reading all that and others' posts, you are still interested, I can walk you through the process if you need it.


    Hey Jerel, Very great insight and valid points to mention. One thing I wanted to mention is the existing mortgage can actually be wiped 100% off of the sellers DTI if you use a 3rd party servicing company that can show proof another entity is responsible for those payments. Usually we can wipe off 75% in 3 months and 100% in 12 months by doing so. The DTI is really only a concern in the short term but even then we can still get around it with lease agreements or working with one of my lenders who offers conventional loans with 3% down


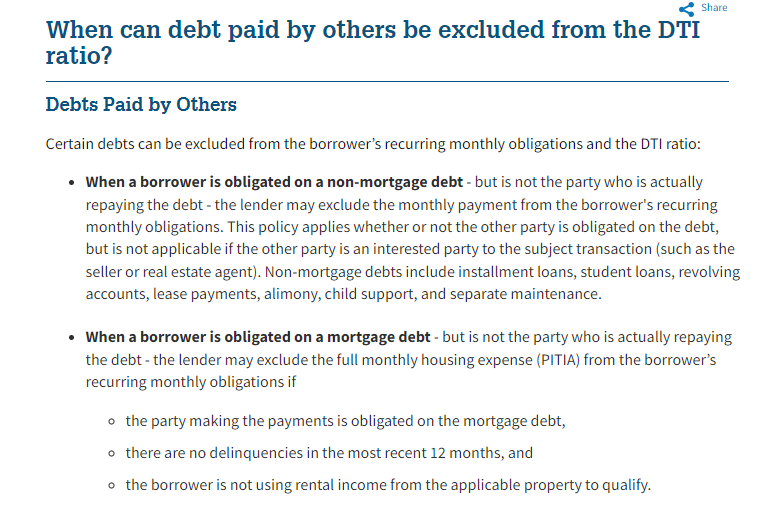
     That is correct when the debt is non-mortgage but when it is a mortgage the party paying the mortgage for 12 months has to also be obligated on the debt. A third part servicer does nothing to change this. 

    https://selling-guide.fanniemae.com/Underwriting-Borrowers/L...

    Hurst Real Estate, INC4.989 Reviews
  • Investor 路 Scottsdale Austin Tuktoyaktuk 路 Member since 2021 路 4k+ posts 路 4k+ votes
    2y
    Quote from @Jay Hurst:
    Quote from @Jack Lander:
    Quote from @Jerel Ehlert:

    Buy sub-2 and then what?

    Many sellers, desperate to get out of the house/loan, will thank you today. But in 3-5 years, after you make on-time payments and their credit is improved because of it, they will want to buy another house. The loan on the one they sold you will still show up and underwriters won't let them with the DTI ratios. Now they will try to pressure you into refinancing by messing with your relationship with their lender.

    If none of that happens, but there's an insured loss, making a claim will be challenging. Even with a PoA, underwriters and banks can throw up hurdles requiring the seller's cooperation.

    If, after reading all that and others' posts, you are still interested, I can walk you through the process if you need it.


    Hey Jerel, Very great insight and valid points to mention. One thing I wanted to mention is the existing mortgage can actually be wiped 100% off of the sellers DTI if you use a 3rd party servicing company that can show proof another entity is responsible for those payments. Usually we can wipe off 75% in 3 months and 100% in 12 months by doing so. The DTI is really only a concern in the short term but even then we can still get around it with lease agreements or working with one of my lenders who offers conventional loans with 3% down


     That is correct when the debt is non-mortgage but when it is a mortgage the party paying the mortgage for 12 months has to also be obligated on the debt. A third part servicer does nothing to change this. 

    https://selling-guide.fanniemae.com/Underwriting-Borrowers/L...

    That's for Fannie Mae underwriting of course. But, there are plenty of other soures of lending that don't follow Fannie rules. 
  • Jay HurstBusiness Member
    Lender 路 Dallas, TX 路 Member since 2017 路 1k+ posts 路 1k+ votes
    2y
    Quote from @Account Closed:
    Quote from @Jay Hurst:
    Quote from @Jack Lander:
    Quote from @Jerel Ehlert:

    Buy sub-2 and then what?

    Many sellers, desperate to get out of the house/loan, will thank you today. But in 3-5 years, after you make on-time payments and their credit is improved because of it, they will want to buy another house. The loan on the one they sold you will still show up and underwriters won't let them with the DTI ratios. Now they will try to pressure you into refinancing by messing with your relationship with their lender.

    If none of that happens, but there's an insured loss, making a claim will be challenging. Even with a PoA, underwriters and banks can throw up hurdles requiring the seller's cooperation.

    If, after reading all that and others' posts, you are still interested, I can walk you through the process if you need it.


    Hey Jerel, Very great insight and valid points to mention. One thing I wanted to mention is the existing mortgage can actually be wiped 100% off of the sellers DTI if you use a 3rd party servicing company that can show proof another entity is responsible for those payments. Usually we can wipe off 75% in 3 months and 100% in 12 months by doing so. The DTI is really only a concern in the short term but even then we can still get around it with lease agreements or working with one of my lenders who offers conventional loans with 3% down


     That is correct when the debt is non-mortgage but when it is a mortgage the party paying the mortgage for 12 months has to also be obligated on the debt. A third part servicer does nothing to change this. 

    https://selling-guide.fanniemae.com/Underwriting-Borrowers/L...

    That's for Fannie Mae underwriting of course. But, there are plenty of other soures of lending that don't follow Fannie rules. 

     The post I answered references conventional loans. 

    Hurst Real Estate, INC4.989 Reviews
  • Investor 路 Austin, TX 路 Member since 2023 路 12 posts 路 9 votes
    2y

    Thanks for all the great feedback, everyone! You all mentioned a lot of blind spots I had. Much appreciated! I鈥檒l keep you all posted and hopefully come back with more questions. Thank you! 馃檹馃徑 

  • Michael GonzalesBusiness Member
    Real Estate Agent 路 San Antonio 路 Member since 2018 路 23 posts 路 10 votes
    2y

    AJ! I love that you posted this. Sub To was my introduction into RE investing and boy, was it stressful - but I learned a ton. Connecting with you for more details - by no means am I an expert, but I have been around the proverbial block. 

Join the conversationCreate a free account to reply, vote on answers and follow this thread.