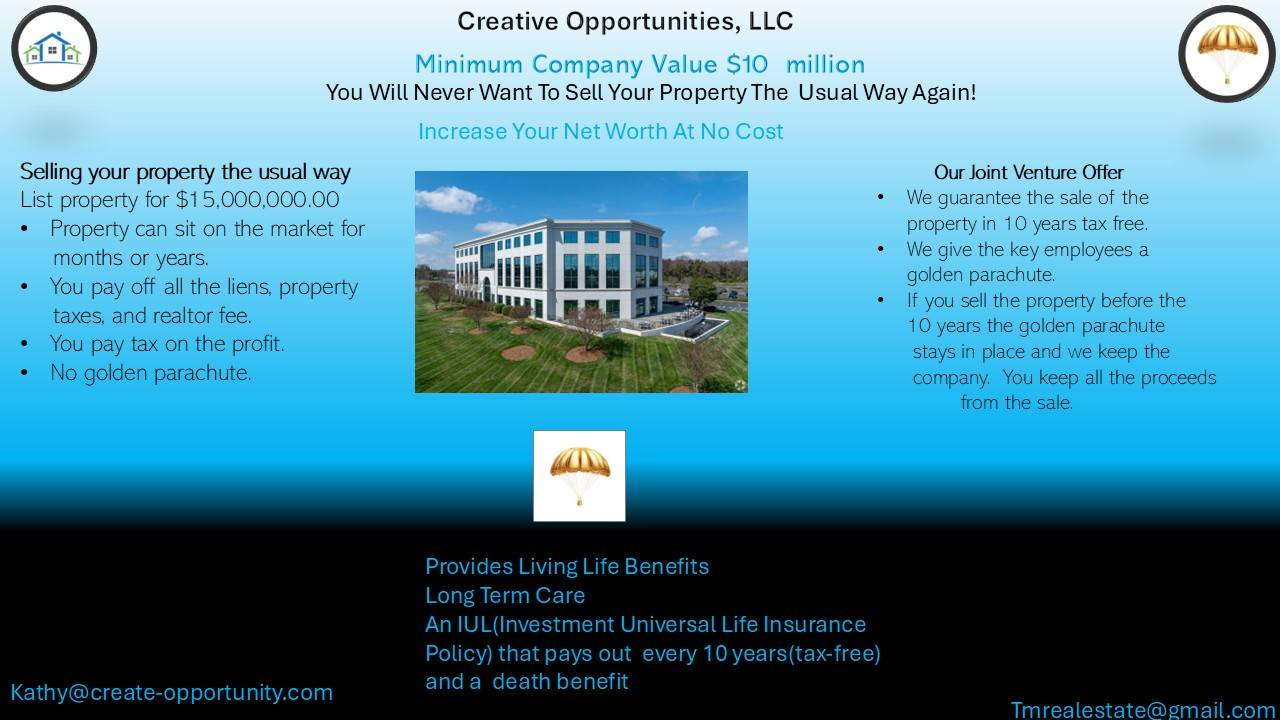
Hi Kathy, interesting concept. I see a lot of creative structures in Florida, so I have a few questions to understand this better.
When you say you guarantee the sale of the property in 10 years tax free, who is guaranteeing that? Is that a written guarantee from a buyer, or is that based on the IUL policy performance?
And during those 10 years, who holds title to the property? Who is responsible for the mortgage, taxes, insurance, and maintenance if the property needs work?
Last one — if the owner needs to sell before year 10 for a family emergency or health reason, what happens? Does he lose the golden parachute, or can he still get out?
I ask because most sellers I work with care about two things: control and being able to get out if life happens. Trying to understand how this structure handles that.
Question One- Based on policy performance-It also pays out every 10 years
Question Two-The current owner will hold title. The current owner is also responsible for all necessary created expenses already on the property as they are now.
Question Three-In the right column I answered this.
This actually works for both buyers and sellers. But this is designed for sellers in this layout. We disclose if they need to sell the property they can. The ability to use the asset to create additional collateral is what is key. As then once the policy is created from using the asset there is a loan performed on the newly created asset the IUL not the property. So it's one of those create and forget til maturity. It has the ability for people who already own their property to create additional collateral that can pay off a mortgage in 10 years vs 30. Basically once someone puchases an asset currently they are taking on a liability this is asset creation that offsets that liability.