Using the BRRRR Method on Oceanfront Condos — Anyone Else Doing This Near the Coast?
Hey everyone,
I’m Brandon from Myrtle Beach, South Carolina. I work primarily with investors focused on short-term rental–friendly oceanfront properties, and something interesting has been happening here:
Many of my clients are applying a modified BRRRR strategy to dated oceanfront condos — essentially:
Buy older, underpriced units in established resorts → Renovate to STR-grade finishes → Rent on Airbnb/VRBO → Refinance after 12–18 months based on new income comps → Repeat with equity pull-out capital.
Even though condos can be trickier with financing and HOA dynamics, the math has worked surprisingly well when:
-
The HOA allows STR operations.
-
Renovations target higher ADR and occupancy.
-
The appraisal reflects short-term rental income rather than long-term leases.
I’ve noticed this approach works best when you treat each condo almost like a “micro–multifamily” — tracking cash flow, management efficiency, and appreciation just like you would for a small apartment deal.
Curious — has anyone else here applied the BRRRR method to condos or coastal properties instead of single-family or multifamily units?
How have your refinance experiences, appraisal values, or lender feedback compared to traditional BRRRR projects?
Would love to trade notes on what’s working (and what’s not) in different coastal or vacation markets.
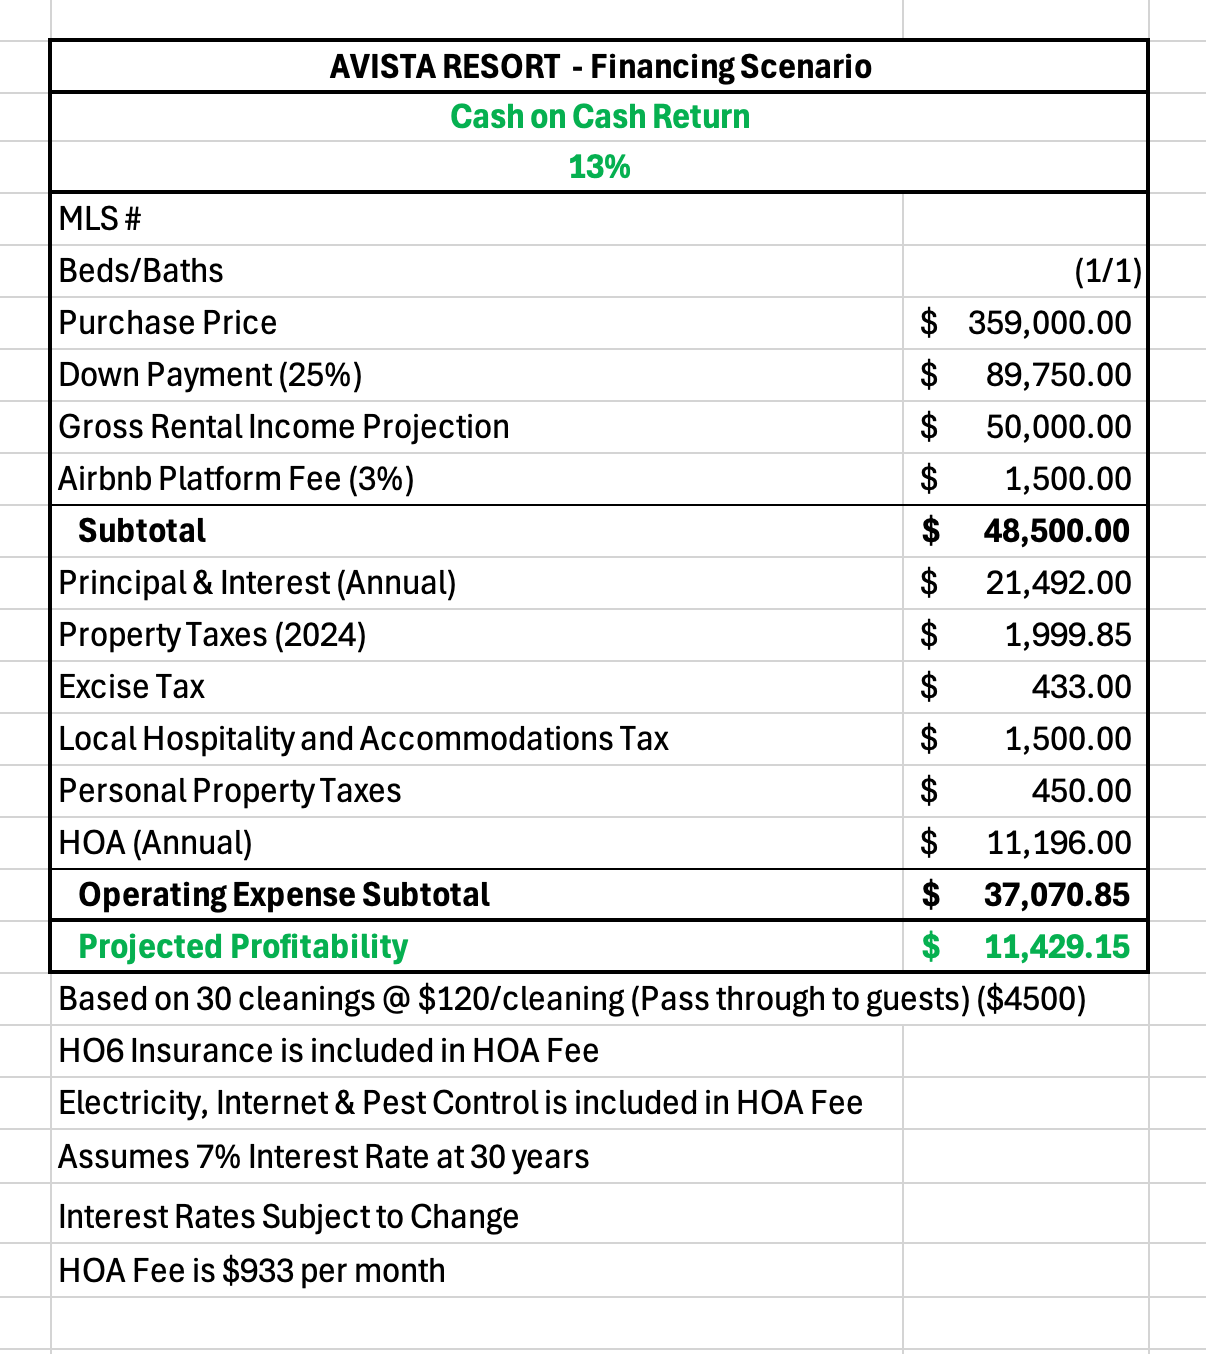
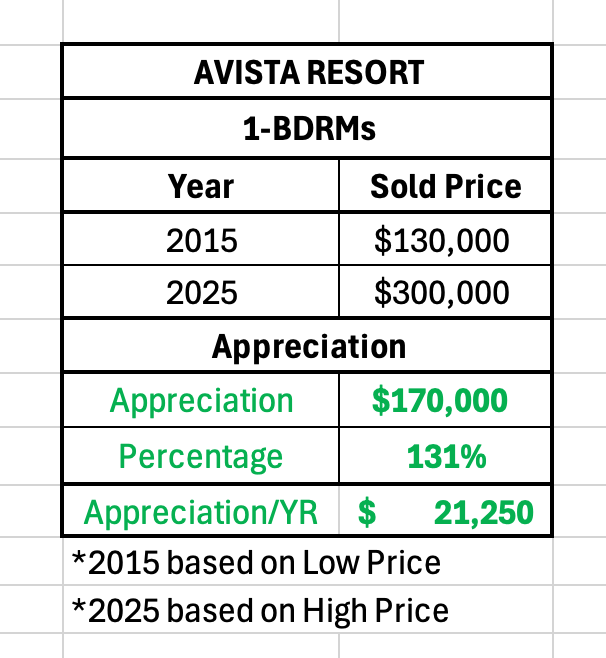
HERE'S THE MATH ON THE SHORT TERM RENTAL BUSINESS FOR A 1-BEDROOM OCEANFRONT CONDO:
Disclaimer: All information given is meant to be educational. I am only
passing on historical information shared with me by owners, rental
companies, and various publications. I am not guaranteeing these
numbers, nor can I guarantee future rentals or appreciation. This
information is not intended to replace your own research, or to provide
legal, investment, or financial advice. Please consult an attorney for
legal advice.
— Brandon

