A Very Succinct Outline for Legally Raising Capital

A Very Succinct Outline for Legally Raising Capital

Don KonipolBusiness Member
Investor · The Woodlands TX / Avon, CT · Member since 2009 · 6k+ posts · 10k+ votes

There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 

Private Mortgage Financing Partners, LLC
1Reply
19 views

Most Popular Reply

Chris SeveneyBusiness Member
Moderator
Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
1y
Quote from @Don Konipol:
Quote from @Robert Ellis:
Quote from @Don Konipol:

There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 


 Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 

I’m no expert in Reg A, so my help with it will be limited.  Historically Reg A was a way for small companies to raise capital in a small PUBLIC offering, with the available use of general solicitation and advertising, often or hopefully leading to having a trading market in their securities.  A few things happened in 2015.  First and foremost with Reg D 506 c established  with the use of general solicitation and advertising eliminating the necessity of going the Reg A route in order to advertise your offering or to not be under the restrictions of a private offering.  So essentially Reg D 506 c is a hybrid between a private and a public offering.  Reg A is a non registered PUBLIC offering.  In 2015 the amount that could be raised was greatly increased and two “tiers” created - up to $20 million and up to $75 million.  As a public offering the sponsor is responsible for compliance with many SEC requirements that a private offering under Reg D is not, especially as it relates to reporting financial and other information on a periodic basis with the SEC, providing investors with financial statements, adherence to investor control in electing board of directors, etc.   However, Reg A offerings are not restricted to accredited investors as are Reg D offerings.

I’m not sure that Reg A is any more likely to attract “big” capital than Reg D is. I believe @Chris Seveney has successfully completed a Reg A offering.  Perhaps he can describe his experience and better answer your question.  


 Yep we have done a regulation A offering (Getting ready for our next one now). There is also Reg CF. If raising $5M or less Reg CF is the way to go, with Reg A you can raise up to $75M per year (not sure any real estate firm has ever done that with a Reg A). Reg A will easily cost you $100k to get it setup and then the question becomes do you do it on your own or bring in a Broker-Dealer, Escrow Company, Technology Company, Transfer Agent and other players or do it yourself.If you are doing a Reg A do not expect it to be like a 506c where you can do it with one or two people - you are gonna need a team. Also you have to have SEC compliant audited financials. That could cost you another $50-$100k between the firm who does the audit and if you have someone who could do it in house or use a third party.

I would not do a Reg A for a single deal, I would recommend it for an evergreen fund. 

Last thingI will mention, we have 800+ investors (I believe or close to that) - your accredited investors will be the bulk of the money. 

7e investments53 Reviews
See this reply in the discussion

7 Replies

Jump to latestLatest
  • Robert EllisBusiness Member
    Developer · Miami, FL · Member since 2014 · 3k+ posts · 1k+ votes
    1y
    Quote from @Don Konipol:

    There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

    1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
    2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

    3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

    4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
    The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
    As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

    I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 


     Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 

    • Real Estate Broker · Cleveland Dayton Cincinnati Toledo Columbus & Akron, OH · Member since 2013 · 30k+ posts · 20k+ votes
      1y
      Quote from @Robert Ellis:
      Quote from @Don Konipol:

      There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

      1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
      2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

      3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

      4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
      The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
      As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

      I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 
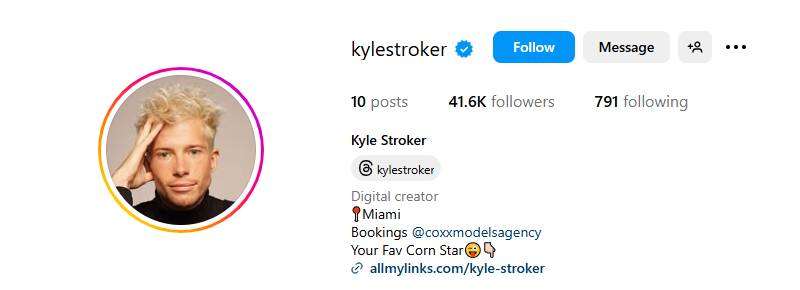

       Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 


       Rob, 

      If you want to raise investor funds, the 1st thing you're going to need to do is stop using fake identities. Can you explain who Kyle Stroker is? Who is real, Robert Ellis or Kyle Stroker? What's the deal here man?

      ___

    • Don KonipolBusiness Member
      OP
      Investor · The Woodlands TX / Avon, CT · Member since 2009 · 6k+ posts · 10k+ votes
      1y
      Quote from @Robert Ellis:
      Quote from @Don Konipol:

      There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

      1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
      2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

      3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

      4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
      The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
      As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

      I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 


       Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 

      I’m no expert in Reg A, so my help with it will be limited.  Historically Reg A was a way for small companies to raise capital in a small PUBLIC offering, with the available use of general solicitation and advertising, often or hopefully leading to having a trading market in their securities.  A few things happened in 2015.  First and foremost with Reg D 506 c established  with the use of general solicitation and advertising eliminating the necessity of going the Reg A route in order to advertise your offering or to not be under the restrictions of a private offering.  So essentially Reg D 506 c is a hybrid between a private and a public offering.  Reg A is a non registered PUBLIC offering.  In 2015 the amount that could be raised was greatly increased and two “tiers” created - up to $20 million and up to $75 million.  As a public offering the sponsor is responsible for compliance with many SEC requirements that a private offering under Reg D is not, especially as it relates to reporting financial and other information on a periodic basis with the SEC, providing investors with financial statements, adherence to investor control in electing board of directors, etc.   However, Reg A offerings are not restricted to accredited investors as are Reg D offerings.

      I’m not sure that Reg A is any more likely to attract “big” capital than Reg D is. I believe @Chris Seveney has successfully completed a Reg A offering.  Perhaps he can describe his experience and better answer your question.  

      Private Mortgage Financing Partners, LLC
    • Chris SeveneyBusiness Member
      Moderator
      Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
      1y
      Quote from @Don Konipol:
      Quote from @Robert Ellis:
      Quote from @Don Konipol:

      There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

      1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
      2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

      3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

      4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
      The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
      As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

      I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 


       Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 

      I’m no expert in Reg A, so my help with it will be limited.  Historically Reg A was a way for small companies to raise capital in a small PUBLIC offering, with the available use of general solicitation and advertising, often or hopefully leading to having a trading market in their securities.  A few things happened in 2015.  First and foremost with Reg D 506 c established  with the use of general solicitation and advertising eliminating the necessity of going the Reg A route in order to advertise your offering or to not be under the restrictions of a private offering.  So essentially Reg D 506 c is a hybrid between a private and a public offering.  Reg A is a non registered PUBLIC offering.  In 2015 the amount that could be raised was greatly increased and two “tiers” created - up to $20 million and up to $75 million.  As a public offering the sponsor is responsible for compliance with many SEC requirements that a private offering under Reg D is not, especially as it relates to reporting financial and other information on a periodic basis with the SEC, providing investors with financial statements, adherence to investor control in electing board of directors, etc.   However, Reg A offerings are not restricted to accredited investors as are Reg D offerings.

      I’m not sure that Reg A is any more likely to attract “big” capital than Reg D is. I believe @Chris Seveney has successfully completed a Reg A offering.  Perhaps he can describe his experience and better answer your question.  


       Yep we have done a regulation A offering (Getting ready for our next one now). There is also Reg CF. If raising $5M or less Reg CF is the way to go, with Reg A you can raise up to $75M per year (not sure any real estate firm has ever done that with a Reg A). Reg A will easily cost you $100k to get it setup and then the question becomes do you do it on your own or bring in a Broker-Dealer, Escrow Company, Technology Company, Transfer Agent and other players or do it yourself.If you are doing a Reg A do not expect it to be like a 506c where you can do it with one or two people - you are gonna need a team. Also you have to have SEC compliant audited financials. That could cost you another $50-$100k between the firm who does the audit and if you have someone who could do it in house or use a third party.

      I would not do a Reg A for a single deal, I would recommend it for an evergreen fund. 

      Last thingI will mention, we have 800+ investors (I believe or close to that) - your accredited investors will be the bulk of the money. 

      7e investments53 Reviews
    • Robert EllisBusiness Member
      Developer · Miami, FL · Member since 2014 · 3k+ posts · 1k+ votes
      1y
      Quote from @Chris Seveney:
      Quote from @Don Konipol:
      Quote from @Robert Ellis:
      Quote from @Don Konipol:

      There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

      1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
      2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

      3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

      4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
      The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
      As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

      I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 


       Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 

      I’m no expert in Reg A, so my help with it will be limited.  Historically Reg A was a way for small companies to raise capital in a small PUBLIC offering, with the available use of general solicitation and advertising, often or hopefully leading to having a trading market in their securities.  A few things happened in 2015.  First and foremost with Reg D 506 c established  with the use of general solicitation and advertising eliminating the necessity of going the Reg A route in order to advertise your offering or to not be under the restrictions of a private offering.  So essentially Reg D 506 c is a hybrid between a private and a public offering.  Reg A is a non registered PUBLIC offering.  In 2015 the amount that could be raised was greatly increased and two “tiers” created - up to $20 million and up to $75 million.  As a public offering the sponsor is responsible for compliance with many SEC requirements that a private offering under Reg D is not, especially as it relates to reporting financial and other information on a periodic basis with the SEC, providing investors with financial statements, adherence to investor control in electing board of directors, etc.   However, Reg A offerings are not restricted to accredited investors as are Reg D offerings.

      I’m not sure that Reg A is any more likely to attract “big” capital than Reg D is. I believe @Chris Seveney has successfully completed a Reg A offering.  Perhaps he can describe his experience and better answer your question.  


       Yep we have done a regulation A offering (Getting ready for our next one now). There is also Reg CF. If raising $5M or less Reg CF is the way to go, with Reg A you can raise up to $75M per year (not sure any real estate firm has ever done that with a Reg A). Reg A will easily cost you $100k to get it setup and then the question becomes do you do it on your own or bring in a Broker-Dealer, Escrow Company, Technology Company, Transfer Agent and other players or do it yourself.If you are doing a Reg A do not expect it to be like a 506c where you can do it with one or two people - you are gonna need a team. Also you have to have SEC compliant audited financials. That could cost you another $50-$100k between the firm who does the audit and if you have someone who could do it in house or use a third party.

      I would not do a Reg A for a single deal, I would recommend it for an evergreen fund. 

      Last thingI will mention, we have 800+ investors (I believe or close to that) - your accredited investors will be the bulk of the money. 

       from what I've seen 506c is how blackcstone even raises their capital. we would have an open ended evergreen fund I believe on the equity side that could push each subdivision development into a sub reit. I have to talk to a securities attorney. our land for a subdivision is 20-30k per acre in our market in columbus so a 50-100 acre tract of land is 1 million to 5 million. we'd need 3 total because we don't want to work with accredited investors unless we have to and the institutions I talk to want checks at 5 million and up so we would subdivide close end funds by markets / metros. Columbus for example would be 3 subdivisions, the ones the institution decide to keep or close on get assigned to the subentity for that market and if they are sold to a builder they'd be closed in a double close, if the fund closes them it would be in the subreit. each subreit would allow us to have development values of 500-1000 housing units and each subdivision approx 100 million so up to 300 million per subreit depending if the institution wants to sell the land or build all the houses or do a combination of both. with larger land tracts we can also subdivide into a planned development and have smaller tracts of land carved out for build to rent, apartments, retail, or other uses so we aren't just going to put in subdivisions. most complaints by municipalities deal with wanting mixed use development patterns. this is nothing compared to the urban stuff we have to do. I think in this structure it would be all 506 c offerings and you are right. we expect each sub fund to be closed and an open ended evergreen fund above that basically acts as a land bank and sells to sub entities post entitlement or that we hold our own holdigns in from the land gains we generate and those can be used as collateral. this is just the structure that allows us to entitle 1000-2000 horizontal lots per years at national scale. 

    • Don KonipolBusiness Member
      OP
      Investor · The Woodlands TX / Avon, CT · Member since 2009 · 6k+ posts · 10k+ votes
      1y
      Quote from @Robert Ellis:
      Quote from @Chris Seveney:
      Quote from @Don Konipol:
      Quote from @Robert Ellis:
      Quote from @Don Konipol:

      There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

      1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
      2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

      3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

      4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
      The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
      As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

      I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 


       Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 

      I’m no expert in Reg A, so my help with it will be limited.  Historically Reg A was a way for small companies to raise capital in a small PUBLIC offering, with the available use of general solicitation and advertising, often or hopefully leading to having a trading market in their securities.  A few things happened in 2015.  First and foremost with Reg D 506 c established  with the use of general solicitation and advertising eliminating the necessity of going the Reg A route in order to advertise your offering or to not be under the restrictions of a private offering.  So essentially Reg D 506 c is a hybrid between a private and a public offering.  Reg A is a non registered PUBLIC offering.  In 2015 the amount that could be raised was greatly increased and two “tiers” created - up to $20 million and up to $75 million.  As a public offering the sponsor is responsible for compliance with many SEC requirements that a private offering under Reg D is not, especially as it relates to reporting financial and other information on a periodic basis with the SEC, providing investors with financial statements, adherence to investor control in electing board of directors, etc.   However, Reg A offerings are not restricted to accredited investors as are Reg D offerings.

      I’m not sure that Reg A is any more likely to attract “big” capital than Reg D is. I believe @Chris Seveney has successfully completed a Reg A offering.  Perhaps he can describe his experience and better answer your question.  


       Yep we have done a regulation A offering (Getting ready for our next one now). There is also Reg CF. If raising $5M or less Reg CF is the way to go, with Reg A you can raise up to $75M per year (not sure any real estate firm has ever done that with a Reg A). Reg A will easily cost you $100k to get it setup and then the question becomes do you do it on your own or bring in a Broker-Dealer, Escrow Company, Technology Company, Transfer Agent and other players or do it yourself.If you are doing a Reg A do not expect it to be like a 506c where you can do it with one or two people - you are gonna need a team. Also you have to have SEC compliant audited financials. That could cost you another $50-$100k between the firm who does the audit and if you have someone who could do it in house or use a third party.

      I would not do a Reg A for a single deal, I would recommend it for an evergreen fund. 

      Last thingI will mention, we have 800+ investors (I believe or close to that) - your accredited investors will be the bulk of the money. 

       from what I've seen 506c is how blackcstone even raises their capital. we would have an open ended evergreen fund I believe on the equity side that could push each subdivision development into a sub reit. I have to talk to a securities attorney. our land for a subdivision is 20-30k per acre in our market in columbus so a 50-100 acre tract of land is 1 million to 5 million. we'd need 3 total because we don't want to work with accredited investors unless we have to and the institutions I talk to want checks at 5 million and up so we would subdivide close end funds by markets / metros. Columbus for example would be 3 subdivisions, the ones the institution decide to keep or close on get assigned to the subentity for that market and if they are sold to a builder they'd be closed in a double close, if the fund closes them it would be in the subreit. each subreit would allow us to have development values of 500-1000 housing units and each subdivision approx 100 million so up to 300 million per subreit depending if the institution wants to sell the land or build all the houses or do a combination of both. with larger land tracts we can also subdivide into a planned development and have smaller tracts of land carved out for build to rent, apartments, retail, or other uses so we aren't just going to put in subdivisions. most complaints by municipalities deal with wanting mixed use development patterns. this is nothing compared to the urban stuff we have to do. I think in this structure it would be all 506 c offerings and you are right. we expect each sub fund to be closed and an open ended evergreen fund above that basically acts as a land bank and sells to sub entities post entitlement or that we hold our own holdigns in from the land gains we generate and those can be used as collateral. this is just the structure that allows us to entitle 1000-2000 horizontal lots per years at national scale. 

      I wish you good luck with your plans.  I wouldn’t be of any help other than what I already offered because I have rarely (only twice) done development and both were small commercial deals.  You’re talking about a bigger arena than I play in…
      Private Mortgage Financing Partners, LLC
    • Chris SeveneyBusiness Member
      Moderator
      Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
      1y
      Quote from @Robert Ellis:
      Quote from @Chris Seveney:
      Quote from @Don Konipol:
      Quote from @Robert Ellis:
      Quote from @Don Konipol:

      There’s lots of confusion, incorrect information, and false assumptions being made about the legality of raising capital for investment.  So here is a very short, quick outline of the legal process in the U.S.A.

      1. Any capital raised for investment purposes, in which one or more parties is NOT active in the management of the investment entity, is a securities offering.  
      2. All securities offering must be REGISTERED with the Securities and Exchange Commission, unless the offering is covered under an exemption from registration.

      3. There are three primary exemptions from SEC registration.  The exemption for intra state offerings (the offer is made to investors residing in a single state), the exemption for investors with FEDERAL accreditation (Federal banks, investment banks of a certain size, Federal funds dealers, etc) and the private placement exemption.  Since single state offerings are very limiting, and many states require state registration and compliance with inherent costs, the private placement exemption remains the most popular. 

      4. There are two methods of “private placement”. The old traditional one was the general exemption for private placement.  The sponsor, with the help of a securities attorney, determines that the offering meets the (often ambiguous) requirements for determination of private placement and proceeds with the offering.  The advantageous of this type of offering is simplicity, cost, and speed. 
      The second method of private placement, is compliance with the SEC “safe harbor” Reg D.  Sec 504, 505, or 506 b or c.  This will necessitate the production of a Private Placement Memorandum (PPM), Operating Agreement, and Subscription Agreement.  Current cost are $8,000 to $15,000 for legal fees, inclusive of Form D filing with SEC and notification filing for the states the initial investors reside in.  The advantages of the Reg D are (1) if the sponsor complies with the Reg D requirements, the offering as to it being a private placement will NEVER be challenged by the SEC.  Further, if disgruntled investors sue, the sponsor has a “definitive defense” as well as a “statutory defense” in a lawsuit. This means that by merely complying with the Reg D requirements, the sponsor should have enough of a defense to beat any lawsuit.  I can tell you from personal experience that a small few investors will consider suing EVEN IF THEY MADE MONEY; and that no attorney will take their case (at least not on contingency) if the sponsor complied with Reg D, absence fraud.  
      As important, all sophisticated investors will only consider investment in private offerings that are Reg D, or occasionally Reg A, compliant.  The most important aspect of Reg D is the 506 c offering, which ALLOWS general solicitation and advertising, and eliminates the requirement of the sponsor and investor having an established relationship. 

      I’d be happy to answer any questions or provide any clarifications; and encourage comments of any kind. 


       Could you do more of deep dive into Reg A offering and 506 C and when you should do each one? We are doing single development offerings in SPVs through a 506 C offering for projects that are ground up like in Columbus Ohio but for larger deals in Miami Florida where an acre of land can be 100 million dollars in an unlimited height district you really need to be raising from institutions and the largest publicly or privately held companies in the country. We've also looked at subdivision funds that would purchase and develop a subdivision and take it all the way to completion with project sizes approximately 25-30 million in construction, land, and entitlements with exits around 50 million but I wanted to know which structure is best used. these are two very different markets. one we could be fine with check sizes 50k-500k, the other one we would need minimum checks of 3 million and up. it could be a 7-8 year development with a billion dollar sell out if your building is as big as those that are 1-2 million square feet in Miami. thanks for posting hope this isn't too much to ask. 

      I’m no expert in Reg A, so my help with it will be limited.  Historically Reg A was a way for small companies to raise capital in a small PUBLIC offering, with the available use of general solicitation and advertising, often or hopefully leading to having a trading market in their securities.  A few things happened in 2015.  First and foremost with Reg D 506 c established  with the use of general solicitation and advertising eliminating the necessity of going the Reg A route in order to advertise your offering or to not be under the restrictions of a private offering.  So essentially Reg D 506 c is a hybrid between a private and a public offering.  Reg A is a non registered PUBLIC offering.  In 2015 the amount that could be raised was greatly increased and two “tiers” created - up to $20 million and up to $75 million.  As a public offering the sponsor is responsible for compliance with many SEC requirements that a private offering under Reg D is not, especially as it relates to reporting financial and other information on a periodic basis with the SEC, providing investors with financial statements, adherence to investor control in electing board of directors, etc.   However, Reg A offerings are not restricted to accredited investors as are Reg D offerings.

      I’m not sure that Reg A is any more likely to attract “big” capital than Reg D is. I believe @Chris Seveney has successfully completed a Reg A offering.  Perhaps he can describe his experience and better answer your question.  


       Yep we have done a regulation A offering (Getting ready for our next one now). There is also Reg CF. If raising $5M or less Reg CF is the way to go, with Reg A you can raise up to $75M per year (not sure any real estate firm has ever done that with a Reg A). Reg A will easily cost you $100k to get it setup and then the question becomes do you do it on your own or bring in a Broker-Dealer, Escrow Company, Technology Company, Transfer Agent and other players or do it yourself.If you are doing a Reg A do not expect it to be like a 506c where you can do it with one or two people - you are gonna need a team. Also you have to have SEC compliant audited financials. That could cost you another $50-$100k between the firm who does the audit and if you have someone who could do it in house or use a third party.

      I would not do a Reg A for a single deal, I would recommend it for an evergreen fund. 

      Last thingI will mention, we have 800+ investors (I believe or close to that) - your accredited investors will be the bulk of the money. 

       from what I've seen 506c is how blackcstone even raises their capital. we would have an open ended evergreen fund I believe on the equity side that could push each subdivision development into a sub reit. I have to talk to a securities attorney. our land for a subdivision is 20-30k per acre in our market in columbus so a 50-100 acre tract of land is 1 million to 5 million. we'd need 3 total because we don't want to work with accredited investors unless we have to and the institutions I talk to want checks at 5 million and up so we would subdivide close end funds by markets / metros. Columbus for example would be 3 subdivisions, the ones the institution decide to keep or close on get assigned to the subentity for that market and if they are sold to a builder they'd be closed in a double close, if the fund closes them it would be in the subreit. each subreit would allow us to have development values of 500-1000 housing units and each subdivision approx 100 million so up to 300 million per subreit depending if the institution wants to sell the land or build all the houses or do a combination of both. with larger land tracts we can also subdivide into a planned development and have smaller tracts of land carved out for build to rent, apartments, retail, or other uses so we aren't just going to put in subdivisions. most complaints by municipalities deal with wanting mixed use development patterns. this is nothing compared to the urban stuff we have to do. I think in this structure it would be all 506 c offerings and you are right. we expect each sub fund to be closed and an open ended evergreen fund above that basically acts as a land bank and sells to sub entities post entitlement or that we hold our own holdigns in from the land gains we generate and those can be used as collateral. this is just the structure that allows us to entitle 1000-2000 horizontal lots per years at national scale. 

      Once you start getting into REITs and subreits that is a completely different animal than just raising $3M. If you go into the REIT space you are going to need inhouse counsel, inhouse accounting and tax/compliance, a rockstar auditor and a complete investor relations team, transfer agent etc on the money raise side. It seems you went from wanting to raise $3M from one of your other posts to having a few hundred-million-dollar real estate company that would probably employ 30-50 employees.

      7e investments53 Reviews
Join the conversationCreate a free account to reply, vote on answers and follow this thread.