I'm looking for DSCR lenders that will allow me to rent an investment property, at the market rate, to two family members. I'm in Kent, WA, and looking at rental properties in Mount Vernon, WA, about 70 miles away. I've found one lender that allows it, but I'm looking for others so that I can compare. I also spoke to a Seattle-area broker about it, and he said that a lender won't ask about who's renting, so it really doesn't matter. However, I want to make sure that any lender is fully aware that I intend to rent to family and has no prohibition against it. Thanks in advance for any leads!
@Anthony Warnke thanks for the post here. The response above had me think about this a little bit. We have the same type of verbiage in our DSCR loans as well...but we have also had parents buy a rental property for their kid going to college. So, there is something to this.
Now, I went through every single page of all the disclosures you sign at closing - none of them define what "family" means. So, does my 2nd cousin, twice removed mean a family member? What about my adopted daughter that lives with me? What about my grandparents that don't live with me? Again, nothing in there that defines what "family" formally means. I'm including some screenshots below.
So, using the property for personal use - that is defined. You cannot occupy the property as a primary or secondary home for this particular loan (but some DSCR loans are ok with STR income). Household would also be a pretty specific piece of legal wording that would defined easily in court - this includes your spouse and dependents in 99% of the scenarios out there (so, the adopted daughter example above would fall in this category). But "family" could be a little open to interpretation. I'll leave it at that though. I also don't like the "the lender doesn't care who rents it" - because lenders do care. If your spouse and kids were to occupy that property because you are on a split - that would be a big deal. So, they do care who rents a property.
Anyways, hope this helps in some way. Here's the pictures I was telling you about:
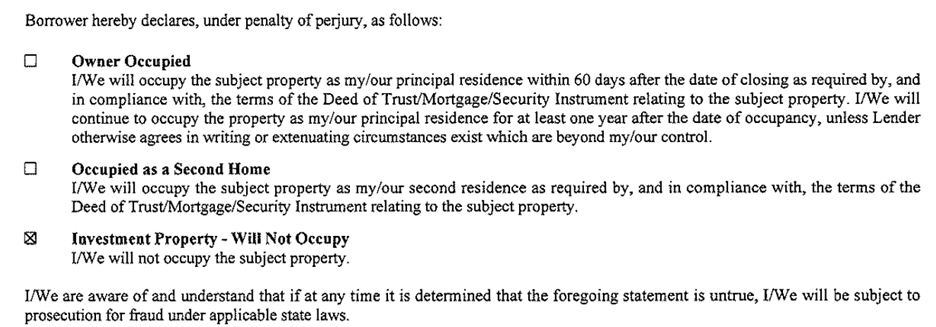
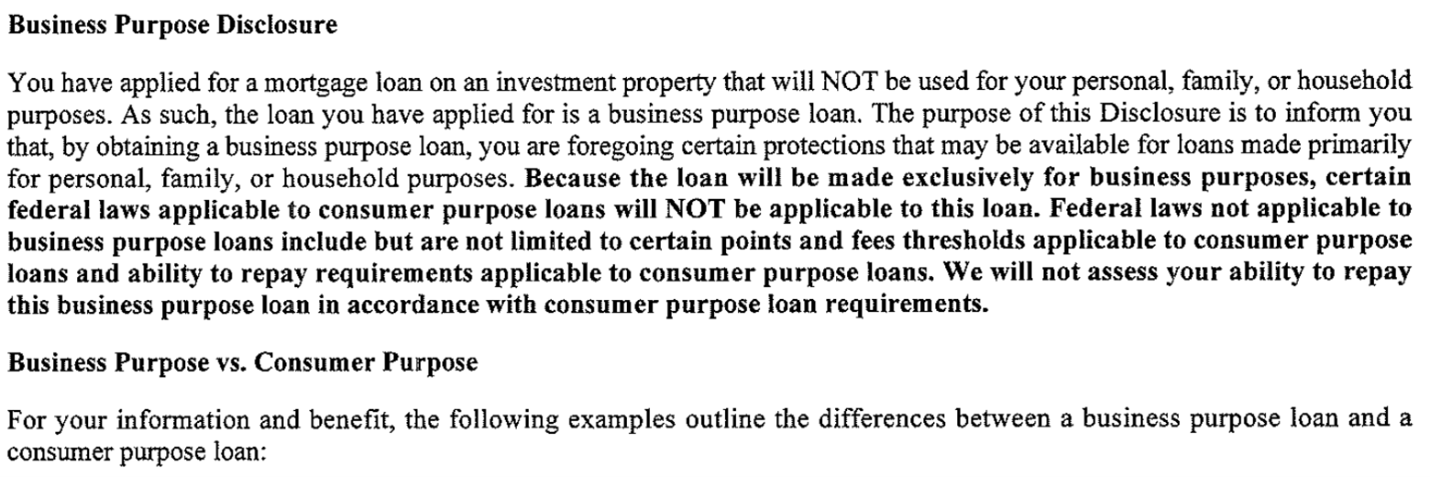
Very, very few lenders are going to allow this. Most will require you to sign a Buiness Purpose Loan statement indicating that you will only use the property for business purposes. Included in that statement are definitions which will include the borrower, any of the members of any entity involved, and their families as prohibited from using the property. The entire premise that allows DSCR loans in the first place relies on the fact that there is no "personsal, family, or household" use for the loan, which can get blurred when family members are living in the property.
If the broker tells you they "wont ask about who's renting" and you sign a statement to the effect above, youre committing mortgage fraud. If the lender finds out, they will immediately put the loan into default and send a demand notice.
Make sure the lender who is claiming they can do a loan in this scenarios can acutally do it.
@Anthony Warnke thanks for the post here. The response above had me think about this a little bit. We have the same type of verbiage in our DSCR loans as well...but we have also had parents buy a rental property for their kid going to college. So, there is something to this.
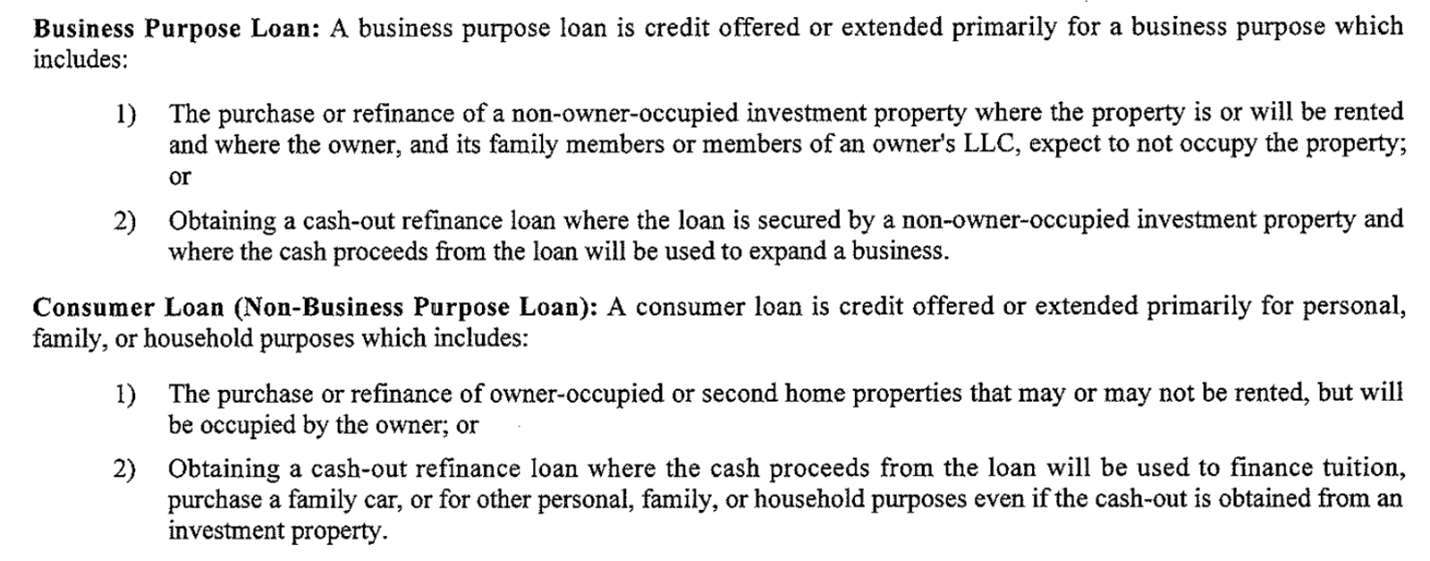
Now, I went through every single page of all the disclosures you sign at closing - none of them define what "family" means. So, does my 2nd cousin, twice removed mean a family member? What about my adopted daughter that lives with me? What about my grandparents that don't live with me? Again, nothing in there that defines what "family" formally means. I'm including some screenshots below.
So, using the property for personal use - that is defined. You cannot occupy the property as a primary or secondary home for this particular loan (but some DSCR loans are ok with STR income). Household would also be a pretty specific piece of legal wording that would defined easily in court - this includes your spouse and dependents in 99% of the scenarios out there (so, the adopted daughter example above would fall in this category). But "family" could be a little open to interpretation. I'll leave it at that though. I also don't like the "the lender doesn't care who rents it" - because lenders do care. If your spouse and kids were to occupy that property because you are on a split - that would be a big deal. So, they do care who rents a property.
Anyways, hope this helps in some way. Here's the pictures I was telling you about:
Thank you both very much - I appreciate the wisdom and affirming my suspicion about claims like "a lender doesn't care." @Andrew Postell - that was so nice of you to spend the time on such a thorough analysis - it's very helpful!
two questions I have are:
1. Who ar the family members. A cousin is very different than a child.
2. Do those family members have the income that can support the rental payments?
This is one of those gray areas where it really depends on the lender, but you're right to want clarity upfront. With DSCR loans, a lot of lenders focus on business purpose and arm's-length leasing, so renting to family can be an issue even if the rent is at market. Sometimes it doesn't come up early, but it can surface later in underwriting or after closing, which is where people get surprised.
If you’re comparing options, I’d make sure any lender that says they allow it is explicitly okay with non-arm’s-length tenants and has seen that plan before. Have you gotten anything in writing yet, or is this still at the “verbal okay” stage?
Thanks for urging me to get that in writing, @Matthew Bernal. It's still been at the verbal okay stage. Would you recommend that a lender get that to me in writing at the time of pre-approval?
@Andrew Postell
I think your response was very appropriate as to how owners of an LLC securing a DSCR loan are signing the mortgage documents and the limitation it puts on them.
I found it interesting on the loan that it stated that the owner or family did not intend to rent it out which seems like an exception as it goes back to intent. If it was the intent all along to rent the property to your daughter or other relative then seems you violated the document, but if it wasn’t predetermined then you are ok. Legal Language is always subject to interpretation by a judge if it were to go that far.
I found the disclosure an interesting point.
@Andrew Postell
I think your response was very appropriate as to how owners of an LLC securing a DSCR loan are signing the mortgage documents and the limitation it puts on them.
I found it interesting on the loan that it stated that the owner or family did not intend to rent it out which seems like an exception as it goes back to intent. If it was the intent all along to rent the property to your daughter or other relative then seems you violated the document, but if it wasn’t predetermined then you are ok. Legal Language is always subject to interpretation by a judge if it were to go that far.
I found the disclosure an interesting point.
Intent doesnt matter on these. You can't intend to use it for business purposes and then later move into the property as a homeowner because circumstances change (like you can with some federally related mortgages). The entire premise that allows DSCR loans to be exempted from the consumer protections of federal regulation - Dodd Frank, RESPA, TILA, etc, and specifically the ATR rule - is that the loan proceeds and property are used only for business purposes, not consumer purposes.
The second that you use it for consumer purposes, you are in default of the terms of the loan and the lender should (and likely will) call the loan when they find out. The fear from the lending side is that by not acting, the lender will be seen as complicit and will have legal exposure on a loan that violates federal (and most states') mortgage laws. I can tell you first hand that this is taken very seriously. AAPL (I think?) recently listed one of the top legal challenges to private loans right now is borrowers claiming that business purpose loans are actually consumer loans and arent enforceable because of consumer protections violations.
Every lender's documents are slightly different. Some are notarized, some are not, wording is different, etc. I can say with certainty just off the top of my head that at least two wholesale investors that we use have language to the effect of "you will not occupy the property while the loan is outstanding" in the doc sets.
I'm looking for DSCR lenders that will allow me to rent an investment property, at the market rate, to two family members. I'm in Kent, WA, and looking at rental properties in Mount Vernon, WA, about 70 miles away. I've found one lender that allows it, but I'm looking for others so that I can compare. I also spoke to a Seattle-area broker about it, and he said that a lender won't ask about who's renting, so it really doesn't matter. However, I want to make sure that any lender is fully aware that I intend to rent to family and has no prohibition against it. Thanks in advance for any leads!
Hey Anthony,
I would suggest you get this confirmation from an Account Executive or Underwriter in email.
It is highly unlikely a DSCR lender will allow you to rent out to relatives. Most lenders will look at the tenant name and may run a background report to verify you are not related to the tenant.
Also if you are using the lease, most DSCR lenders will want to verify 1st months rent + deposit to verify it is a legit lease agreement. If they see a relative's name giving you the rent payments, that will be another red flag.
I'm looking for DSCR lenders that will allow me to rent an investment property, at the market rate, to two family members. I'm in Kent, WA, and looking at rental properties in Mount Vernon, WA, about 70 miles away. I've found one lender that allows it, but I'm looking for others so that I can compare. I also spoke to a Seattle-area broker about it, and he said that a lender won't ask about who's renting, so it really doesn't matter. However, I want to make sure that any lender is fully aware that I intend to rent to family and has no prohibition against it. Thanks in advance for any leads!
I am only aware of one DSCR lender that would knowingly allow this. However, a simple solution may be purchasing the property as a second home... you can put less down and use it pretty much however you choose so long as you or a family member occupies it for at least 2 weeks a year. I cannot recall the distance requirement but thought it was 50 miles from your primary at one point. It may be 100 miles now, which would make it not qualify. Either way its worth looking at if your income and DTI can support it. If it won't work as a second home, then normal conventional lending as an investment doesn't care who you rent to...
Cheers!
Thanks to everyone for their honest responses! @Nick Belsky, can you share with me the one lender that you know that would do this? I'm also willing to explore other lending routes as well.
@Patrick Roberts is right here. Renting to family under a DSCR loan is mortgage fraud and an underwriter is definitely going to care who you are renting to so they are not seen as complicit.
If you buy it with a conventional loan and rent to family (as long as you're charging market rates) will be fine as long as your income supports it. I'm a broker licensed in WA and can give another conventional quote to compare, but pursuing a DSCR is a dangerous path.
The framework above is right!
The line lenders actually care about is occupancy and business purpose, not "family" per se. A DSCR loan is a business-purpose, non-owner-occupied loan, so two things keep you clean:
(1) it's genuinely arm's-length at market rent, a signed lease plus the appraiser's rent survey (1007) supporting that number covers you
(2) you or your spouse/dependents aren't the ones occupying it. Renting to a sibling, cousin, or an adult child who isn't your dependent at market rate generally doesn't violate anything, but you're smart to want it in writing. When you call lenders, ask specifically whether they carry a "related-party" or "non-arm's-length" tenant overlay ,
a small number add one even when the standard docs don't require it, and that's the question that actually separates the lenders who'll do this from the ones who won't. Happy to tell you which overlays I'm seeing out there right now to save you some calling around.
I'm looking for DSCR lenders that will allow me to rent an investment property, at the market rate, to two family members. I'm in Kent, WA, and looking at rental properties in Mount Vernon, WA, about 70 miles away. I've found one lender that allows it, but I'm looking for others so that I can compare. I also spoke to a Seattle-area broker about it, and he said that a lender won't ask about who's renting, so it really doesn't matter. However, I want to make sure that any lender is fully aware that I intend to rent to family and has no prohibition against it. Thanks in advance for any leads!
@Anthony Warnke
This is definitely something to verify with the lender before moving forward, since DSCR guidelines can vary. If the rent is truly at market rate and properly documented, some lenders are more flexible than others, but it's worth confirming the occupancy and lease requirements upfront so there aren't any surprises during underwriting.