When you submit a Fix/Flip to a lender which part of the deal gets the most scrutiny

When you submit a Fix/Flip to a lender which part of the deal gets the most scrutiny

Charles WalkerBusiness Member
Real Estate Consultant · Member since 2025 · 32 posts · 2 votes

I think it is useful to view underwriting as a connected story rather than a checklist of isolated ratios.
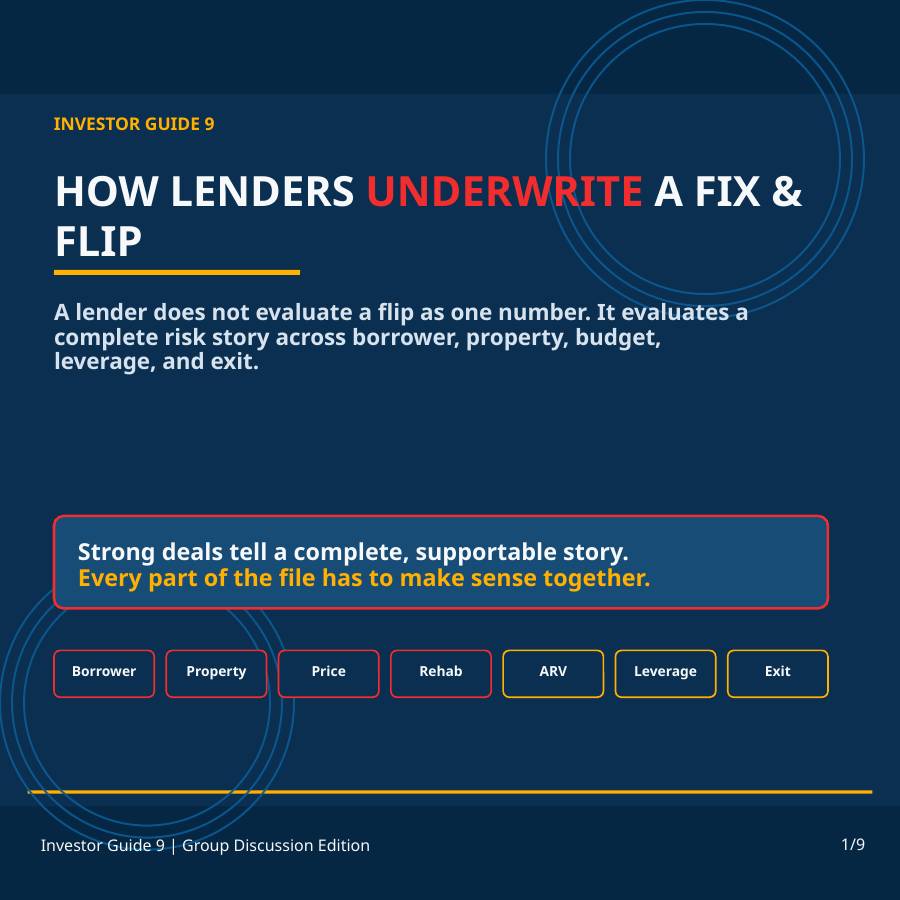
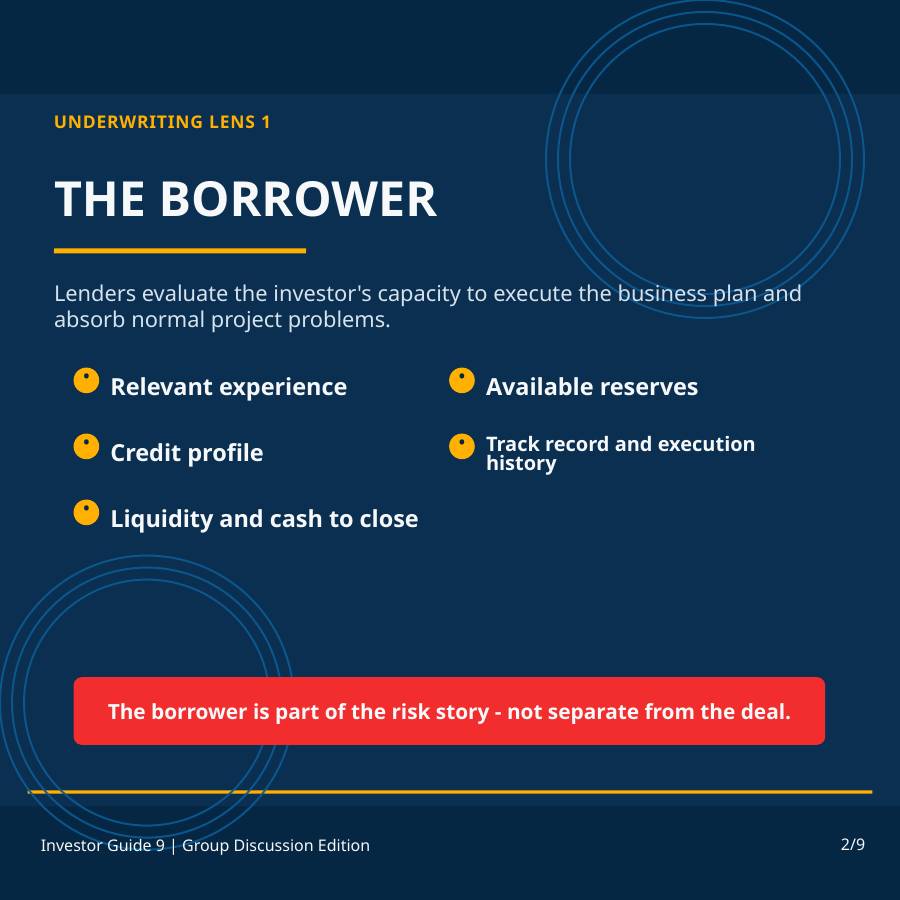
A lender may be trying to answer questions such as:

·         Borrower: Does the investor have the experience, liquidity, reserves, credit profile, and execution history to complete the plan?

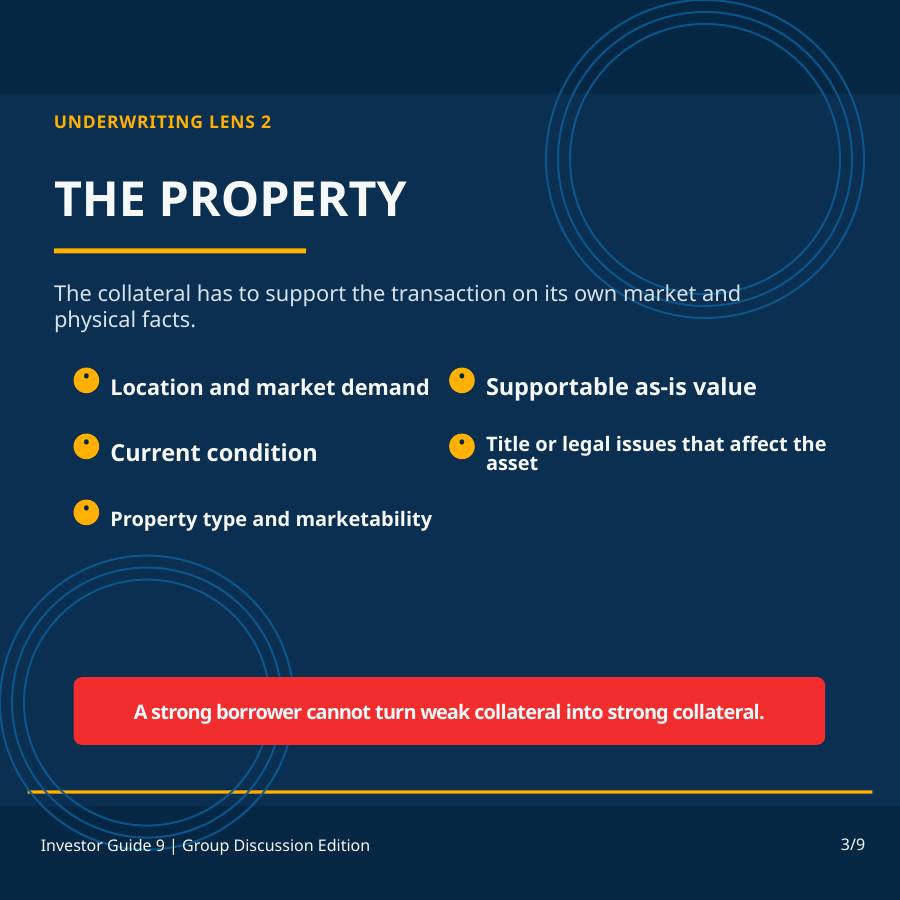
·         Property: Does the location, condition, property type, marketability, and as-is value support the transaction?

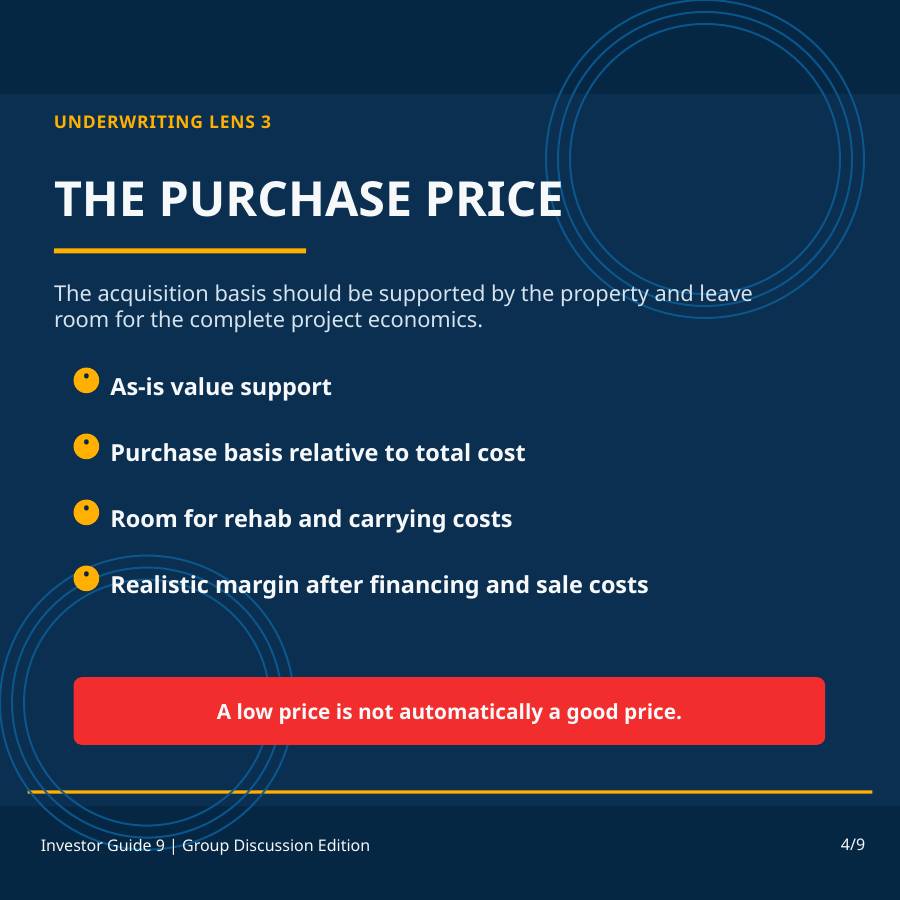
·         Purchase price: Is the acquisition basis reasonable relative to the market and the planned improvements?

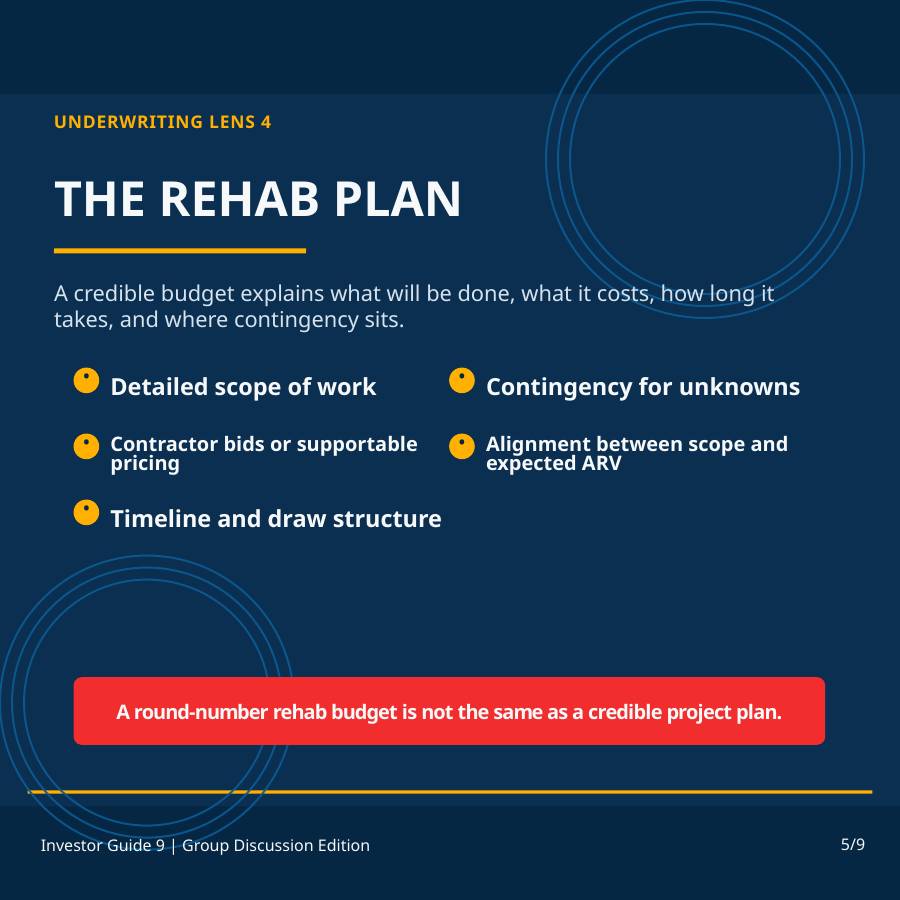
·         Rehab: Is the scope complete, are contractor numbers supportable, and is there enough time and contingency?

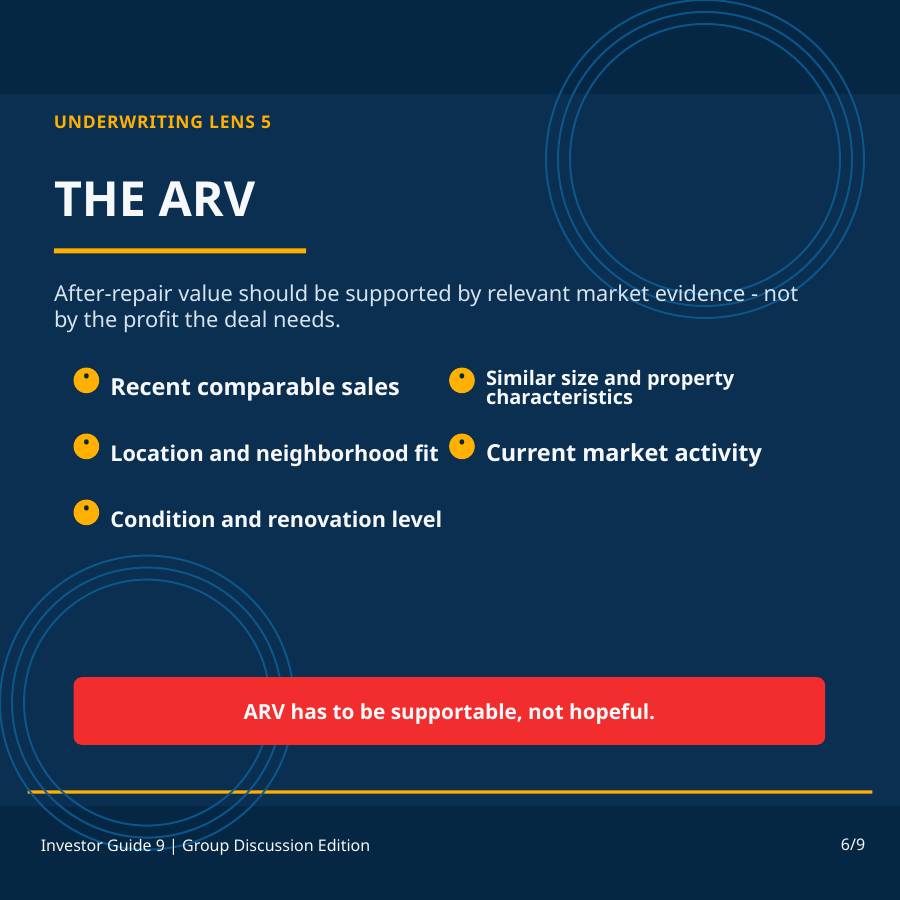
· ARV: Do relevant comparable sales support the projected finished value?

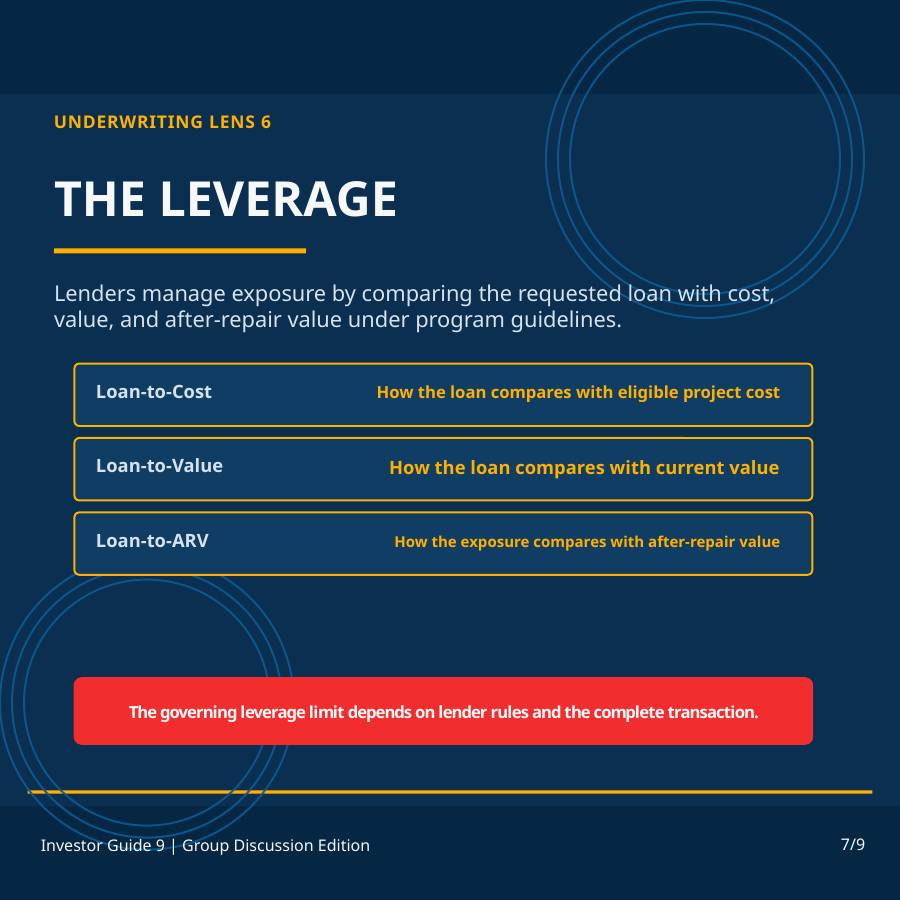
·         Leverage: How much debt is being requested relative to cost and projected value? Exact LTC and LTARV calculations and limits vary by lender and program.

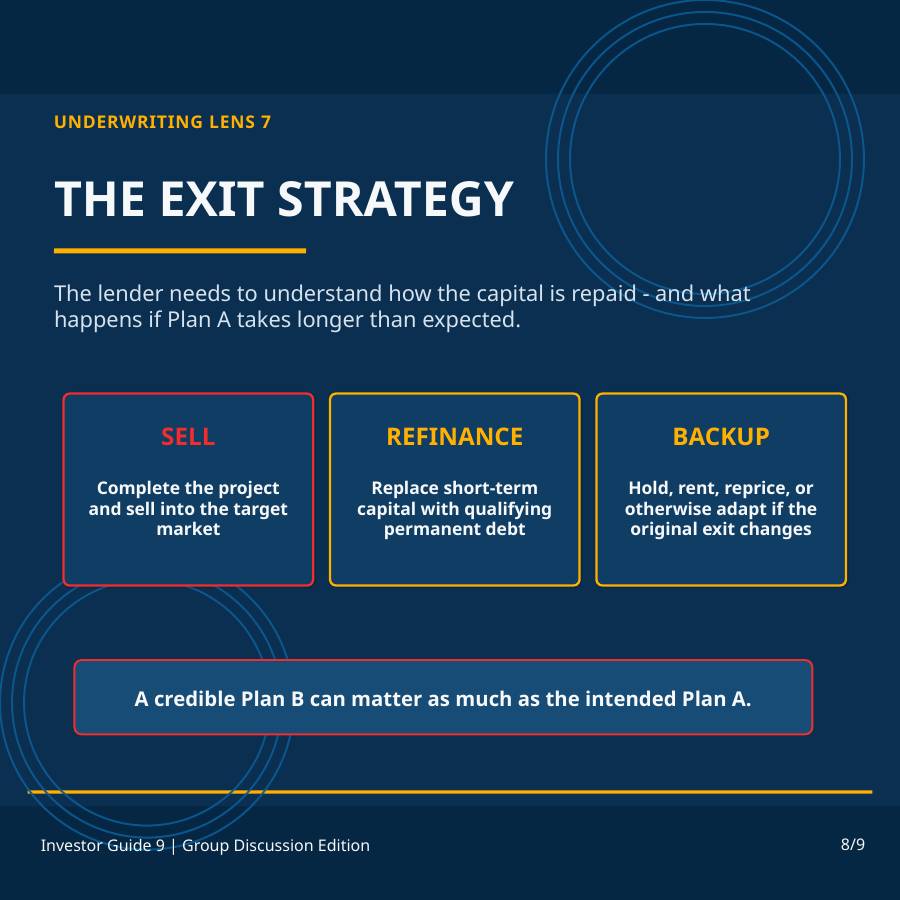
·         Exit: What is the primary repayment plan, and what happens if the rehab, sale, or refinance takes longer than expected?

For the property-selection side, our earlier Investor Guide, "Choosing a Fix & Flip Property," covers location, condition, marketability, and value considerations. For the rehab side, "Proven Strategies to Maximize Fix & Flip Returns" provides a companion look at planning, contractors, budgeting, and execution.

For investors who have funded several flips: which underwriting issue most often changes the original loan structure - borrower liquidity, rehab scope, ARV, leverage, or exit strategy?

1Reply
455 views

9 Replies

Jump to latestLatest
  • Matthew MorrowBusiness Member
    Investor · PA - NY - NJ · Member since 2019 · 853 posts · 299 votes
    1w

    @Charles Walker from the investor side, the ARV is where I've seen the most pushback lately. Appraisals are coming in light across the board right now, so a lender has every reason to lean on the comps behind the number. Behind that, a rehab scope that's detailed and realistic tends to answer a lot of the other questions before they get asked. Interested to hear what the lenders here say.

    CORE Team | Realty ONE Group Supreme548 Reviews
    • Lender · Miami, FL · Member since 2026 · 28 posts · 8 votes
      6d

      Yes, as a lender a big part is the ARV. Which is different in every market. As a lender, I'm targeting luxury or expensive zip codes

  • Charles WalkerBusiness Member
    OP
    Real Estate Consultant · Member since 2025 · 32 posts · 2 votes
    1w

    Matthew, the comps behind the ARV deserve close attention. I would be careful about applying "across the board" to every market, but your point raises a useful question: does the projected value reflect recent comparable sales and the condition the renovation will actually deliver?

    The scope and ARV also need to support each other. If the valuation assumes an updated kitchen, another bathroom, or added living space, the budget and timeline need to account for that work.

    I’d welcome lenders’ perspectives on where they are seeing the largest gaps between submitted ARVs and supported values.

  • Matthew MorrowBusiness Member
    Investor · PA - NY - NJ · Member since 2019 · 853 posts · 299 votes
    6d

    @Charles Walker fair point. I'm speaking to what we're seeing in our part of PA, not every market in the country. Agree the scope and the ARV have to tell the same story. If the comps are fully renovated and the scope is paint and carpet, that gap is exactly where a lender is going to push. Interested to hear what the lenders say.

    CORE Team | Realty ONE Group Supreme548 Reviews
  • James JonesPro Member
    Investor · Collierville, TN 38017 · Member since 2017 · 876 posts · 614 votes
    6d

    Charles, in my experience it is the ARV, and it is not close. The borrower and the purchase price are facts. The ARV is the one number in the file that is an opinion, so it is the one that gets picked apart. I BRRRR single-family in Memphis — buy under $100K, ARV $180K to $265K — and I comp off sold prices only: same ZIP, similar beds, baths and square footage, last six months when I can get it. When my ARV is built that way, the leverage conversation gets easy, because a DSCR refi at 70 to 80 percent LTV against a real number is boring. Deals get re-cut when the ARV needs list prices to work.

  • Divin KanyamaBusiness Member
    Accountant · Seattle, WA · Member since 2025 · 566 posts · 242 votes
    6d

    @Charles Walker I agree that underwriting is a connected story. In my experience, the greatest scrutiny usually falls on the assumptions that determine whether the lender gets repaid: ARV, rehab scope, borrower liquidity, and exit.

    ARV and scope often change the structure first because they drive leverage and required cash. If the comps are weak, the budget is thin, or contingency is inadequate, proceeds usually come down. Liquidity becomes equally important when the borrower must fund overruns, carry costs, or delayed draws.

    The strongest file is internally consistent: the purchase basis leaves room for the work, the scope supports the ARV, the timeline matches the project, and the borrower can survive a slower or more expensive execution. A credible backup exit matters too—especially when the primary plan depends on a quick sale or aggressive refinance.

  • Nicholas FloydBusiness Member
    NY · Member since 2026 · 322 posts · 103 votes
    4d

    Charles, great breakdown. From a funding perspective, I’d say borrower liquidity and available reserves are two of the biggest challenges, especially for investors trying to take on multiple projects at once.

    A deal can have a solid ARV, realistic rehab budget, and a good exit strategy, but if the investor doesn't have enough accessible capital to handle unexpected expenses or delays, that can create problems.

    That's one reason I help real estate investors explore alternative business funding options, including 0% APR business credit cards, business lines of credit, business loans, and revenue-based funding. Depending on eligibility, these can provide additional working capital for permitted project expenses without relying entirely on property-backed financing.

    I’m curious, Charles, when you’re reviewing fix-and-flip deals, do you find that borrower liquidity causes more issues than the actual numbers on the property?

  • Real Estate Consultant · Riga, Latvia · Member since 2026 · 59 posts · 11 votes
    4d

    Hi Charles, thanks for laying it out as one connected story, that's a really helpful way to look at it!

    From the renovation side, the rehab line is where a deal story most often falls apart, because it's usually the least documented part: a contractor lump sum plus a contingency percentage. What made our budgets easy for clients to check was pricing scope as quantity x unit rate from photos of the current condition, so anyone reviewing it can see what's being replaced and why it costs that. The same photos later become the baseline for draw inspections.

    Curious to hear from the lenders here: does a line-item scope with photos actually speed up underwriting, or do you re-scope everything with your own inspector anyway? Have a great weekend, everyone!

  • Lender · Irvine, CA · Member since 2026 · 12 posts · 1 vote
    11h

    From the lender side, the thing that changes a loan's structure most often is the rehab budget measured against the ARV, not the borrower. A thin budget on a heavy scope tells me either the investor doesn't know the cost or the ARV is stretched, and either way the loan gets resized.

    Second is liquidity. Plenty of first-timers qualify on experience exceptions, but not if they'd be out of cash after closing with no cushion for overruns.

    The fastest approvals I see come with a line-item scope, contractor bids, and 3 sold comps that actually match the finished product.

    Full disclosure, I'm a hard money lender, so this is my day job.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.