Rental Property Investor · Tampa, FL · Member since 2019 · 128 posts · 166 votes
The role of the Appraiser is an odd one: Way too much art (opinions) and way too little science (data-analytics), with way, way, way too little accountability. While the world embraces tech tools to automate workflows and tasks, reduce errors, and thereby increasing precision, the Appraiser is basically doing the same thing they did 80+ years ago. Show up with a tape measure and a camera, pretend like they are doing something scientific, pontificating unscientific opinions, charging ridiculous fees for said opinions, then going home with no accountability for the disasters that stems from those opinions. And the worse part: we have to pay for this rubbish, and live with the rubbish for 3-6 months we can pay for new rubbish --OR live with the rubbish and make a whole helluva lot less $$ then a scientific method would have yielded.
These people are not scientists. They are not "professionals" in a true sense of the word. Yes, in exchange for 75 hours you too can obtain a license to be an Appraiser and work on your own! No one will check your work. That's NOT a professional. And by extension, it should no longer be a profession.
This is a role in our investor ecosystem that is ripe for automation and transformation. I, for one, am sick and tired of these opinions (and folks, let's be honest -- that's all they are offering here. 75+ hours of qualification to offer you their opinion on what they think your property is worth.) Now I know there is the occasional rare professional equipped with both experience and a scientific method. Well, I don't actually "know" -- I just suspect. I've never actually had the privilege of meeting or interacting with such a rare species. (And to be fair, Robert Kiyosaki has said (once) 'a great Appraiser is invaluable.' I've just concluded that this is must be some mythical creature that would have great value if the creature actually existed. But I digress...)
Alas, I don't know what one individual can do. The ecosystem is set up to require us to get an appraisal the same ol' way we've been getting them since the 1930s. So all I can do is joke about it. So please join me in sharing your favorite Appraiser joke. I'll start:
“What does an appraiser’s wife say if she can’t sleep? ‘Honey, tell me about your day at work.’”
Ok, one more...
“I finally figured out how to make a million dollars in the real estate business. You ask an Appraiser to appraise your two million property that you own free and clear.”
Keep it going... go on! I know you have a favorite. Please share!
If the appraisal is 100% for the lending institution why am I paying for it?
The same reason borrowers usually pay for lenders’ document prep fees, notary fees, and other similar fees. (All things that benefit the lender but borrowers typically pay for.)
It’s the cost of doing business (lending money) and you want their money.
Greg you have have obviously been burned by an appraiser recently. Yeah it sucks. I had one come in low on what I thought was an easy duplex appraisal. I think Ed really got it right on his explanation Greg I am not sure you have researched what it takes to be an appraiser now. Most have to get the 75-100 hour class you discussed and then do a 2-3 year apprenticeship for another 2000+ hours. I think it is very unfair for you to call them out as not being true professionals. You our anyone on this forum can call themselves a real estate professional by claiming they have flipped a house or have a rental. Does that really make them a professional. Appraisers provide a function for lenders. Would you rather your lender just took the zillow value. Zillow can tell if you gutted and renovated a 1500 sq fto house and if the one next door is a dump. Someone has to go out a verify information. That is what the appraiser is doing. Verifying the house is there ad has the features stated so the lender can make the decision if they want to lend the money. In the last crash the appraisers took alot of the blame for "inflating" values. That is why appraisers now or very conservative. This is obviously opposed to what we as investors want, higher values. Work with your appraiser. Every time I meet an appraiser I give them a list of comps. They don't have to use them but at least they know I have researched and what I am expecting.
@Greg Moore I’ve read the thread and, perhaps I missed it, but to those who are “roasting” the current appraisal process and appraisers in general, what is the solution?
I’m not an appraiser, and don’t even know any appraisers, so I don’t have a dog in this fight. I’m honestly just curious because I’ve read a lot of posts pointing out what’s wrong, but no real viable alternatives offered.
There has to be something in its place and whatever that looks like it is always going to include an element of art vs science (i.e. an opinion of value).
People don’t like when a computer/algorithm (Zillow, Redfin, etc) does it. Apparently people also don’t like when a human (appraiser) does it. So what do you propose?
Great discussion! I have always questioned their independence and “non-objective” appraisals and comps. In my experience, I often feel like they are working for the other party (buying agent or bank) because some of the comps don’t make sense. I have the experience and know how to pull recent sold’s (closed public records sold) along with pictures to object to what they have but they won’t listen or even take into account what I found.
I would like a way to challenge the appraisal. Maybe there is and I don’t know?
Challenging an appraisal may be illegal.
It is not illegal to challenge an appraisal if errors are discovered, however be advised, no appraisal is perfect and there is room allowed for small errors before an appraisal will be deemed deficient. The errors must be a) substantial to the result or b) so numerous that they illustrate incompetence. A couple of typos aint going to cut it. An appraisal that demonstrates an appraiser can't add and subtract might. An appraisal that demonstrates a difference in opinion between you and the appraiser is not going to cut it.
It is illegal to challenge the appraised value in all mortgage appraisals. It is illegal for the bank to do it. It is illegal for the borrower to do it. It is illegal for the realtor to do it. It is collusion if these parties conspire to do it.
Where everyone goes wrong on this issue, is the law allows the appraisal client (the bank) to request supplemental information from the appraiser post-submission of the appraisal report, for the purposes of providing further support of the value conclusion already made and delivered. This provision is widely misinterpreted, for obvious and self-serving reasons, as an open-season to challenge the value conclusion. Take a second and consider the circumstance of obtaining a mortgage appraisal in the first place - the entire point is to create a barrier between the valuation of the asset and the loan officer, according to the rule of law to do so - not because nobody other than the appraiser can figure out what the property is probably worth.
The absence of law enforcement has made the problem more widespread, to the point where people are challenging appraisals all the time. In the absence of law enforcement, each individual appraiser faced with the circumstance must navigate how to address challenge requests, often blatantly titled "Reconsideration Of Value Request" by the lender, borrower and realtor. Some lenders even have policies encouraging borrowers and inviting realtors (what the hell is the realtor doing in the loan office?). What most appraisers do, is bite the bullet and write a paragraph of nonsense saying they aren't going to change a damn thing and **** you, written in a much more polite and professional manner. The really stupid appraisers will actually conspire illegally with the bank, borrower and realtor and change the value (if I can add to this thread list of things stupid appraisers do, that might be the top of my list). The incredibly smart appraisers MIGHT take the time to explain this to the client, except by doing so, lenders usually call another appraiser the next time, seeing as they prefer to have their head in the sand while the sand is profitable. See no evil.
The influence on appraisers from loan brokers in the modern world is the telephone. Play ball or the phone stops ringing. Each appraiser actively working in the mortgage industry currently is therefore a) ignorant of the laws governing the profession - an act prohibited under USPAP or b) dishonest or c) both or d) doing the best they can while they suffer injustice and an impossible choice. I'd say option D is the most common one. It's 100% the appraisers fault and at the same time is 0% the appraisers fault. That last bit takes a few more pages of text to explain. It's also at the core of why I stopped being an appraiser. I have seen the evil and have walked away.
As far as the question about comps, why are you attempting to analyze comps??? Think hard. Answer honestly.
As far as your inclination that appraisers are working for the "other" party, I wonder at what point did you ever think it might be any other way??? Was it when the bank talked you into paying the fee for the appraisal? Is that when you thought you purchased an interest? Of course the appraiser is working for the bank. The appraiser is working only for the bank. And what that explains, is why the comps appear to be selected according to what the bank might want to see, maybe not what might make the most sense to another party. That is exactly what is happening, and also exactly as it should be. Your problem is you think you are entitled to more for your money than you are!!! (As a side note, the only reason the borrower receives a copy of the appraisal report today when they pay for it is because someone complained to the right person and a law was passed a few years ago - borrowers did not always get a copy, and the fact that everyone does now creates confusion over the rights of use.)
As far as the ability to pull data on your own - bravo! Each investor will need to become their own appraiser. Then when you have cash and don't need a bank, that skill will really come in handy as there are no social safety nets in place for cash buyers.
Thanks for the reply. I pull and analyze comps to compare my home to others and I’m pretty fair as evident that some of the flips sold first week or even weekend and they close, several for full asking price. Of course, I want more money and I fight for my right (and hard earned effort) to maximize my profit while balancing the need to move it quickly.
I had one house on a great quiet street, all new electrical, kitchen, master bath, floors…etc. One of his comps was a house on a four lane busy road that was not remodeled. I showed them a house similar to mine around the corner that was remodeled and sold (closed) within a couple of months of my listing. That was not one of his comps.
I only want them to be fair and consistent and that is my hang up with some…not all of them.
If you are good at pulling comps, what you could do is present them to the appraiser when the appraiser comes to do the inspection. Any good appraiser will welcome more data coming their way. It will also give you a chance to tell the appraiser why the property is valuable to you. Too many people think they are forbidden from having a conversation with the appraiser - not true. What the appraiser is forbidden from doing is disclosing confidential assignment information - in other words it's the banks appraisal - so the conversation will be one sided. With the last flip I invested in, the "easy-to-find" market comps dropped about $10k from $130k to $120k within the time I was flipping (an anomaly) - not a ton of money but very significant for a flip when we were already over budget and I was definitely planning on $130k or better. I did some deep diving on comps and found some, then presented them to the appraiser and explained my property was a flip and that FLIPPERS DO NOT HAVE A TYPICAL MOTIVATION TO SELL AND SO HOMES SOLD AS FLIPS MAY NOT REFLECT MARKET VALUE - The house got sold for full asking and I never heard another word of it. This is a roast of crappy appraisers right? A crappy appraiser will over-look the part I capped and so a smart investor will remind them of that. Mortgage appraisers don't get paid to make sure a loan goes through. What they do is provide a cheap and fast product that gets the job done and on to the next. Sometimes the seller would be wise to do some of the appraisers work for them.
@Raul R. Oh my gosh, I love this idea! Simple, doable. And would introduce at least the same kind of social accountability everyone else providing a service has to live up to. Maybe we just start it here on BP??
If the appraisal is 100% for the lending institution why am I paying for it?
An excellent question. Maybe you should ask your lender next time they ask you to pay it. It wasn't always like that. Before 2008 it was common for the loan officer to foot the bill and if the loan went through, the fee would be rolled into the closing costs - zero fee from the applicant borrower up-front. This arrangement happened about 50% of the time. This is an example of market economics. Maybe when people realize that some banks are skimming the appraisal fee too, they might even refuse to pay it any other way than at closing, or at all. But that of course comes down to how bad someone wants to get a loan. It's a gamble really - my term for it is the CGT - the Consumer Gambling Threshold - That is in fact the force that sets the appraisal fee, not the appraiser. How much is a potential borrower willing to pay up front and potentially lose before they will no longer apply for a loan??? I promise you your banker knows the answer to that question, or at least the people that own the bank do.
@Merritt S. Thanks for your insights on this thread. They were useful. I do understand your main point. And perhaps there is nothing I as an individual can do about it other than roast Appraisers. Know any good jokes?
Sorry. This topic is personal for me. I'm like a dog chasing a squirrel with this stuff. If you think I went-off here, you aint seen nothin'. I attempted to get my appraiser peers organized to fix all the things being discussed here for years and it went nowhere. I had to leave the profession because of it. I thought I would retire as an appraiser when I started doing it. It still makes me furious. I dunno. Maybe what I really need to do is to take the medicine your offering here!?!?
So here's my joke and it's a really bad one because I can never remember a joke so I just made it up - but sort of appropriate to what I'm attempting to say.
How many appraisers does it take to change a light bulb?
Until appraisers organize in a fashion similar to the NAR, all these problems with the appraisal profession will continue. For now, the United States Government has taken on that role of organization, and they allow the banks to have a say. Because of the way politics works, appraisals, and the entire appraisal industry as a result, are exactly as the banks would have them.
With this rating system being proposed in this thread, for starters there already is Yelp, and for seconds you would be complaining about a service you did not receive. That would be like going on Yelp and complaining about the food eaten from the customer in the next table when you didn't even take a bite, though maybe you picked up the bill.
A lot of talk has been made here about methodology. The first thing to set straight in that category of discussion is the concept of expectation. It is the foundation of all appraisal work, the very first thing that must be established when a client contacts an appraiser to hire them in all cases for all appraisals. Without that established context of expectation, the appraisal client would not get what they were hoping and paying for. Without understanding what that that context is, anyone reading the appraisal report who is not the appraisal client would not understand the appraisal. That's what happens with mortgage appraisals. They are the banks appraisal, not the borrowers, so the borrower often fails to understand the appraisal.
The argument of if an appraisal is an art or science will likely never be resolved. There are too many valid points to argue on either side. But what is never in contention, is the appraisal is an opinion at the end of the day. This is why few to zero appraisers lose lawsuits in court when sued over a valuation. The other reason many lawsuits fail is the moment the judge looks at the part of the appraisal that reports the name of the client. When the judge sees it is the bank and not the borrower, and it is the borrower standing before them and not the bank, the case gets thrown out right there.
Does that count as a joke? I would laugh if I witnessed a case getting thrown out like that.
Many appraisers were very worried after 2008 when FNMA initiated it's buy-back program. FNMA went back and did a forensic review of each and every failed loan they had on their books - thousands and thousands and thousands of them. They had the money to do this because the United State Government had taken them over, which is still the case today I believe (not sure on the last bit). Of course countless appraisals were identified as flawed and the originating bank was forced to buy the loan back for violation of the Fannie Mae Selling Guide, which serves as a contract between originating lenders and FNMA - these were all contract-law cases.
The really interesting part about that whole thing is not one appraisal was identified as flawed because of a bad valuation alone, or for all sorts of things a person might assume would qualify as a flaw. What they did is identified occurrences where the appraisal did not meet the guidelines set forth in the Selling Guide, and once they established that, they hired an appraiser to go back and do a retro-active field-review of the original appraisal. If the original appraisal was non-compliant and if the value from the field reviewer came in at least 10% less than the original appraisal, they would make a case in court for a buy-back.
Want to know how many appraisers got sued for having an appraisal identified as flawed within the FNMA buy back? Zero. FNMA did not file a single case. We are talking billions and billions of dollars here. Chase, I believe, was the only originating lender to attempt to go after appraisers, and they lost every single case that went to court (I believe they were able to settle with some E & O insurance companies). This is for two reasons. For starters, an appraisal is an opinion, it's art. Second, it was not the fault of the appraiser, it was the fault of the underwriter/originating lender, who failed to deliver a loan to FNMA that met the contractual guidelines.
Mortgage appraisals are submitted to the originating lender and what they do once they have it, is go over it to make sure it is complaint. They could care less what the value is. This is why you see really strange things in a mortgage appraisal, like really insane comparable properties selected for the sales grid. The originating lender does not have to accept any appraisal ever, it is buyer beware. Nobody is forcing them to write a loan based on a "bad" appraisal. A better term than bad is weak.
@Greg Moore reading stories like yours and others on this thread are extremely disconcerting. I’m new to the RE investment scene and have been reading and listing to everything I can find on the subject. It is ludicrous that someone can have so much unregulated control over the valuation of a property.
@Greg Moore, loving this post! I find it hysterical everytime I get an appraisal. For one, I have access to all or more of their data. For two, it takes me about 30 min max to come to an unbiased decision. And I love how the bank hires them, as if their in the business of giving low valuations lol. The first time I get a low appraisal is the last time I will call them. The last appraisal I got came within $500 of our offer...like really.
It takes me about 10 minutes. It's the inspection and report that takes all day. Mortgage reports used to be 6 pages, only two needed to be filled out and the rest was boilerplate language. Average mortgage appraisal today are 40-50 pages. Brokers are not required to support their opinion, which is why BPO's are a joke and why they are illegal for any other purpose than marketing in most states and at the federal level. Appraisers are required to support their opinion, which is not easy.
When was the last time you personally hired an appraiser as a realtor??? Or as a homeowner??? Then again, why would you? If you don't know what a property is worth as a broker how good are you at your job right??? Like you said, 30 minutes and done. LOL.
Here in WI the state has adopted boiler-plate real estate contracts to serve as the accepted default - most transactions take place employing those forms. The single family here is called the WB-11. All of the state-approved contracts have language in them that along with the language in the USPAP, serves to artificially keep prices increasing perpetually. The language in the WB-11 is this:
APPRAISAL CONTINGENCY: This Offer is contingent upon Buyer or Buyer’s lender having the Property 311 appraised at Buyer’s expense by a Wisconsin licensed or certified independent appraiser who issues an appraisal report 312 dated subsequent to the date stated on line 1 of this Offer, indicating an appraised value for the Property equal to or 313 greater than the agreed upon purchase price. 314 This contingency shall be deemed satisfied unless Buyer, within ________ days after acceptance, delivers to Seller a 315 copy of the appraisal report indicating an appraised value not equal to or greater than the agreed upon purchase price, 316 and a written notice objecting to the appraised value
What is unfathomable to me is that the State Of Wisconsin approves that garbage. Don't they have lawyers? Not very good ones. At what point did the parties in this contract ever obtain permission from the lender or appraiser to use the mortgage appraisal to satisfy the Appraisal Contingency in this contract? Never happened. This contract makes an assumption about other parties unrelated to the contract and by doing so, creates a the vehicle by which prices can artificially increase perpetually.
An appraisal contingency ought to be an agreement between the buyer and seller, where they agree that one party or the other or both will purchase an appraisal for the specific purpose of settling the matter of value in the agreement. Using the banks appraisal is a convenient way to save money and time and hassle, but it could not have more devastating consequences to prices paid and the housing market. This is because of the next language from USPAP, the Uniform Standards of the Professional Appraisal Practice, which all licensed appraisers performing mortgage appraisals must follow:
Standards Rule 1-5
When the value opinion to be developed is market value, an appraiser must, if such information is available to the appraiser in the normal course of business:
(a) analyze all agreements of sale, options, and listings of the subject property current as of the effective date of the appraisal; and
(b) analyze all sales of the subject property that occurred within the three (3) years prior to the effective date of the appraisal.
Comment: See the Comments to Standards Rules 2-2(a)(viii) and 2-2(b)(viii) for corresponding reporting requirements relating to the availability and relevance of information.
USPAP requires the appraiser to "analyze" any current agreement of sale (a pending WB-11 for instance) during the development of the valuation (called the Appraisal in USPAP, different from the Appraisal Report). This provision ought not be in there. It does not say only in cases that are relevant to the appraisal assignment. The Comment at the end refers to that, and directs the reader of the USPAP to seek other information concerning what needs to be reported and what doesn't, according to the relevance. Well, how is the purchase price of a pending contract relevant to an independent and unbiased valuation? It isn't. Now, if you're a bank, no big deal, you only lend 80% of the purchase price and require an insurance policy be purchased by the borrower naming the bank as beneficiary to cover the balance of the 20% - also known as mortgage insurance or PMI. If you are a buyer or seller, and may I point out I did not say borrower, the expectation of the valuation is in terms of only a few dollars, not thousands. I hope you can wrap your head around that, most people don't understand what I just said and how it affects the housing market.
What ought to be done is this, each buyer and seller ought to hire an appraiser on their own. The bank appraisal ought never be a part of the appraisal contingency. When the appraiser requests a copy of the purchase agreement as they are required to do so under USPAP, the buyer and seller should refuse to disclose it. An appraiser can still perform an appraisal without the purchase contract, but only after they have made appropriate attempts to obtain it. Finally, the appraiser would also have to explain to each party up-front and before they proceeded with the assignment, that appraisals are not an exact science, more of an art really, and that real estate markets are not as precise to the degree that buyers and sellers typically negotiate. At that point the buyer and seller would need to agree on an allowable variance, if the appraisal was to be expresses as a price instead of a range of value - 1-5% perhaps? Without this understanding, the whole thing is financially dangerous for all parties. It's how people get underwater on their mortgage. It's how housing bubbles expand.
Value is defined as what a willing, ready and able buyer is willing to pay and the willing seller will accept. These meet at true value. In the absence of fraud, an appraisal is useless as teets on a boar hog. IMO
Value is defined as what a willing, ready and able buyer is willing to pay and the willing seller will accept. These meet at true value. In the absence of fraud, an appraisal is useless as teets on a boar hog. IMO
Everything about the appraisal business is fracked up. The Appraisal Foundation is useless as well. I've watched a couple of their meetings and it's just a bunch of old bureaucrats patting themselves on the back. Full disclosure, I had been taking the appraisal courses but stopped after getting through 75% after finally accepting the fact that the position is going to be dead in a few years.
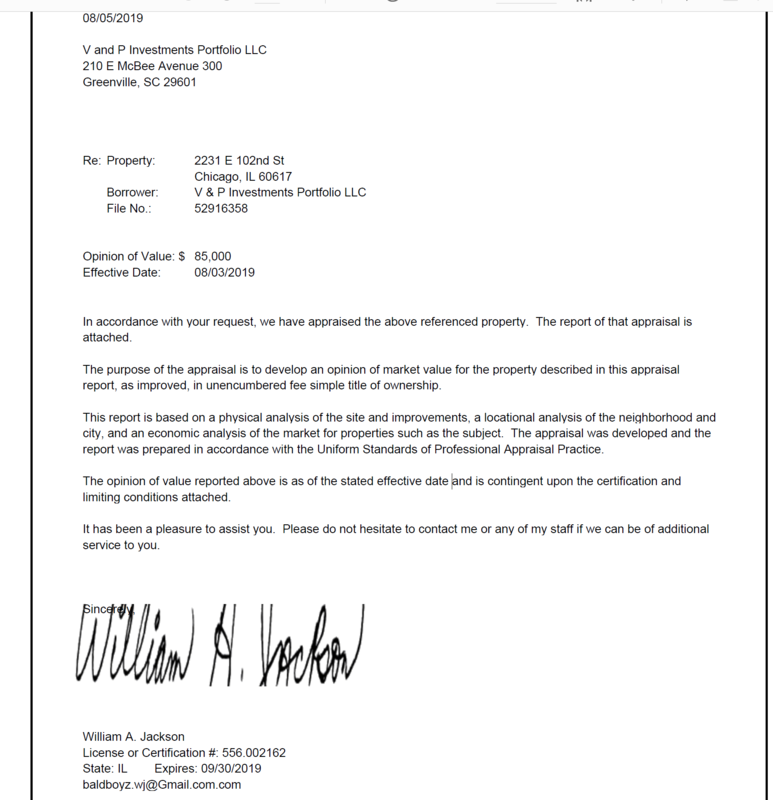
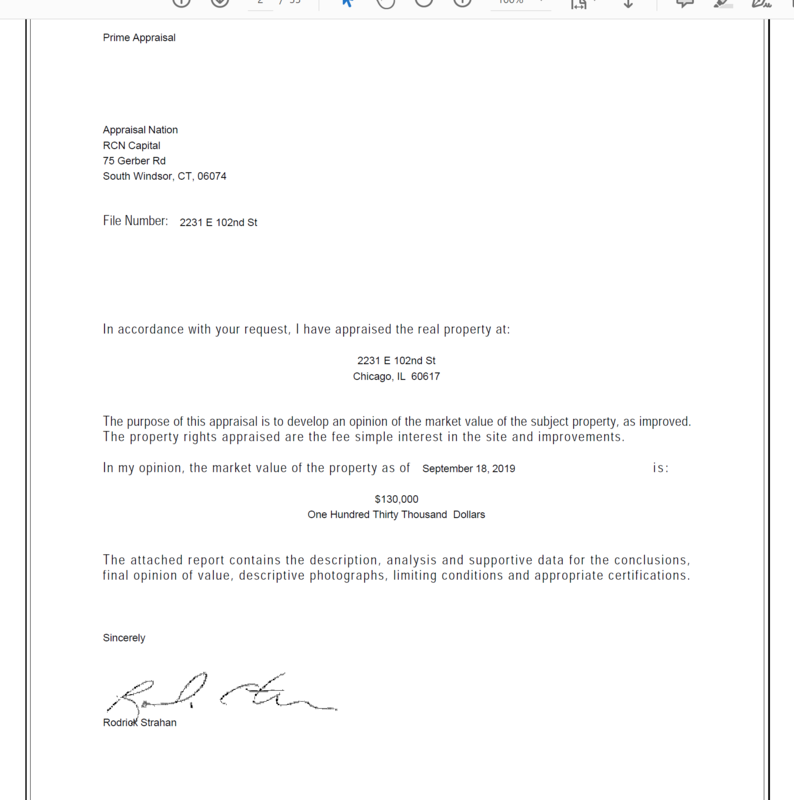
Here are two real appraisals done last Summer. One joker thought it was worth $85,000. 6 weeks later another appraiser gave is $130,000. No improvements to the property were made. Comps used are obviously totally different but the market didn't quite improve that much in over a month.
Can someone please develop an app so that MASSIVE inconsistencies like this garbage can be avoided?
And while they are at it, let's give the entire business a dirt nap. $600 for a 20 minute tour of a house and 2 hours of works is excessive.
Really want to throw them off? Ask for an appraisal on a log home. First 285k, second 185k. Two weeks apart and both were “quality inspected” by a third party.
185k: We couldn’t find any comps so we had to use a Manufactured home 30 MILES AWAY because it had similar acreage.
285k: I think the log home across the street that just sold might be a good indicator.
There is a lot of screaming and kicking at the sky in this thread, and rightfully so as I agree with the absurdity of the process and application of the appraisal field. That said, and as another mentioned, rather than screaming at the sun, why not accept it for what it is and do yourself a favor - learn how to interact with them and "influence" them to get the result you need (within reason of course). Taking a smart azz approach with them will only HURT your desired outcome.
The post copied above is the first in this thread to recognize this point and say something about it. Years ago right here on Biggerpockets, I have made posts about how to deal with appraisers as they are often out of the area and do not have personal knowledge or experience in the subject property area. Here in LA and in many other areas across the country, you could have decisively different values from one side of the main street to the other or one neighborhood to the next even if they are within a 1/2 mile radius. Only a knowledgeable individual of that specific area could know that.
So, to my point, instead of screaming and moaning, simply pull valid comps with photos and full descriptions of what the comp has in comparison to the subject property. Perhaps you were personally able to get inside some of these comps and do your own photos and inspection, pointing out what the comp didn't have that your subject property does. Providing viable and legit evidence and details to support the value of your subject property IS YOUR JOB as an investor or seller. Rather than blaming others (as easy and in this case appropriate), take responsibility and do something positive. I have heard many horror stories about appraisals coming back too low and destroying deals. Much of them could have been avoided with some effort on the part of the investor/seller.
I always made it a priority to greet the appraiser, make small talk conversation with them, and hopefully gain their respect in the few short minutes we have together. In doing so, I would hand them over a set of comps with details and a list of items my subject property had, along with costs associated with the remodel/addition. It was handed to them with the explanation that I understand how difficult their job is (an exaggeration of the truth) and that they may or may not be exactly familiar with this specific neighborhood as well as facts about each comp and my subject property which is NOT available to the appraiser. Additionally, and when it was possible, I would also provide them written backup offers showing how many buyers wanted my house at said price. Each of them were always thankful for my efforts and I have been very successful and getting the desired appraisal to meet the purchase amount of my buyer.
@Tracy Streich I’m glad someone has come to the rescue of the Appraisers. I’m surprised it has t happened before now. Please understand I’m not talking about individuals, but rather the collective function. I’ve been just as upset about the appraiser who gave me exactly the number I expected as I have been about the low ballers. Why? Because they don’t hold themselves to a consistent method or standard. My main argument here is it is time for this functional role to transform.
Ok, so there have been some good points that Appraisers work for the banks. Fine. If banks want real numbers, then how come we have numerous examples in this thread of 6-figure deltas between appraised value and purchase price within weeks? It is because the appraisers do not operate with a robust scientific method intended to produce “truth”.
I agree with your point there is a lack of professionalism in other areas. Those are not the focus of this thread. The headline of “Join me in roasting crappy appraisers” should have served as a filter for the topic of this thread.
Until I see innovation, transformation, embracing of technology, aspirations to improve, a code of conduct, and a commitment to a scientific method aimed at objectively producing consistent and accurate valuations, I will continue to point out there is a need for improvement.
@Eury Marte yes it is very disconcerting. But don't lose faith in REI! It's still a good place to be- even with the weak links described in this thread.
@Kyle J. There are several ideas posed in this thread. @Merritt S. Has made several great suggestions that get to the root causes of why the function is broken.
My answer to your question is we need a disruptive technology that is good enough (=solid business case) for banks to change their process. In my view, this will happen out of necessity. In the same way economics dictate you cannot have a slum SFH on a property that warrants a new 20 story tower, there will be a new standard established that will rely on data. Even if post-purchase upgrades could be verified and documented in a cloud platform then the time is not far away we could get "close"— definitely closer than the current people and process producing appraisals today are able to provide. When we hit that tipping point, the role of the appraiser will be obsolete (at least for standard appraisals in the beginning, and more sophisticated and bespoke scenarios over time).
I could go on with characteristics of the solution, but the purpose of this thread is to roast, so I’ll save those for another thread!
Had a property appraised recently (my first in NJ). This is for a new construction triplex. I receive the appraisal report and I'm reviewing the comps and am appalled. I notice a tiny asterisk located next to the "rent" section of the comps and start searching through the entire packet to figure out what that is for.
I finally find a small sentence that (in sum and substance) reads: if actual rents are unknown, it is up to the appraiser to determine the rent. This appraiser was from Ohio, which has a vastly different rental market than here. Especially when apparently all three comps were 3/2's that were supposedly bringing in $1,400 a month. I haven't seen those type of rents for a brand new construction in this area in....I don't know 6, 7, 8 years. A new 3/2 in the section I am in, you're looking at about $2,000 - $2,200 a month. But, that's what I got.
We build new 5-bed/5.5-bath houses and rent them to students near OSU in Corvallis, OR, and there are a couple other builders in town who build similar properties. They're technically single-family homes, but when they're sold, the price is always based on the CAP rate because they're income properties. The problem is that these sales are rare, so comps are scarce. We always explain this to our lender in hopes that the appraiser will lean into the income approach, but our appraisals are hit and miss.
A couple years ago we had the worst. The appraiser used houses in a bad part of town as comps and didn't consider proximity to campus. He came back at $390k. Later that year we had a different appraiser work on our identical houses across the street, and he valued them at a more realistic $540k, a ONE HUNDRED FIFTY THOUSAND DOLLAR DIFFERENCE.
I would agree that overall appraisals are more voodoo than science. That being said the knife cuts both ways. If you get a nightmare appraiser you are in for a long night and it could jeopardize the loan. If you have a preferred lender that you have worked with before and you know the appraiser they use than you can make some magic happen. Finding the right people is the real struggle.
If you want to get me really worked up lets talk underwriters. Those people drive me nuts!