My Goal is to be Financially Independent at 40

My Goal is to be Financially Independent at 40

Jake AndronicoBusiness Member
Realtor · Reno, NV · Member since 2019 · 1k+ posts · 938 votes

My goal is to be financially independent at 40. 

At 24, I was making $180K a year working in private equity.

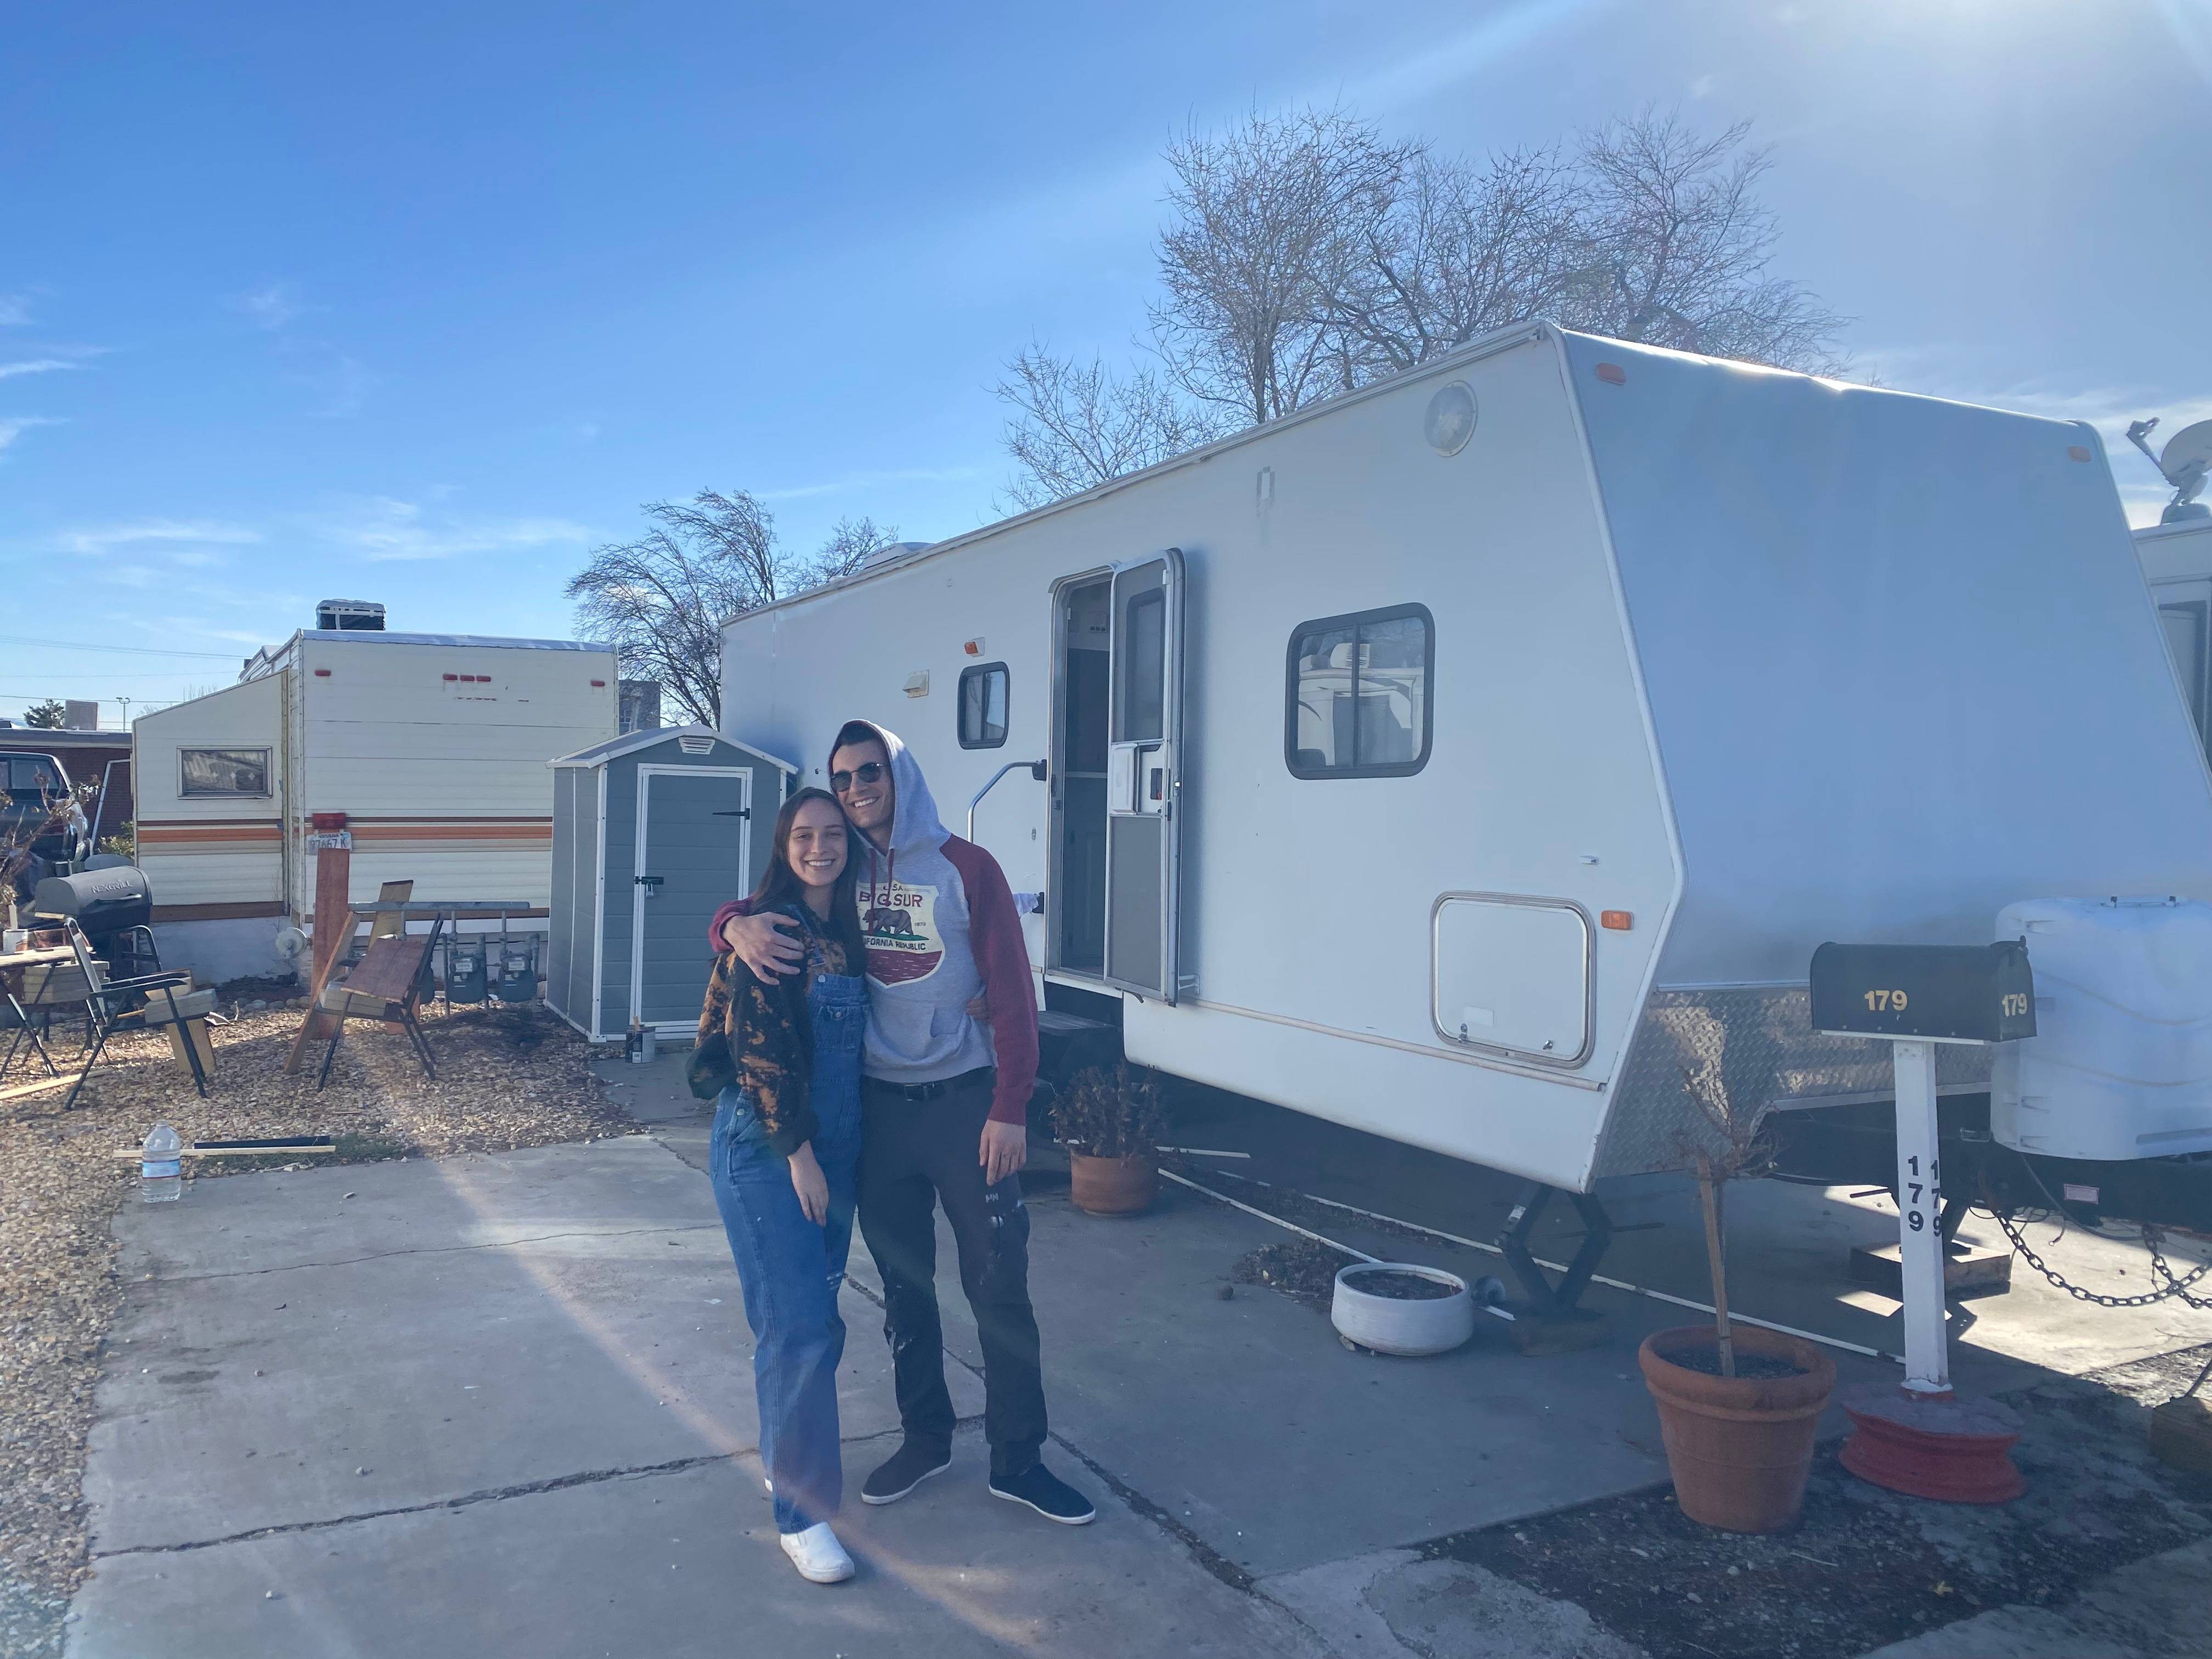
I still chose to live in a travel trailer with my now wife.

Not because it was noble.

Honestly, because I was scared of wasting a rare window.

What surprised me most back then wasn’t the money.

It was how differently people I respected thought about it.

The people who were already where I wanted to be didn’t care what I drove or where I lived.

They paid attention to my choices and work ethic. 

What I said no to.What I was willing to delay.

That year, I saved and invested more than half my income.

Not because I was disciplined.

But because I made the decision early, before lifestyle creep had a vote.

Since then, I’ve had conversations with incredibly successful professionals.

People who earn far more than I did back then.

And are still trying to create financial flexibility later in life.

It made something click for me.

Income definitely matters.

But behavior matters far more.

Living lean isn’t about “doing without.”

It’s about being intentional.

Spending on what actually improves your life and aligns with your goals.

And cutting what quietly locks you into needing more.

I don’t think simple living is the answer for everyone.

But I do think clarity is.

And clarity gets a lot easier when your lifestyle isn’t doing the talking for you.

P.S. I’m curious, what’s one expense you kept on purpose because it truly mattered to you?
1Reply
250 views

Most Popular Reply

Chris SeveneyBusiness Member
Moderator
Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
9mo

I am going to take a different approach as I have someone in my family who grew up under a communist regime and did not have anything and now they live in US, make $300k+ a year and are very good with there money and spend it wisely. They live in a $2M+ home (due to appreciation and of course have a very low mortgage and mortgage rate) and go on vacation when they want and have great savings. I would not consider them financially independent but enjoying life.

They also have a different mindset because they lost a parent at a young age and reality is we do not know when our day is done and we cannot take money with us. 

So I am not knocking this post in any way, people need to be financially literate and do very well managing their money and I applaud what the original poster has done, but everyone in life has different goals and there are many "right ways" you can go about living life.

7e investments53 Reviews
See this reply in the discussion

13 Replies

Jump to latestLatest
  • G. Brian DavisPro Member
    Investor · Hatboro, PA · Member since 2016 · 3k+ posts · 891 votes
    9mo

    This really resonates. I’ve seen the same thing over time, income helps, but behavior and structure are what actually create freedom. In my case, I’ve taken a similar intentional approach by investing through a co-investing club, spreading smaller amounts of capital across larger deals instead of inflating lifestyle or chasing single wins. That clarity around where money goes has mattered far more than how much comes in.

    • Jake AndronicoBusiness Member
      OP
      Realtor · Reno, NV · Member since 2019 · 1k+ posts · 938 votes
      9mo
      Quote from @G. Brian Davis:

      This really resonates. I’ve seen the same thing over time, income helps, but behavior and structure are what actually create freedom. In my case, I’ve taken a similar intentional approach by investing through a co-investing club, spreading smaller amounts of capital across larger deals instead of inflating lifestyle or chasing single wins. That clarity around where money goes has mattered far more than how much comes in.

      Appreciate it! And yes, agreed :) 
  • Lender · Lake Geneva WI, USA · Member since 2023 · 141 posts · 72 votes
    9mo

    Truly, a modern Diogenes 

  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    9mo

    I am going to take a different approach as I have someone in my family who grew up under a communist regime and did not have anything and now they live in US, make $300k+ a year and are very good with there money and spend it wisely. They live in a $2M+ home (due to appreciation and of course have a very low mortgage and mortgage rate) and go on vacation when they want and have great savings. I would not consider them financially independent but enjoying life.

    They also have a different mindset because they lost a parent at a young age and reality is we do not know when our day is done and we cannot take money with us. 

    So I am not knocking this post in any way, people need to be financially literate and do very well managing their money and I applaud what the original poster has done, but everyone in life has different goals and there are many "right ways" you can go about living life.

    7e investments53 Reviews
    • Jake AndronicoBusiness Member
      OP
      Realtor · Reno, NV · Member since 2019 · 1k+ posts · 938 votes
      9mo
      Quote from @Chris Seveney:

      I am going to take a different approach as I have someone in my family who grew up under a communist regime and did not have anything and now they live in US, make $300k+ a year and are very good with there money and spend it wisely. They live in a $2M+ home (due to appreciation and of course have a very low mortgage and mortgage rate) and go on vacation when they want and have great savings. I would not consider them financially independent but enjoying life.

      They also have a different mindset because they lost a parent at a young age and reality is we do not know when our day is done and we cannot take money with us. 

      So I am not knocking this post in any way, people need to be financially literate and do very well managing their money and I applaud what the original poster has done, but everyone in life has different goals and there are many "right ways" you can go about living life.

      Personal finance is absolutely personal :) Good for them!!
  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    9mo

    OP.  Not sure of the purpose of your post.  

    My direct serious response to your question is Almond Joy bars.  I buy one about every 3 months.   But that doesn’t help you to financial freedom.  

    1.   How old are you?  To establish timeline to 40.

    2.  How much will you consistently save annually to invest?

    3.  Define financial freedom in lifestyle and dollar terms.  For example.  If you have $90,000 you have financial freedom now.  But the lifestyle probably won’t match your objective.  
    4. REI and other investment strategy. To achieve your target.

    The above are the concepts you need to nail down.    

    • Jake AndronicoBusiness Member
      OP
      Realtor · Reno, NV · Member since 2019 · 1k+ posts · 938 votes
      9mo
      Quote from @Henry Clark:

      OP.  Not sure of the purpose of your post.  

      My direct serious response to your question is Almond Joy bars.  I buy one about every 3 months.   But that doesn’t help you to financial freedom.  

      1.   How old are you?  To establish timeline to 40.

      2.  How much will you consistently save annually to invest?

      3.  Define financial freedom in lifestyle and dollar terms.  For example.  If you have $90,000 you have financial freedom now.  But the lifestyle probably won’t match your objective.  
      4. REI and other investment strategy. To achieve your target.

      The above are the concepts you need to nail down.    

      Putting my goal in writing and sharing it, as well as sharing what I've observed. If you don't agree or it doesn't resonate with you, that's completely OK :) 

      1. I'll be 29 years old in May. 
      2. My goal is to save $100K per year. I was able to hit it last year. 
      3. $2mil in assets (mix of real estate and stocks) producing 5-6% net per year, or about $10K per month "passively". 
  • V.G JasonPro Member
    Investor · Member since 2022 · 3k+ posts · 3k+ votes
    9mo

    What expense I kept on purpose because it really mattered to me?

    Unfortunately, food. Bad food.

    With that said, I'm not against your post but it does trigger me because most people seek this and they need to be careful what they're asking for. Obviously, it can work. I "retired" young-ish, and couldn't take it for very long. My nature is to work. 

    Behavior is important, but it could be said finances are more that than mathematical but we're on a REI board where fabricated pro-formas/inputs and the FOMO contest it deeply.

    • Jake AndronicoBusiness Member
      OP
      Realtor · Reno, NV · Member since 2019 · 1k+ posts · 938 votes
      9mo
      Quote from @V.G Jason:

      What expense I kept on purpose because it really mattered to me?

      Unfortunately, food. Bad food.

      With that said, I'm not against your post but it does trigger me because most people seek this and they need to be careful what they're asking for. Obviously, it can work. I "retired" young-ish, and couldn't take it for very long. My nature is to work. 

      Behavior is important, but it could be said finances are more that than mathematical but we're on a REI board where fabricated pro-formas/inputs and the FOMO contest it deeply.

      Not trying to be triggering :) I have two rental properties and I am no longer in private equity. 

      I'm an investment agent in Reno for 1-10 unit properties. 

      And yes, everyone is different. That's why I said financially independent, not necessarily not working. I'm the same way, my nature is to work as well. 

      I wish you the best of luck and congrats on where you're at!
  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    9mo

    OP

    1.  For 4 or 5 years now, you have saved about $500,000 not counting increases.......

    2. Since this is an REI forum. You should have in the range of: A. 25% down on $500,000 or $2mm of investments using commercial terms, or B. 10% down SBA on $500,000 or $5mm of investments using SBA terms.

    3.  Whether your there yet or not doesn't matter, just gives a bandwidth for discussion.

    4. I don't recommend all REI or all Stocks, so split based on your diversification risk model.

    5. By now, if you have been investing in REI, you should have started to either narrow down your REI approach and started to perfect it or identified a new REI approach.

    6.  You should build a model from your assets today to your age 40 goal.  This will test if your investment model gets you there, along with your personal savings.

    7. Your $2mm target at 40 is a net asset number. You will use REI either Cash flow or Appreciation approach or both to achieve your target.

    8.  Since you're in Private equity the above thought process and projections will be easy for you.  You will know ahead of time if you will hit your target or if you need to adjust your approach.

    9. If your plan is to save $90k to $100k from age 24 to 40; to achieve $2mm net assets. There really isn't a need for discussion. And if that is your plan, I would not recommend getting into REI, not worth the learning curve or risk.

    10. Depending on your world view. I would adjust the $2mm target upwards. Right now, my view of $2mm by the time your 40; will only be worth about $1mm in today's buying power. And even then, the passive 5 to 6% net return will be a true negative 4% due to inflation and dollar devaluation. For example, 2025 we earned around 5% on our cash equivalents, but actually lost 5% net after currency devaluation. Luckily you have access to a lot of great economic thinking. I would recommend you do a model, good, better, best or H/M/L against both your wealth creation and your year 40 wealth and what it is worth. Again, hitting your $2mm target at 40 is pretty easy. I would not get into REI to achieve that.

    11.  I would treat your year 40 as a retirement age, even though you shouldn't.  As you get close to it, you will need to switch over to Wealth protection to a larger percentage.  

    Have fun on the Journey.

    • Jake AndronicoBusiness Member
      OP
      Realtor · Reno, NV · Member since 2019 · 1k+ posts · 938 votes
      9mo
      Quote from @Henry Clark:

      OP

      1.  For 4 or 5 years now, you have saved about $500,000 not counting increases.......

      2. Since this is an REI forum. You should have in the range of: A. 25% down on $500,000 or $2mm of investments using commercial terms, or B. 10% down SBA on $500,000 or $5mm of investments using SBA terms.

      3.  Whether your there yet or not doesn't matter, just gives a bandwidth for discussion.

      4. I don't recommend all REI or all Stocks, so split based on your diversification risk model.

      5. By now, if you have been investing in REI, you should have started to either narrow down your REI approach and started to perfect it or identified a new REI approach.

      6.  You should build a model from your assets today to your age 40 goal.  This will test if your investment model gets you there, along with your personal savings.

      7. Your $2mm target at 40 is a net asset number. You will use REI either Cash flow or Appreciation approach or both to achieve your target.

      8.  Since you're in Private equity the above thought process and projections will be easy for you.  You will know ahead of time if you will hit your target or if you need to adjust your approach.

      9. If your plan is to save $90k to $100k from age 24 to 40; to achieve $2mm net assets. There really isn't a need for discussion. And if that is your plan, I would not recommend getting into REI, not worth the learning curve or risk.

      10. Depending on your world view. I would adjust the $2mm target upwards. Right now, my view of $2mm by the time your 40; will only be worth about $1mm in today's buying power. And even then, the passive 5 to 6% net return will be a true negative 4% due to inflation and dollar devaluation. For example, 2025 we earned around 5% on our cash equivalents, but actually lost 5% net after currency devaluation. Luckily you have access to a lot of great economic thinking. I would recommend you do a model, good, better, best or H/M/L against both your wealth creation and your year 40 wealth and what it is worth. Again, hitting your $2mm target at 40 is pretty easy. I would not get into REI to achieve that.

      11.  I would treat your year 40 as a retirement age, even though you shouldn't.  As you get close to it, you will need to switch over to Wealth protection to a larger percentage.  

      Have fun on the Journey.

      OK, thank you :) 
  • Member since 2025 · 324 posts · 121 votes
    9mo

    I’m curious, what’s one expense you kept on purpose because it truly mattered to you?

    A lot.

    But one expense we regret is the fishing yacht my husband bought. Each month it costs him $300 to store. And he is so busy that he only used that boat less than 15 times after 5 years.

    • Jake AndronicoBusiness Member
      OP
      Realtor · Reno, NV · Member since 2019 · 1k+ posts · 938 votes
      9mo
      Quote from @Ying Tang:

      I’m curious, what’s one expense you kept on purpose because it truly mattered to you?

      A lot.

      But one expense we regret is the fishing yacht my husband bought. Each month it costs him $300 to store. And he is so busy that he only used that boat less than 15 times after 5 years.

      Ahhh gotcha. That's a bummer. Using it 3 times a year is a lot more than most though! 

      Sounds like it's probably an easy fix if it's worth the hassle to sell :) 
Join the conversationCreate a free account to reply, vote on answers and follow this thread.