Ranting and raving about mortgages in the time of COVID19

Ranting and raving about mortgages in the time of COVID19

Realtor · Boston, MA · Member since 2019 · 244 posts · 275 votes


Use other people's money, they said. Leverage, they said. Harumph.

Mortgage 1: My personal residence (duplex) in Boston. With rates low, my promo rate on the HELOC expiring, a bunch of exterior renovations I want to do, and prices at an all time high in Boston, I thought February was the perfect time to refi. I called my private banker (sidebar: switching to a private bank was the best business move I've made in years), he put me in touch with his mortgage guy, I got a great rate, low fees, we're off to the races. This is a plain vanilla cash out refi 30 year, except it's Boston so it's a jumbo loan because even a 1 bedroom fixer in Boston is a jumbo loan. We submitted the application the end of Feb.

Then COVID19 hits, things got delayed, but I have a great bank, no problem, it will just take a little bit longer...and then one of my tenants gets sick and another one says he only has one lung and they don't want the appraiser to walk through, and the mayor issues a statement backing up tenants in exactly this kind of situation and my hands are tied. The appraiser gets hard to deal with because she's "essential" and she's upset that she has to work from the pictures my tenants took instead of walking through their unit and I can see things going sideways. And all of a sudden my appraisal comes in a full $300K below what we anticipated, which translates to us getting only 1/3 the cash out of the loan we'd planned on. And of course, when you appeal an appraisal it just goes back to the same appraiser, so we're SOL. My banker breaks the news that if I don't close this loan he may never be able to give me another one because I am pretty much the last jumbo loan that will ever close in America, especially at pre-COVID rates, so I hold my nose and do it. The world is ending and even 1/3 of my planned cash is better than no cash, but now we can't afford to do the renovations we'd planned on and I just reset my 30 year clock and paid thousands in fees and it took 9 weeks...but at least the loan is done. Only we still don't have the funds, that won't happen for another week for some reason. So I am still anxious until I see them hit my account.

Loan 2: Your basic BRRRR. 2 units we bought in SE TX in the fall. As with all rehabs, it took too long and cost too much, but we got it done. Now I just need to refi and place tenants. Started in January working with a local CU, upset that they gave me 4.5% when I wanted 3.9, but it's not a huge loan and I want a local banking relationship and already have a loan with them on another property. They promise closing in 4 weeks. 6 weeks later, on the first really scary COVID day as the markets are cratering, just a few days before closing, they call me up with some BS excuse about not being able to lend to out of state owners (remember, I already have a loan with them on another property) and cancel the loan. They even have the gall to try to get me to pay for the appraisal they ordered. I refuse and they back down. So much for me trying to build a relationship with a local lender. Strike 1.

No biggie, I am working with a HML on some other stuff, he's great. He quotes me 5.8% and tells me it will be done in 2 weeks. I just want to pay off my private money lender at 9% who is a personal friend, so I'm happy. This is crazy low for HML. Then he tells me the rates have dropped, which is also unheard of. He quotes me 5.5% at 70% LTV and I am overjoyed. We move forward, but he's getting cagey. Then two weeks later he sends me new terms with rates closer to 6% and no more than 60% LTV and a full year's payments in escrow, plus all kinds of fees. By the time they're done, I barely have enough left to pay off my private loan. Pandemic or not, this deal sucks and I walk. Strike 2.

I ask my friend if she will just refinance at 5.5% over 10 years, or pretty much whatever terms she wants. She thinks it over and says no. The markets have spooked her and she wants her money back. Strike 2.5

My PM knows someone, he swears she's great. I call her on March 23 and ask her if she can help. She promises she can get the deal done and be closed by the end of April at conventional rates. She's cagey on the rates but I let it slide. Desperate times and all. It's a full doc loan. Weeks go by, we provide mountains of documents, I ask for rates and terms a half dozen times and never get a straight answer. She's making me nervous. We finally get a handwritten PDF today with rates and terms and she's got me at 4.875 and $6900 in fees on a $140k loan. And she won't take the appraisal I just got from the credit union at the beginning of March, so now I have to sit here and stress that this appraisal will also come in crazy low while also being bent out of shape that I'm getting nearly hard money rates on a full doc loan. Maybe I should have just gone with the HML at 60% LTV, at least I'd be liquid by now. Oh, and we haven't placed a tenant for the larger unit yet after 2 months on the market, which makes me even more nervous for the appraisal. My PM says showings are down 75% across the board.

And here I sit, waiting for strike 3...

0Reply
24 views

Most Popular Reply

Jay HinrichsBusiness Member
Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
6y

@Chris Mason  it was quite common in years past that local banks and credit unions would not loan on rentals to anyone who lived more than 100 miles from the property..  RISK  reasons.. more defaults with out of area borrowers. its only been the last 5  or 6 years that they kind of looked the other way on that stip.. but now it appears its coming back. As I have seen two other posts on BP with the same issue ..

See this reply in the discussion

14 Replies

Jump to latestLatest
  • Chris MasonPro Member
    Moderator
    Lender · CA · Member since 2015 · 9k+ posts · 10k+ votes
    6y

    Loan 1 - That was self imposed. If an appraiser wants to take a bath in your bathtub, and you want that refi appraised value, then you let them take a bath in your bathtub, or there went your appraised value. It sucks, but it is what it is.

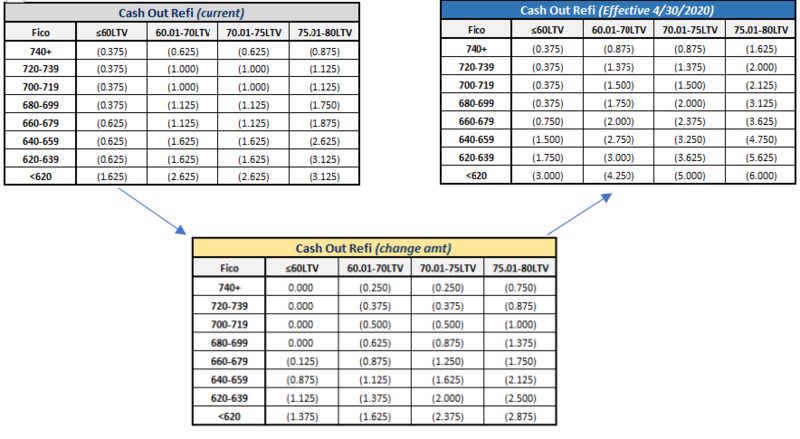
    Loan 2 - Yup, wonky stuff like that was going on for a bit. Lots of anecdotes about absurd/implausible reasons for denying cash out refis. Some of our partner lenders are still doing them, others have made them more expensive, or stopped entirely, and everything in between. Here's the updated cash out pricing hits from one of our partner lenders, who have taken the strategic decision to be super strong in the purchase mortgage segment at the expense of the cash out refi segment (I can respect that, it's fairly transparent to me as a mortgage broker, and I just know not to use them for cash out refis that they clearly do not want anyways). This bank has captive vendor W2 employee retail direct loan officers who can ONLY offer that bank's mortgage products, I'm glad that I'm not one of them!

    Loan 3 - Yup, HML are getting more conservative. Naturally. How could they do otherwise? This pandemic is bigger than you or me. I personally don't do HML deals, but I'm from clients across the board that HML rates/terms/points/fees have gone to crap (or, really, they went back to where they always are when Wall Street isn't buying the paper).

  • Rental Property Investor · Durham, NC · Member since 2016 · 7k+ posts · 7k+ votes
    6y

    @Jason Turgeon strike three is probably another canceled loan. Things are going to be like this for a while. Buckle up

  • Rental Property Investor · Clarksville, TN · Member since 2016 · 1k+ posts · 1k+ votes
    6y

    @Jason Turgeon

    Have you and your friend looked at writing a longer term note and selling it so she can recoup her principal?

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    6y

    @Chris Mason  it was quite common in years past that local banks and credit unions would not loan on rentals to anyone who lived more than 100 miles from the property..  RISK  reasons.. more defaults with out of area borrowers. its only been the last 5  or 6 years that they kind of looked the other way on that stip.. but now it appears its coming back. As I have seen two other posts on BP with the same issue ..

  • Property Manager · Ketchum, ID · Member since 2016 · 277 posts · 132 votes
    6y

    Had the same sequence of problems and it was highlighted by the appraiser. Since Dodd Frank and Sarbains Oxley, banks have to order appraisals and no one can choose the appraiser. As a result, there are many very bad appraisers that get work regularly regardless whether they are accurate or "good" at what they do. We need to lobby for that to be changed for sure as a group I think. Our experience was that the first loan fell through because the interest rate went up to 8.2%. I bailed. But the appraisal was at market and well done. No longer can we reuse appraisals done within 6 months as we could before. So the appraiser win big time. (that also has to be changed at the congressional level). So we finally got a good rate with 70% LTV and had to have another appraisal. This guy presented wrong information about the property in terms of square footage, number of rooms, left off the second rental unit and came in $350K less value than the previous appraiser had given with apples to apples comps. This new appraiser used apples to oranges comps in a different city about 70 miles away. I had the lender point out the differences and ask for a reconsideration. The appraiser refused. I had no other option but to get another appraisal. This one came back at the same value as the first one with correct data. So I did a chargeback on the second appraisal and presented the wrong information with comparisons of the first two appraisals. The credit card company sent a query and the appraisal company lied to them saying that we had signed an agreement no to charge back the fee under any circumstance. We had not signed any such thing. We had only allowed our lender to have our credit card charged. Our lender send info stating that he felt the appraisal was poorly done, a month late in delivery and did not correctly reflect the value of the property. Still the credit card company would not consider the charge back.

    Summation:  There is no protection for property owners from the appraisal industry where there are clearly people who want to control the price of properties and hold the keys when people are trying to buy or refi properties.  It happens for residential and commercial properties.  These people are giving opinions of value. There is no science to it.  It would be very helpful to have input into how the laws governing this industry so that those who are not good at what they do or try to control a situation, are able to be weeded out.  I am sorry you are having so much trouble.  It is a jungle out there for sure.

  • Realtor · Boston, MA · Member since 2019 · 244 posts · 275 votes
    6y

    @Chris Mason I expected a slight discount but $300k is absurd. She was able to walk through our unit and the outbuildings and got pictures of their unit. I also gave her past appraisals and architectural drawings. She came in almost 30% below what I expected, and almost $200k below the appraisal we got 2 years ago, and since then we've done about $30k of work and the market has appreciated. Being conservative is one thing, being punitive is another. Our bank approved the remote appraisal, after all. And had the tenants complained to the city, I would be in court. Boston is not joking around with tenant protections during this. After the loan is funded I will be filing a complaint with our state board. 

  • Realtor · Boston, MA · Member since 2019 · 244 posts · 275 votes
    6y

    @Todd I would have been happy to do that but this is her first foray into private lending and she's a good friend. She's not comfortable with the more sophisticated techniques yet, so I just want to pay her back quickly. 

  • Appraiser · Chicago area · Member since 2020 · 36 posts · 15 votes
    6y
    Originally posted by @Timmi Ryerson:

    Had the same sequence of problems and it was highlighted by the appraiser. Since Dodd Frank and Sarbains Oxley, banks have to order appraisals and no one can choose the appraiser. As a result, there are many very bad appraisers that get work regularly regardless whether they are accurate or "good" at what they do. We need to lobby for that to be changed for sure as a group I think. Our experience was that the first loan fell through because the interest rate went up to 8.2%. I bailed. But the appraisal was at market and well done. No longer can we reuse appraisals done within 6 months as we could before. So the appraiser win big time. (that also has to be changed at the congressional level). So we finally got a good rate with 70% LTV and had to have another appraisal. This guy presented wrong information about the property in terms of square footage, number of rooms, left off the second rental unit and came in $350K less value than the previous appraiser had given with apples to apples comps. This new appraiser used apples to oranges comps in a different city about 70 miles away. I had the lender point out the differences and ask for a reconsideration. The appraiser refused. I had no other option but to get another appraisal. This one came back at the same value as the first one with correct data. So I did a chargeback on the second appraisal and presented the wrong information with comparisons of the first two appraisals. The credit card company sent a query and the appraisal company lied to them saying that we had signed an agreement no to charge back the fee under any circumstance. We had not signed any such thing. We had only allowed our lender to have our credit card charged. Our lender send info stating that he felt the appraisal was poorly done, a month late in delivery and did not correctly reflect the value of the property. Still the credit card company would not consider the charge back.

    Summation:  There is no protection for property owners from the appraisal industry where there are clearly people who want to control the price of properties and hold the keys when people are trying to buy or refi properties.  It happens for residential and commercial properties.  These people are giving opinions of value. There is no science to it.  It would be very helpful to have input into how the laws governing this industry so that those who are not good at what they do or try to control a situation, are able to be weeded out.  I am sorry you are having so much trouble.  It is a jungle out there for sure.

    Actually, there are "appraisal waivers" out there, so the six month rule is not necessarily a thing.  There are many factors.  As to 70 miles away, I'd be interested to hear how rare a property this is that would be needed.  Thanks for the tip on the chargeback, I'll be sure to get agreements in place where needed.  You are owed an appraisal that reflects accurate information, but you are not owed any predetermined value.  I don't care about holding any keys and you are correct in implying that it is not a perfect science.  If a lender retains poor appraisers, move to a more reputable lender.  It is the lender's job to weed out appraisers and they have the authority to do so, but not because an appraiser did not provide you with a value to make your deal work.  That is not their job.  If you have a weird or rare property, do extra homework and provide good comps to the appraiser at the time of inspection, or even before. 

  • Property Manager · Ketchum, ID · Member since 2016 · 277 posts · 132 votes
    6y

    @josephhdifranco:  Appreciate your comments.  Iot is a 2 acre property in a neighborhood of 35 1 acre single family homes with comps as close as across the street and everywhere within a 2 mile range.  So no, nothing special except that it is a log home with rental over the garage and a horse facility and pastures.  But there are many log homes in the area.  Some have rental units and several also have horse facilities. The comps were available to the appraiser who chose to go to a different city where log homes are rare.  This was truly a disparate report which will be reported to the state board governing appraisers.  

  • Chris MasonPro Member
    Moderator
    Lender · CA · Member since 2015 · 9k+ posts · 10k+ votes
    6y
    Originally posted by @Jason Turgeon:

    @Chris Mason I expected a slight discount but $300k is absurd. She was able to walk through our unit and the outbuildings and got pictures of their unit. I also gave her past appraisals and architectural drawings. She came in almost 30% below what I expected, and almost $200k below the appraisal we got 2 years ago, and since then we've done about $30k of work and the market has appreciated. Being conservative is one thing, being punitive is another. Our bank approved the remote appraisal, after all. And had the tenants complained to the city, I would be in court. Boston is not joking around with tenant protections during this. After the loan is funded I will be filing a complaint with our state board. 

     You aren't my client, but if you were then I'd invite you to double down on that bet, it sounds like there's a strong case for you being right. The way I'll handle it: If we order another independent appraisal (not doing anything funky, we never get to cherry pick) and it comes in close to what you were expecting allowing us to get to the closing table, then you win, I'll comp you the cost of the first. If it doesn't, well, at some point we have to find another solution.

    See if your LO does something like that. 

  • Chris MasonPro Member
    Moderator
    Lender · CA · Member since 2015 · 9k+ posts · 10k+ votes
    6y
    Originally posted by @Jay Hinrichs:

    @Chris Mason  it was quite common in years past that local banks and credit unions would not loan on rentals to anyone who lived more than 100 miles from the property..  RISK  reasons.. more defaults with out of area borrowers. its only been the last 5  or 6 years that they kind of looked the other way on that stip.. but now it appears its coming back. As I have seen two other posts on BP with the same issue ..

    Interesting, and by the way it was good to listen in on that podcast you were a guest on yesterday, even if @Jason Hsiao did kind of put me on the spot. :P

    Was this 100 mile requirement an overlay for folks doing Fannie type loans, or was this non-agency paper? 

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    6y
    Originally posted by @Chris Mason:
    Originally posted by @Jay Hinrichs:

    @Chris Mason  it was quite common in years past that local banks and credit unions would not loan on rentals to anyone who lived more than 100 miles from the property..  RISK  reasons.. more defaults with out of area borrowers. its only been the last 5  or 6 years that they kind of looked the other way on that stip.. but now it appears its coming back. As I have seen two other posts on BP with the same issue ..

    Interesting, and by the way it was good to listen in on that podcast you were a guest on yesterday, even if @Jason Hsiao did kind of put me on the spot. :P

    Was this 100 mile requirement an overlay for folks doing Fannie type loans, or was this non-agency paper? 

    local banks doing portfolio loans..  back in the day when country wide was going great funs you could live anywhere of course.

  • Realtor · Boston, MA · Member since 2019 · 244 posts · 275 votes
    6y

    @Chris Mason Unfortunately my bank wouldn't allow me to request another appraisal, even if I paid for both. And my rate lock was set to expire this week so I was over a barrel - if I rolled the dice with a new loan and a new appraisal, I'd be guaranteed a much higher rate and higher closing costs on top of it. We closed on Tuesday with the low value just to guarantee ourselves at least some cash on hand during the uncertainty ahead. But I am nowhere near the cash position I wanted to be in, and will have to defer the majority of the much-needed renovations we were planning on doing. 

  • Chris MasonPro Member
    Moderator
    Lender · CA · Member since 2015 · 9k+ posts · 10k+ votes
    6y
    Originally posted by @Jason Turgeon:

    @Chris Mason Unfortunately my bank wouldn't allow me to request another appraisal, even if I paid for both. And my rate lock was set to expire this week so I was over a barrel - if I rolled the dice with a new loan and a new appraisal, I'd be guaranteed a much higher rate and higher closing costs on top of it. We closed on Tuesday with the low value just to guarantee ourselves at least some cash on hand during the uncertainty ahead. But I am nowhere near the cash position I wanted to be in, and will have to defer the majority of the much-needed renovations we were planning on doing. 

     Ah, I guess a difference worth noting on the broker side... when I do what I described above, we're switching lenders too. I'm not bound to one.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.