Cash out refinance in an LLC

Cash out refinance in an LLC

Investor · Shelton, CT · Member since 2016 · 218 posts · 225 votes

Hi BP Community,

My partners and I are looking to pull out equity of our investment property to move on to our next purchase. Shortly after we purchased two and a half years ago we did a quit claim from the mortgage in one of the 3 partner's name to our LLC. If we do a refi can we do it under the LLC's name or does the deed need to be switched back to that partner's name as his wife is suggesting? As stated, we closed on the property in August of 2018.

Thank you in advance!

1Reply
100 views

Most Popular Reply

Stephanie P.Pro Member
Washington, DC Mortgage Lender/Broker · Member since 2016 · 4k+ posts · 2k+ votes
5y
Originally posted by @Jeff Piscioniere:

Hi BP Community,

My partners and I are looking to pull out equity of our investment property to move on to our next purchase. Shortly after we purchased two and a half years ago we did a quit claim from the mortgage in one of the 3 partner's name to our LLC. If we do a refi can we do it under the LLC's name or does the deed need to be switched back to that partner's name as his wife is suggesting? As stated, we closed on the property in August of 2018.

Thank you in advance!

I would refinance it in the LLC and leave things alone. The conventional financing on this will be arduous given the number of owners/partners and rates on the no income verification loans that will close this in the LLC are in the 4's and 5's on the high side at 75% ltv. Save yourself some hassle and just get a DSCR loan. You can go up to 80% on a rate and term, but if cash out is the goal, 75% will be your max with a decent rate.

I don't know how much the loan amount is, but on a 200K loan at 3.875% (Fannie rate as of yesterday on an investor, cash out, refinance with 6 months on title, 750 mid score) the principal and interest payment is $940. Cash out on a 200K loan at 75% with a 740 mid score, same 6 months on title is 4.5% and 2 points, but it stays in the LLC and you don't need to take it in and out. Monthly payment on that one is $1013. I know $73 and the 2 points can be a lot of money over time, but with multiple borrowers and multiple sets of tax returns and taking the ownership out of the LLC and then putting it back in later, it seems the risk and hassle aren't going to be worth the cost (at least to me).

One girl's perspective

Stephanie

See this reply in the discussion

5 Replies

Jump to latestLatest
  • Greg ScottPro Member
    Rental Property Investor · SE Michigan · Member since 2014 · 4k+ posts · 6k+ votes
    5y

    No, you do not need to switch the deed back to your partners name. There are plenty of banks that will offer you a cash out refi directly to the LLC. But, if you want a conventional mortgage, you cannot do it in an LLC. Also, if you decide to transfer the deed, you start a 6 month season period before you can do a cash-out refi.

  • Investor · Shelton, CT · Member since 2016 · 218 posts · 225 votes
    5y

    @Greg Scott so conventional loan vs what exactly? And thanks for that 6 month seasoning item. That I did not know nor do I think my partners did.

  • Lender · Nationwide Lender · Member since 2019 · 391 posts · 140 votes
    5y

    Hi Jeff,

    To get the best terms typically you will want to go conventional financing. Doing this you will need to get the property back into your personal name by doing a quit claim deed. Its a simple document and is very inexpensive. Once the refinance is done you have the freedom to put the property back into the LLC with another quit claim deed. This is a very common practice and is not hard to do, typically a lender can help you facilitate it. Hope this helps, let me know if you have any other questions.

  • Lender · Winlock, WA · Member since 2013 · 1k+ posts · 1k+ votes
    5y

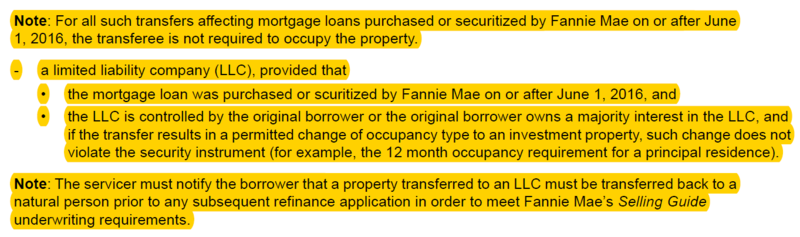
    If you do the cash out refinance as a Fannie Mae loan, you can then transfer the title to an LLC that the borrowers on the loan, are the majority members of. Fannie changed this rule back on 6/1/2016 to allow this without it violating the "Due on Sale" clause.
  • Stephanie P.Pro Member
    Washington, DC Mortgage Lender/Broker · Member since 2016 · 4k+ posts · 2k+ votes
    5y
    Originally posted by @Jeff Piscioniere:

    Hi BP Community,

    My partners and I are looking to pull out equity of our investment property to move on to our next purchase. Shortly after we purchased two and a half years ago we did a quit claim from the mortgage in one of the 3 partner's name to our LLC. If we do a refi can we do it under the LLC's name or does the deed need to be switched back to that partner's name as his wife is suggesting? As stated, we closed on the property in August of 2018.

    Thank you in advance!

    I would refinance it in the LLC and leave things alone. The conventional financing on this will be arduous given the number of owners/partners and rates on the no income verification loans that will close this in the LLC are in the 4's and 5's on the high side at 75% ltv. Save yourself some hassle and just get a DSCR loan. You can go up to 80% on a rate and term, but if cash out is the goal, 75% will be your max with a decent rate.

    I don't know how much the loan amount is, but on a 200K loan at 3.875% (Fannie rate as of yesterday on an investor, cash out, refinance with 6 months on title, 750 mid score) the principal and interest payment is $940. Cash out on a 200K loan at 75% with a 740 mid score, same 6 months on title is 4.5% and 2 points, but it stays in the LLC and you don't need to take it in and out. Monthly payment on that one is $1013. I know $73 and the 2 points can be a lot of money over time, but with multiple borrowers and multiple sets of tax returns and taking the ownership out of the LLC and then putting it back in later, it seems the risk and hassle aren't going to be worth the cost (at least to me).

    One girl's perspective

    Stephanie

Join the conversationCreate a free account to reply, vote on answers and follow this thread.