Once again: cost segregation hype

Once again: cost segregation hype

Michael PlaksPro Member
Tax Accountant / Enrolled Agent · Houston, TX · Member since 2014 · 5k+ posts · 6k+ votes

I have written about over-selling of cost segregation before. I will indulge myself one more time. 

See, cost segregation is indeed wonderful when it works. The problem is: it does not always work. But when you see it marketed online, including here on Bigger Pockets, the  impression you get is that it is pure magic, easily available to all, like on Oprah shows.

Examples are poached from a very prominent tax firm specializing in real estate.

Example A.
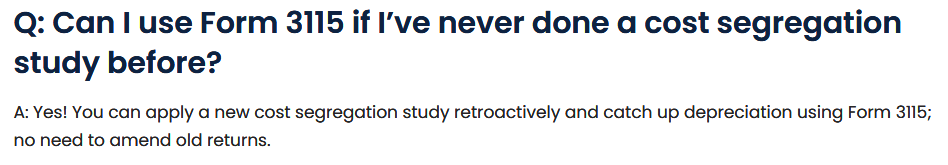
Is this a true statement? Yes. But it is an incomplete statement. It is missing an, ahem, minor detail: most cost segregation losses are blocked by PAL (passive activity limitation) rules. You need to qualify for one of the two exceptions: either operate STRs (short-term rentals) or meet the REPS (real estate professional status) requirements. Many investors do not qualify for either.

Example B.
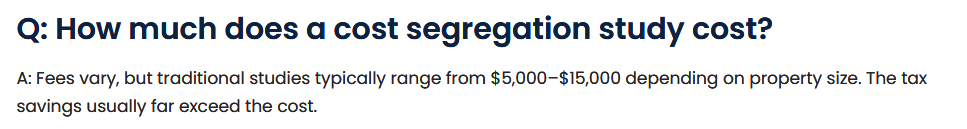
Again, kind of a true statement. Again, missing critical details. Such as this one: the tax savings are not permanent. They are temporary, as in a loan. You have to return these tax savings when you sell the property without a 1031 exchange. 

Another missing part: the savings are for one year only. After that, you are back to where you were, unless you buy another property and apply cost segregation to your new one.

I am all FOR cost segregation. I fully support it and recommends it to my clients. WHEN IT IS APPROPRIATE. Which is not always.

Here are some of my older posts on cost segregation:

https://www.biggerpockets.com/forums/51/topics/1075919-five-...
https://www.biggerpockets.com/forums/51/topics/831924-beware...
https://www.biggerpockets.com/forums/51/topics/1136752-expla...
https://www.biggerpockets.com/forums/51/topics/1191846-cauti...
https://www.biggerpockets.com/forums/51/topics/831924-beware...

4Reply
245 views

Most Popular Reply

Henry ClarkPro Member
Developer · Member since 2020 · 4k+ posts · 4k+ votes
1mo

I would treat it as an interest free loan or to offset higher income for the year.  

As a loan I would ask myself what would I do with the money the next 5 years?  If I can do 1 or 2 more deals and double triple my money then any future depreciation recapture or higher taxes due to less deductions is well worth it.  

If I treat it as a one time tax reduction due to higher income from other sources I would look at my tax bracket savings if any.  Although you could go thru the expense to refile returns.  But again treat it as a loan.  

If I was going to do it just to reduce taxes, and not invest the tax savings in a high return investment then I wouldn’t do it.  

One time we did so we could keep scaling. Doing either 100% or 400% COC returns in 2 years. Another time we had a farm land sale gain we offset.


This does play into any future sale of those two properties.  As far as timing or not scaling at the moment.   Or rolling via 1031 or scaling and reinvesting into another property where we didn’t write off again.  

See this reply in the discussion

9 Replies

Jump to latestLatest
  • Brett P SwartsPro Member
    Specialist · SAINT AUGUSTINE · Member since 2017 · 270 posts · 27 votes
    1mo

    Michael - great points here, especially #2. Timing is the most important factor in investing and tax deferral. If when you sell it all goes back then you need to be careful to budget your time horizon. 1031 is good to kick the time out further, but then you may have to buy something in a short period of time (45 - 180) and may over pay. 

    What amount of time do you think is generally the minimum amount of time to hold a property if you are going to do a cost seg? 

  • Michael PlaksPro Member
    OP
    Tax Accountant / Enrolled Agent · Houston, TX · Member since 2014 · 5k+ posts · 6k+ votes
    1mo

    Hi @Brett P Swarts, thanks for chiming in.

    I don't think there is a specific time horizon that applies across the board. In some situations, cost seg makes sense even with a very short holding period. For example, if you are rolling gains into a 1031, or if you have gains to offset this year but not next year, or if you have some other income spike, and so on.

    That said, in a very textbook case of having just one investment property that you are planning to sell once it appreciates - maybe 5 years of holding will make cost seg worthwhile, even considering depreciation recapture. Of course, YMMV.

  • Investor · Pflugerville, TX · Member since 2014 · 152 posts · 93 votes
    1mo

    I did a cost segregation on a six-plex that we own and it felt great the first few years as the depreciation was higher but it caught up after a couple and now we have less to offset the income.  All in all I think it is a wash and probably not worth doing unless you plan on getting taxed less in the future.  Even then that depreciation recapture tax rate will come back to bite you at some point.  

    • Real Estate Consultant · Denver, CO · Member since 2021 · 661 posts · 389 votes
      1mo
      Quote from @Christopher Gilbert:

      I did a cost segregation on a six-plex that we own and it felt great the first few years as the depreciation was higher but it caught up after a couple and now we have less to offset the income.  All in all I think it is a wash and probably not worth doing unless you plan on getting taxed less in the future.  Even then that depreciation recapture tax rate will come back to bite you at some point.  


      Cost segregation is about the time value of money. If you reinvest the money that you would have paid in taxes, you make out exceedingly well. Leaving that possible cash flow with the Treasury Department earns you no interest or appreciation. Remember, ALL depreciation is recaptured upon sale, even straight-line depreciation. Of course, you will likely lose the advantage that cost segregation provide you if you spend the extra cash flow on non-income producing purchases. 1031 exchanges also work to your advantage down the road. Also, if you intend to will your properties to your heirs, you NEVER have to pay any recapture. Your heirs receive the property at full market value and can do another cost seg upon their possession of the property. What's is not to like about cost segregation, even the AICPA and Journal of Accountancy recommend investors do it. BTW, if you purchase the property for your own company's use, such as manufacturing or as a doctor, you have the opportunity to make what would be a passive investment into an active investment in the first year of ownership. I have seen too many tax professionals miss this opportunity for their clients. 

      If you haven't done so, also read Stanley Odum's excellent explanation above. We both work for the same company. 

  • Brett P SwartsPro Member
    Specialist · SAINT AUGUSTINE · Member since 2017 · 270 posts · 27 votes
    1mo

    Thanks @Michael Plaks. That makes sense to me. 

  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    1mo

    I would treat it as an interest free loan or to offset higher income for the year.  

    As a loan I would ask myself what would I do with the money the next 5 years?  If I can do 1 or 2 more deals and double triple my money then any future depreciation recapture or higher taxes due to less deductions is well worth it.  

    If I treat it as a one time tax reduction due to higher income from other sources I would look at my tax bracket savings if any.  Although you could go thru the expense to refile returns.  But again treat it as a loan.  

    If I was going to do it just to reduce taxes, and not invest the tax savings in a high return investment then I wouldn’t do it.  

    One time we did so we could keep scaling. Doing either 100% or 400% COC returns in 2 years. Another time we had a farm land sale gain we offset.


    This does play into any future sale of those two properties.  As far as timing or not scaling at the moment.   Or rolling via 1031 or scaling and reinvesting into another property where we didn’t write off again.  

  • Accountant · We serve all 50 states · Member since 2015 · 90 posts · 50 votes
    1mo

    I absolutely agree with my colleagues! I think this topic has been highly popularized by Tik Tok and other social media, so a lot of my clients have been hyped over it. But the thing is, it doesn't always give any benefits. If you are not a real estate professional, chances are it's not going to make a difference, and all the costs and hassle of doing it will be in vain. 

    With that said, a few of my clients did save tens of thousands of dollars in taxes with proper planning and the right timing of it. That's why it's so important to talk to a tax professional before pulling the plug on it.

  • Specialist · United States · Member since 2025 · 45 posts · 31 votes
    1mo

    In response to Example A comments, passive loss is limited by passive income. In a passive income/loss scenario, the loss created through cost segregation is suspended until absorbed by passive income or the applicable assets are sold in a taxable event. For passive investors who own multiple properties, passive gains and losses offset each other. Passive activity grouping elections allow passive investors to treat multiple activities as a single activity. This understanding of IRC Section 469 PAL rules is why cost segregation continues to be very popular tax deferral strategy for passive RE investors. In addition to STR and REPS, there is an active participation exception to the PAL rules that allows taxpayers who meet the active participation requirement (i.e., make management decisions) to deduct up to $25,000 of passive losses against non-passive income. This deduction phases out when AGI is between $100K and $150K. In response to Example B comments, if IRC Section 1245 Tangible Personal Property (shorter life assets) acquired incidental to Section 1250 Real Property (longer life assets) are not replaced/retired during the recommended 3 to 5 year holding period after applying the results of a cost segregation study, a diminished value can be assigned to the shorter life assets which are taxed at the personal income tax rate of up to 37% upon sale as these assets will be partially or fully depreciated and more gain can be assigned to longer life assets taxed at the more favorable Real Property tax rate (up to 25%). This minimizes the impact (amount) of depreciation recapture upon sale. In response to "one year only," this depends on whether or not the study generated enough loss to carry forward into subsequent years. Cost segregation is a time value of money play that improves cash flow. Most investors take advantage of the reduced taxable income resulting from cost segregation (bonus/accelerated depreciation) to purchase additional property, pay down the loan principal, hire property managers, make improvements, etc. Disclaimer: This is not tax advice.

  • Basit SiddiqiBusiness Member
    Accountant · New York, NY · Member since 2015 · 8k+ posts · 3k+ votes
    1mo

    I also agree that cost segregation studies are great when they work. As you mentioned, they don't always work and are over advertised on Biggerpockets and social media platforms.

    I often get some new clients that already purchased a cost segregation study and the prospective clients often mention never having a discussion with any accountant prior to the purchase of the cost segregation study, which is concerning.

    The last thing I don't like about the study is that most estimates/studies will mention 'tax savings' by getting the study without any disclaimer that it may be rejected by PAL or dependent on the overall tax burden by the taxpayer.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.