Just announced. More than many thought including me. I figured 1/4 point then another in a couple of months.
Should be interesting to see how things shake out.
@Michael Baum
I believe they noted to be another 1/2 point and down to 4.5 by end of year, 3.5 by end of 2025 and 3 by end of 2026.
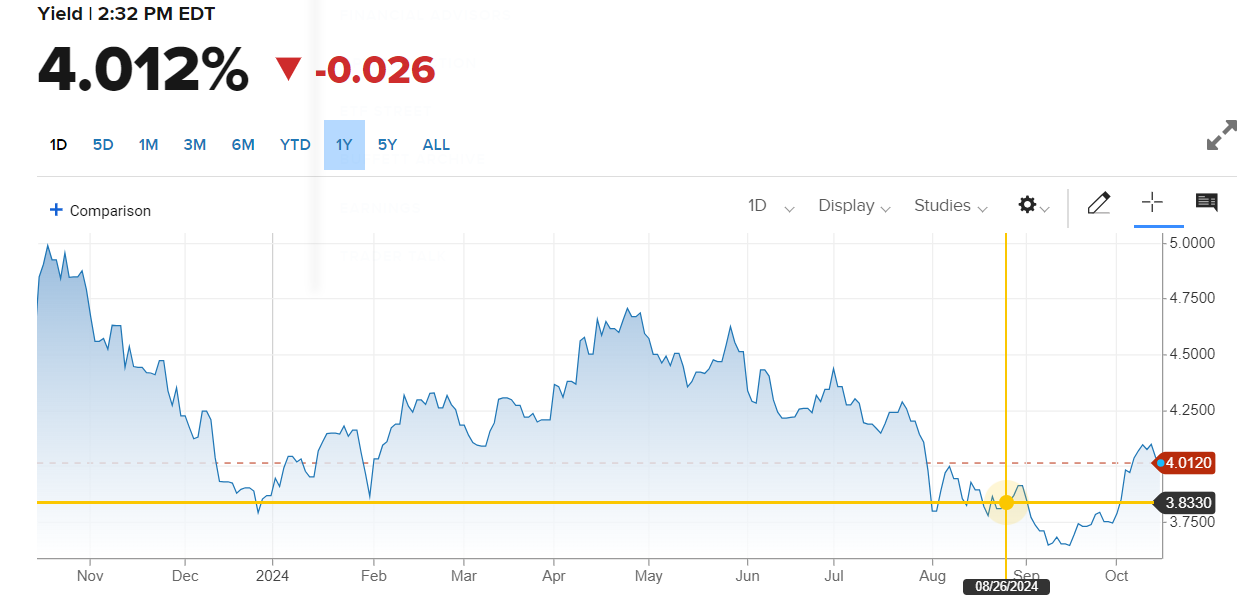
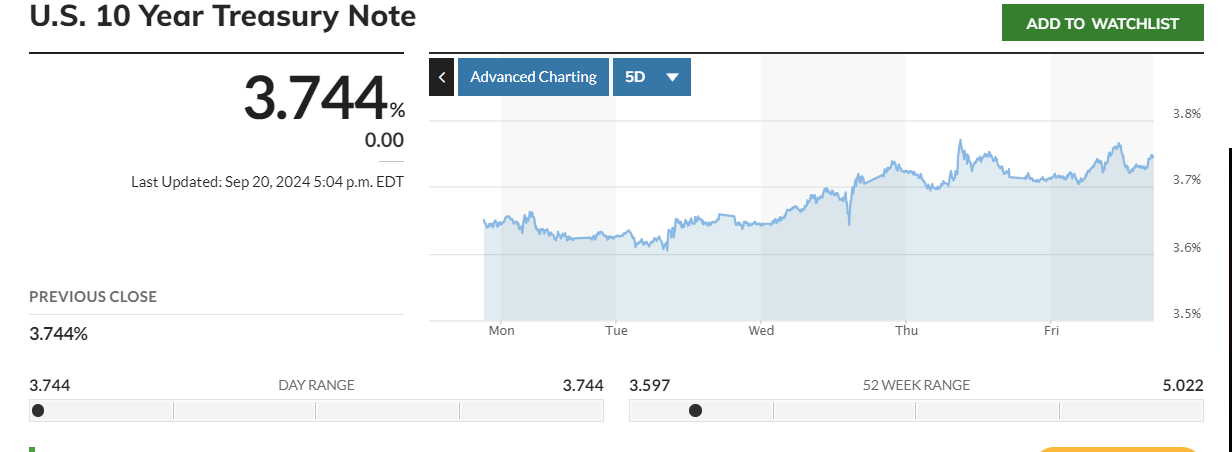
Again mortgage rates are closerly correlated to 10 year not short term rates - so we can see how that reacts and how investors price the 10 year to gauge mortgage rates
I think people think rates will drop tomorrow but the last month rates have been dropping knowing the fed was reducing rates
Economy weaker than you thought? Dow is above 42K (record) Economy booming. Rates going down.
I sure wish gas was low. Over $4 a gallon in my area.
Ouch! It's under $3 here in KC
I sure wish gas was low. Over $4 a gallon in my area.
Here's what get's me on all this with gas.
So, we have all these electric autos now right, they only need electricity to run.
And we have this thing about stop carbon emissions, which gas a diesel emits, a lot of.
And we readily, and rather easily, have generators that run on hydrogen. Hydrogen that comes from regular tap water via electrolysis. Simple simple stuff nowadays, average handy person can do a conversion at home to rig it up.
So why can't we just, ya know, put a generator in the boot of an electric auto? Which would average about 100 mpge (mile per gallon equivalent)? And with near to 0 carbon emissions.
It would cost the average person what, $5, $10 a week for fuel?
If want to fight inflation, cause deflation, well, there ya go. How much would that deflate costs if all transport fuel costs dropped by 90%?
I bet ya all the water used in the current gasoline/diesel/ethanol process would offset a big chunk of that annual water use for hydrogen.
Hey @Collin Hays, I agree with you. That is why I said Full Bore.
There are recessions and there are RECESSIONS.
I don't want a repeat of 2007-2009. I would rather have it be more like early 2001.
07-09 did suck but we also purchased 6 houses for under 100k and we learned from that period so with cash on hand I wouldn't mind it.
As long as you are well positions with access to capital, a recession or a RECESSION would be an excellent buying opportunity.
In illinois that would work wonders because our taxes are so high. a new construction 1,500 sq ft home here is going for around 300k to 330k in my area. But the tax rate is 3.1 to 3.3 percent depending on the town. There is a homeowner exemption but the taxes are still 7k to 8k a year for that house. That would save a homeowner 70k to 80k over the 10 years. HUGE incentive.
But where that wouldn't work would be in states like tennessee where they pay $800 a year for homes valued at 600k to 700k. I"m guessing areas like florida and such would be the same thing. Wouldnt' move the needle.
Not sure how best to do it, but a larger first time homebuyer credit makes no sense to me. Thats just going to create a larger buyer pool for existing homes which will drive up those prices (and inflation) but not really address the lack of new construction going on.
Now let's see it.

I don't think we see a GFC repeat, necessarily, it's just strangely unique how similar mid Sep 2007 to mid Oct 2007 is to mid Sep 2024 to mid Oct 2024. The sentiment, the narrative, and the numbers. Almost everything is the same; the fear of rampant inflation, housing issues, junk yield to fed funds ratio.
The latter point is the absolutely most worrisome.
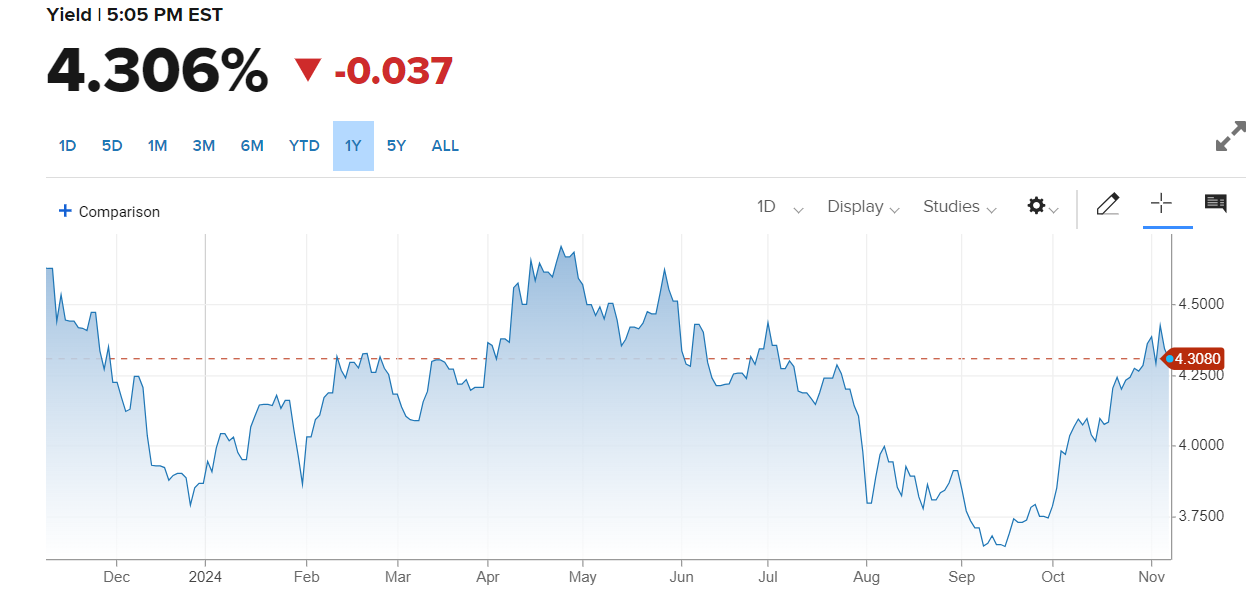
Up we go, like I said before. I don't think we stop here, I would not bat an eye at 5% re-surfacing and 30-year FRM being near 8% for primary by EOY, maybe shortly thereafter.
As supply increases, and rates increase, this is going to force a correction. Trump's policies will have a net long-term benefit, but be a short-term bruise. Higher inflation, higher wages for sure, but the former happening first. And that's where some blood will surface.
I believe we see 8% FRM before we see 6%. The media keep saying fed cutting rates is great for mortgages is completely misguided.
I am just wondering how this trickles into equities, because now margin is getting cheaper and we Q3 earnings aren't as bad as some, like me, suspected. I would not be shocked to see Nvidia post excellent earnings the week after next and run up again.
Rather than do what most do, I will take @Mike Dymski advice and rather than admire the problem. Tell folks what I am doing; still going long gold, btc, but equity wise heavy leaps on NVIDIA, META, OKTA collared with puts(15:5 ratio) so net bullish.
Real estate wise--as rates keep moving up on FRM, and inventory increases, I will continue to be a deep value bid. My deep value bids are getting more aggressive as sellers realize these fed funds aren't getting their houses sold overnight. I have yet to get under contract since attempting to since labor day, but I am in no rush. I believe I am well set, I am targeting Smokies STRs and Austin LTRs. I feel like Austin may be the poster boy of this rate:inventory issue and I'd like to get this as my barrier to entry.
And if I'm wrong, oh well I tried.
@V.G Jason we are now into a place where Fed actions are arguably one of the smallest impactors on economic immediacy and near term future.
If Fed Dept of Edu is effectively ended sending all back into hands of the States, all the industry built around such sector is completely disrupted and how does that play out? Personally I am a fan of this but still, it will be an industry disruptor.
Next, if U.S. goes "OPEN FOR BUSINESS" on oil and gas, that changes everything. Imagine if actions were done to replace RU as the #1 O&G exporter supplying Europe. This is one ball in play up in the air right now.
Next we have actions to on-shore US manufacturing industry by eliminating foreign advantages in trade (this is where tariffs come into things) and forcing foreign business to invest in US domestic operations.
And so far none of this is theory or banter, these are campaigned items of promise so, very real potential at realizations.
And than the Grand-daddy of them all, eliminating federal income tax.... Holly cowabunga would that change everything. And I believe it's BRILLIANT because fact and reality is this system no longer works at all. We have added layer upon layer of complexity to keep it working, to the point now where it's a mess that nobody even those administrating it get anymore. The savings in operating the federal government alone from elimination and moving to any of the simplified systems such as national sales tax etc, and the savings to everyone out there......
Not to mention one factions constant talk about "pay your fair share", well ok, that's an easy way we get there, the person buying cans of tuna pay pennies and those buying tins of caviar are paying tens of dollars per, that is a common sense SIMPLE "fair" allocation.
And that would be a MASSIVE income boost to the middle class who's been slaughtered the past decades.
All of these are in play and more. Any number of them is a massive disruptor. Together, it alters the landscape so much it's hard to wrap the mind around.
The biggest factor in what things will be in coming months and years will be which of these are actually executed upon.
Fed rate is a drop in the bucket in contrast to all these items now in play.
I see the stock market entering a cycle of massive swings because of industry impacts from such changes, both positive and negative. Than the assorted $ chasing those massive shifts, and working to anticipate the next in there trades. A true wild-west for wall-street where it's very possible the biggest players and winners will look more like RoaringKitty than the Claus Schwab's. And thus just another disruptor factor.
@V.G Jason we are now into a place where Fed actions are arguably one of the smallest impactors on economic immediacy and near term future.
Yes, but tell that to the general public in regards to the fed actions being the smallest impactors. They're completely oblivious to this.
Why can't we quote context anymore, and it just quotes with nothing lined in there. Makes no sense BP.