New to RE-Bay Area investing question - Cashflow vs appreciation?
Developer · Newport, NJ · Member since 2019 · 50 posts · 43 votes
Hi Everyone,
I have been reading the book on Rental Property investing by Brandon Turner and it is helping me a lot. Brandon always mentions that appreciation is like gambling and a speculation. We should not buy any properties based on speculation. He says the first thing we should look for is positive cashflowing properties. But people from the bay area know this very well that here it is basically the appreciation which matters as most of the properties are negative cashflowing for a long time.
I currently have 50k worth for downpayment (700k loan) and was looking to buy a home with FHA loan and house hack. that way I will save up living expenses and also taxes. In my range, there were a few houses in San Bruno but only 2 bd and the numbers did not make any sense. Also, the only places that makes sense were places in East Bay (Hayward, Oakland, Richmond etc). Now, the only thing I am confused about is which location should I choose and also should I ride this appreciation roller coaster? How do you people find out if a property is going to appreciate or not?
Any help would be greatly appreciated.
Thanks
Hi Everyone,
I have been reading the book on Rental Property investing by Brandon Turner and it is helping me a lot. Brandon always mentions that appreciation is like gambling and a speculation. We should not buy any properties based on speculation. He says the first thing we should look for is positive cashflowing properties. But people from the bay area know this very well that here it is basically the appreciation which matters as most of the properties are negative cashflowing for a long time.
I currently have 50k worth for downpayment (700k loan) and was looking to buy a home with FHA loan and house hack. that way I will save up living expenses and also taxes. In my range, there were a few houses in San Bruno but only 2 bd and the numbers did not make any sense. Also, the only places that makes sense were places in East Bay (Hayward, Oakland, Richmond etc). Now, the only thing I am confused about is which location should I choose and also should I ride this appreciation roller coaster? How do you people find out if a property is going to appreciate or not?
Any help would be greatly appreciated.
Thanks
A lot of the senior head honchos at BP have experiences that bias them towards the midwest. In Ohio or Colorado or Nebraska, I agree that it might be a total coin toss if something will appreciate or not. A family member of mine just sold a home in small town Indiana after owning it for 15 years, and it didn't appreciate a single inflation adjusted dime during that entire time they owned it.
Let's compare/contrast with our area. I dare you to find someone who has owned well located Bay Area real estate for 15 years, at any point since 1945, that didn't see that property DOUBLE in value over that 10 or 15 years.
And if you want to "whatabout" the Great Recession, great grab what some considered a "rough" neighborhood in Oakland in 2007, and let's even shorten it to 10 years. Fruitvale Oakland CA sales prices 2007 v 2017 for well maintained real estate. Buying right on the eve of a once-a-century catastrophic event, there's your WORST case scenario going back six full decades. And you STILL came out ahead, it probably did indeed double in value.
At some point we must concede that it's not "luck," the dice in the SF Bay Area are quite loaded, and they are loaded in favor of property owners. Income in the Bay Area is largely a tech story. Wealth in the Bay Area is largely a real estate story. It would IMO be silly to evaluate things in our area like our area is Ohio.
But, again, if you're looking in rural areas or the midwest, then yes "cash flow is king." It MUST be king, since in those markets you MUST assume zero appreciation.
And not to put too find a point on it, but Saj right above is a Subject Matter Expert on achieving "impossible" cashflow in the Bay Area, in the current market, right now as we speak he has one in escrow. See podcast here where he goes over exactly that:
https://anchor.fm/sean-pan/episodes/33---Why-Investing-in-Your-Backyard-is-the-Best-Strategy-with-Saj-Shah-e3d249?fbclid=IwAR0eZ-wL-Plb00UjP_NIYQ4eSUn-gC26J60yrcKtPSqqOF1qgBHPnX_sjgg
Cashflow for me, and I invest in the bay area. Deals are harder to find, but they're out there. Appreciation is a game of speculation, whereas cashflow is tangible money in your pocket.
@Vivan Bhalla you should be looking at multi family, a duplex up to 4 units. With your $50K you can afford much more than $700K because the potential rental income will help you qualify for a more expensive property.
Yes it won’t be a house, and yes you’ll be sharing space. But if you make this sacrifice, you can likely find cash flow in the Bay while benefiting from the immense appreciation.
@Account Closed Thanks for your reply. I tried finding a few homes but I could not find anything for this range in the bay. Which areas were you referring to?
Also, how can the rental income let me buy a more expensive home? Can you explain that strategy please?
You shouldn’t be looking at homes. You should set your search criteria to multi family.
You should also speak with a lender to get you pre-approved, before you analyze deals. @Chris Mason is great and has done several loans for me. He can add in future rental income from the other units (that you’re not living in) and use that to help you qualify for a more expensive property.
Hi Everyone,
I have been reading the book on Rental Property investing by Brandon Turner and it is helping me a lot. Brandon always mentions that appreciation is like gambling and a speculation. We should not buy any properties based on speculation. He says the first thing we should look for is positive cashflowing properties. But people from the bay area know this very well that here it is basically the appreciation which matters as most of the properties are negative cashflowing for a long time.
I currently have 50k worth for downpayment (700k loan) and was looking to buy a home with FHA loan and house hack. that way I will save up living expenses and also taxes. In my range, there were a few houses in San Bruno but only 2 bd and the numbers did not make any sense. Also, the only places that makes sense were places in East Bay (Hayward, Oakland, Richmond etc). Now, the only thing I am confused about is which location should I choose and also should I ride this appreciation roller coaster? How do you people find out if a property is going to appreciate or not?
Any help would be greatly appreciated.
Thanks
A lot of the senior head honchos at BP have experiences that bias them towards the midwest. In Ohio or Colorado or Nebraska, I agree that it might be a total coin toss if something will appreciate or not. A family member of mine just sold a home in small town Indiana after owning it for 15 years, and it didn't appreciate a single inflation adjusted dime during that entire time they owned it.
Let's compare/contrast with our area. I dare you to find someone who has owned well located Bay Area real estate for 15 years, at any point since 1945, that didn't see that property DOUBLE in value over that 10 or 15 years.
And if you want to "whatabout" the Great Recession, great grab what some considered a "rough" neighborhood in Oakland in 2007, and let's even shorten it to 10 years. Fruitvale Oakland CA sales prices 2007 v 2017 for well maintained real estate. Buying right on the eve of a once-a-century catastrophic event, there's your WORST case scenario going back six full decades. And you STILL came out ahead, it probably did indeed double in value.
At some point we must concede that it's not "luck," the dice in the SF Bay Area are quite loaded, and they are loaded in favor of property owners. Income in the Bay Area is largely a tech story. Wealth in the Bay Area is largely a real estate story. It would IMO be silly to evaluate things in our area like our area is Ohio.
But, again, if you're looking in rural areas or the midwest, then yes "cash flow is king." It MUST be king, since in those markets you MUST assume zero appreciation.
And not to put too find a point on it, but Saj right above is a Subject Matter Expert on achieving "impossible" cashflow in the Bay Area, in the current market, right now as we speak he has one in escrow. See podcast here where he goes over exactly that:
https://anchor.fm/sean-pan/episodes/33---Why-Investing-in-Your-Backyard-is-the-Best-Strategy-with-Saj-Shah-e3d249?fbclid=IwAR0eZ-wL-Plb00UjP_NIYQ4eSUn-gC26J60yrcKtPSqqOF1qgBHPnX_sjgg
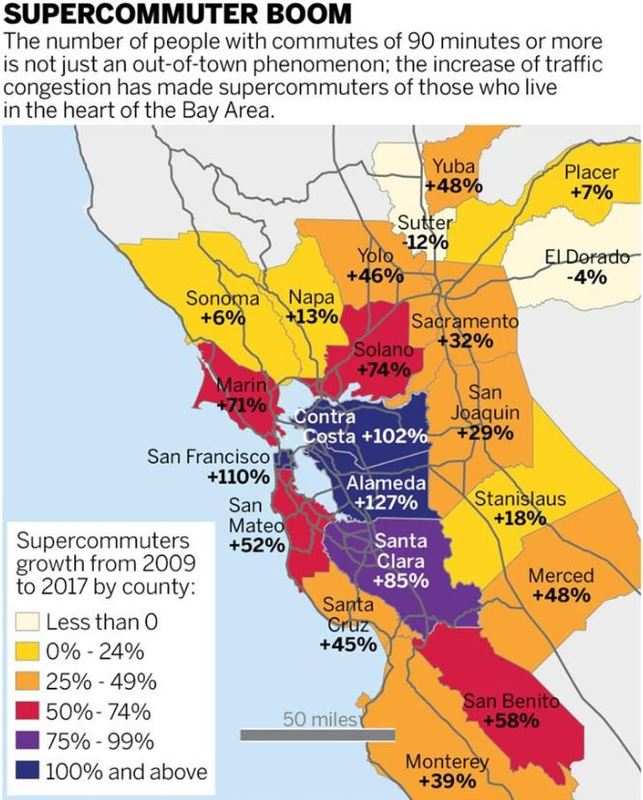
Here's something driving demand (and thus prices and rents) for well located Bay Area real estate that isn't often discussed:
Thanks @Chris Mason for the advice it was really helpful. Also, @Account Closed thanks for the advice on MF real estate houses. I will look for that as well. Do you have any areas in mind where I should focus? Chris mentioned Richmond to be a nice choice, what are your suggestions?
Vivan,
To parlay on what Saj and Chris said, look for a multifamily asset and long-term appreciation in the Bay is real, not some myth or speculation like the clueless folks on BP claim. In fact, watch out for the ones who claim appreciation is speculation because they have some OOS 💩 to sell to you.
Real estate is about supply and demand, and desirability. The Bay Area has all of these factors. Supply is constrained due to geography and NIMBYism in the name of environment protectionism. Bay Area real estate sells to the entire world in addition to a tons on high paying jobs here. Bay Area is the land of endless opportunities where dreams become reality.
Appreciation can be created by us in addition to the market appreciation, which is due to supply constraint and rent growth. Higher rents = higher asset prices. Saj and I have created hundreds of thousands in equity on each of our purchases within months. We then do a cash out refinance. Rinse and repeat. Times that by a few handfuls of buildings and we’re talking about millions. Now, that’s how wealth is built and cash flow is created. No one is going to hand over their equity and cash flow to us. We have to manufacture them.
Lastly, tell us which market produces consistently rent growth? Don’t you know a $50 rent increase is equivalent to $10k in equity in our market? If you run the math on Bay Area real estate, the rate of appreciation has outpaced the rate of monthly rent for the last 40-50 years or so. Basically, we get paid for owning real estate here. Nothing is more passive than appreciation. BP’s thinking is so backwards IMO. 😂😂😂
Compared to what Chris said above, 10 years of no appreciation in some OOS market? No, thank you very much.
Just some food for thought.
Cheers!
Here's an example of a triplex property in Oakland: use realtor.com and choose Property Type = Multifamily
Whichever city you invest in, familiarize yourself with tenant laws. Many properties in Oakland are sold with existing tenants (and hence priced lower). Vacant properties will go for a higher list price. Hayward, San Leandro, Newark are other options to look at.
If you want something easier than MF, then stick to SFR and create value through square foot addition or ADU addition. This gets you to a duplex where you stay in the main house and rent out the ADU. Of course, you're now sharing your lot space, so if this is your primary home then it's a lifestyle question as well.
All these options require some work on your part, whether it be in gaining knowledge or selecting your target market or networking. If you want completely hands-off, choose a good commercial syndicate and that will yield you 8% preferred / 1-5-2x equity return over 3-5 years. There are ways to make money in every asset class.
I'm a software engineer who works in East Palo Alto, but I commute from San Jose to get to work, (about an hour drive).
From friends and acquaintances that I have been talking to, it seems like people are becoming more fed up with prices of rent in the peninsula, and are looking to the East Bay for rentals.
I feel this way because I've been looking to move out now, and East Bay seemed like the cheapest option that could get me a much nicer place than anywhere on the peninsula. The only thing I had to consider is the fact that crossing the Dumbarton bridge costs $6 everyday... so maybe its just more worth it to pay more for a room close to work and avoid paying for gas + bridge toll fees everyday. (Plus, less time wasted on driving back and forth).
As a result, I've also been researching East Palo Alto as a potential place to invest, seeing that Mark Zuckerberg and his wife plan to build a private school there, and are actively contributing to the gentrification of this area (check out CZI initiative). Plus, it'd be really close to work and a great place for me to house hack, since it'd only be 5 minutes walk away from work. Seems like EPA is a small pocket that's seen crazy appreciation since 2013, and I can only see it going up from here. It's literally less than 5 minutes away from Facebook and Amazon, and 10 minutes from Google. I don't think there would ever be a shortage of demand for these properties.
@Vivan Bhalla I've been in contact with a few BP members, bothering people through messages about how they invest in Bay Area real estate, and lots of them mentioned interest-only loans. Not sure if this is applicable if you have 50k saved up, but something worth looking at and asking around about. I myself am starting my real estate journey and am actively studying the markets around me, specifically EPA and Alameda County.
I'm a software engineer who works in East Palo Alto, but I commute from San Jose to get to work, (about an hour drive).
From friends and acquaintances that I have been talking to, it seems like people are becoming more fed up with prices of rent in the peninsula, and are looking to the East Bay for rentals.
I feel this way because I've been looking to move out now, and East Bay seemed like the cheapest option that could get me a much nicer place than anywhere on the peninsula. The only thing I had to consider is the fact that crossing the Dumbarton bridge costs $6 everyday... so maybe its just more worth it to pay more for a room close to work and avoid paying for gas + bridge toll fees everyday. (Plus, less time wasted on driving back and forth).
I would rent in a cheaper place to live and save money. appreciation can only be done (ideally) in two ways - timing/location + forced appreciation.
But why not get both. The housing market is primed to drop (nothing like in 2009-2011) but still we should be seeing a steady decline in the coming years.
House hack is a great idea and way to get started as soon as possible but again, don't overpay for properties in this current market.
Two more tips - a base Tesla model 3 can be had for less than $40,000 and you will save both gas and toll fees ($3) for bridge toll. Free carpool/express lane access for easier commute. almost NO maintenance. Lastly, you have to "live" and enjoy. investors are going to hate me for saving this but use it as motivation to invest more.
Why not live in Newark (rent or house hack). I think that is one of the best places for investors. Newark, CA is such a great location (close to everything) and yet prices are still fairly good compared to other parts of the SF bay area.
Joe
@Michael Hyun It'll be a good idea to compare cashflow for house hacking a place in EPA after purchasing and house hacking a place after renting the entire house. If I didn't live in the same city where I worked, I'd definitely look into moving closer to my workplace. This is mainly because time is money and I'd rather stay sane rather than getting stuck in mind numbing traffic.
Most of the properties I've analyzed in the bay will fall into negative cashflow. I suppose getting a duplex - four plex might work a bit better for cashflow but definitely don't overpay for a property in this heated market.
@Vivan Bhalla listen to @Account Closed, as he gave you sound advice regarding targeting 2-4 units vs single family. As for which cities and which specific neighborhoods, that’s where you have to do homework! Start by looking at listings to find reasonable price points. Then walk the areas, talk to neighbors there, read local news about those areas, etc.
Second, search on the BP forms for “cash flow vs appreciation” (or it’s variant), and you will uncover a whole lot of conversations about Bay Area investing vs out of state. I commented in the past a lot about this, so search for my comments as well. Frankly I’m tired of writing the same damn thing over, and over and...although @Account Closed was kind enough to do so, and give you an experienced investors POV.
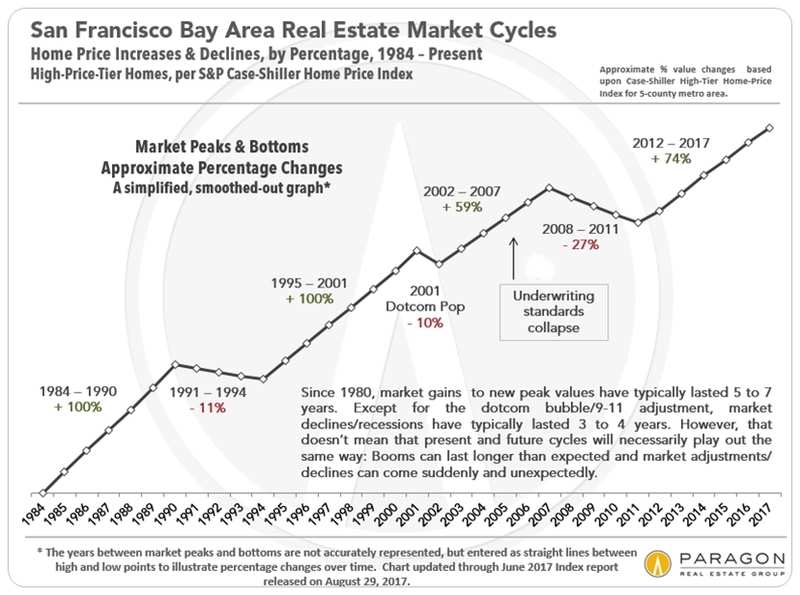
Lastly I’ll leave you with this graph, which basically says it all:
-good luck!
@Vivan Bhalla and @Michael Hyun,
Unlike the TK marketers and providers, we fellow local investors don't have anything to sell to you guys. It kills me/us to see our fellow Bay Area investors, in general, throw their hands up with our market and go OOS. Most of them just take the path of least resistance and learn it the hard way.
Let me share with you a brief story. Over a cup of Peets Coffee today, my partner and I went over some rehab, repair and rent numbers. It reminds us why we're doing what we're doing. The formula seems sooo simple. We buy a building with $7-$10k/mo in-place rent. Over a course of 5-10 years, the rent roll goes up to $12-$15k conservatively. Say we get to keep only 70% of that rent increase as the property management company keeps 5%, property taxes, insurance, repair costs, etc... take another 25%. That's still $3.5k/mo, which is equivalent to $700k of equity per building. Times that by 10 buildings we own. At the same time, tenants are paying down over $2M of principal over the course of 10 years. That's $9M, or $4.5M for each guy. Of course, the pathetic cash flow of six figures help pay for lunches and coffees while the true wealth is being built.
We recently completed a cash out refinance on 15 units. Our average repair and maintenance cost came in at $568/yr/unit for the previous 2 years. The appraiser noted it costs an average $1,300/yr/unit for our San Jose market. We disputed the number and challenged our loan officer to take this to his committee. I told him we're full-time RE investors, and I'm a licensed general contractor in addition to being a licensed civil engineer. Could this be the reason why we have been able to keep our R&M cost down? They accepted our reasoning, used our number and gave us a bigger loan size.
Say we save an average of $732/yr/unit, times that by 76 units we own, that's about $55k/year. Peanuts right? Our market is trading at 15 GRM. $55k x 15 GRM = $825k/year value that we add to our buildings, and I haven't even talked about the cost we have been saving on cap-ex. You're totaling dependent on someone else's, who doesn't have your best interest at heart when you go OOS. Real estate is about control and leverage. You're giving up half of the equation (control) when you invest out of your farm.
By the way, we just closed on a 4-unit building in Oakland with two vacant units, and the lot is big enough to build 7 more units. We may hit or get very close to the 1% rule once we put in the new tenants. @Rolando Reyes Jr has been to the site and checked it out.
We're also in contract to buy another 5-unit in SJ for $1.225M. Of course, people will keep parroting the market is too high, you will lose our shirt, the numbers don't make sense, blah, blah, blah... As Henry Ford said "If you believe you can't, you're right. If you believe you can, you're also right."
Just some food for thought.
@Account Closedthanks so much for your advice, It is very helpful to hear from such experienced investors like yourself. I am also focusing on getting a MF house which has more units. However, there is one big question that I have in mind - "Will I be able to get something with a 50k down payment?"
@Vivan Bhalla - if this is your first home, you can take advantage of FHA loan w/ 3.5% down. That gets you to approx. $700k in leverage (say $25k downpayment and $25k fixup). Now start to look on realtor.com or redfin.com for duplex+ homes in that range. The key to making economics work in this case will be to go for duplex at minimum. This won't work for SFR unless you can go the ADU route and manufacture income.
Listen very carefully to Saj's podcast...ton of good insights & ideas. It is a tough market & the guys who are making great deals have an advantage of starting out much earlier. Not to be discouraged, this is a sport where knowledge & experience count a lot and the only way to get both is ...to be on the ground and get started. Good luck & I'd love to follow your success.
Look into the American Dream mortgage loan from US Bank. It's a mortgage product they provide to be in compliance with the community reinvestment act. The loan allows a 3% down payment, has no PMI, and allows you to buy up to a duplex.
That's the loan I used for my first purchase, and now I can use FHA 3.5% down on my 2nd property. Though, with all the appreciation over the last 3 years since I bought, I've got 200k in a HELOC and I may not need to use FHA 3.5% down.
Get it where u fit in, as soon as u can. Hope this helps!
@DG A. You got 200k in appreciation in 3 years?