Really THINK About What You are Saying if You Think Rates Are Coming Back Down

Really THINK About What You are Saying if You Think Rates Are Coming Back Down

Scott TrenchPro Member
Rental Property Investor · Denver, CO · Member since 2014 · 2k+ posts · 6k+ votes

I continue to have arguments with close friends and colleagues about where rates are headed in the next year. And, while it's anyone's guess, I just continue to think that some investors are a little crazy/deluded to think that rates are coming down quickly. 

The only way rates come down in the next year or two in a meaningful way, is if our Federal Reserve completely screwed up, the rate hikes cause a massive recession/depression, a bubble bursts, and mass job loss/deflation forces them to reverse course quickly. 

Saying that rates are going to get back down to the 4-5% range in the next year or two, is essentially arguing that the Fed are completely out of their minds right now to keep rates where they are, will cause a huge economic disaster, panic, and reverse course quickly. 

This is really an unreasonable argument, in my view. It's not going to happen. Even if the Federal Reserve is as dumb as some people think they are, for rates to come down, they have to self-actualize the (potential, theoretical, future) damage being done to the economy, admit defeat, panic, and rapidly reduce rates.

Guys - that is a bad bet in my opinion. The Federal Reserve are not some bunch of quacks who have no idea what they are doing. They are pretty good at their jobs. And, I bet that the Federal Reserve Board got to where they are by being confident, strong economic careerists. Even if they ARE as wrong as some of the pundits say, they aren't going to panic and undo rates overnight. 

I believe that our Federal Reserve is not some bunch of idiots. They screwed up two years ago and let inflation get out of hand. They have aggressively fought that inflation with clearly effective economic policy since. They have caused economic pain, but not disaster. GDP continues to grow, employment remains high. Inflation is nearing it's target. 

A far more reasonable bet is that the Fed does exactly what they say they are going to do - they raise rates another 25-50 bps. They stop. The yield curve normalizes. The current rates set in, and we continue on our merry way with a new "normal" for Federal Funds rate for the next few years, and asset values reflect the new order. 

I keep getting called crazy for calling the yield curve normalizing in the next year or two, and the 10-year marching to 5%, 5.5%, and beyond. But, I think that this is the obvious, logical outcome of the current Fed Policy and believing what they are saying. In my view, it's simply going to happen. And I am planning accordingly.

9Reply
82 views

Most Popular Reply

JD MartinBusiness Member
Moderator
Rock Star Extraordinaire · Northeast, TN · Member since 2015 · 10k+ posts · 16k+ votes
3y

Here is my best guess at what is going to happen in the not too distant future:

1. Housing & real estate as a percent of GDP is going to decline, perhaps dramatically, as things start to seize up or downsize. No inventory because no one wants to give up 3% interest rate mortgages for 7% mortgages. No buyers because no one can afford 500k houses at 7% rates. So the housing market stabilizes but far, far smaller than it has been. All of the ancillary businesses that depend on constant buy & sell of housing start to collapse - furniture stores, refinance officers, real estate agents. 

2. Commercial real estate that is financed with variable rates starts to have a much higher rate of default. MFH projects that depended on "cashing out" every 3-5 years become albatrosses that can't find buyers and can't raise rents without increasing vacancies.

3. REITs start to fail because of the cash required to prop up the investments.

4. New construction sputters and stalls because of the high cost of labor and materials coupled with high mortgage rates. 

5. Eventually the FED lowers rates to try to combat all of the above. Whether that's in a year or 5 years there's no way to know. 

One thing I think is for certain is that the FED doesn't like to admit defeat. Dropping rates to zero at the outset of COVID was foolish and unnecessary. RE and housing may have been on a long-term unsustainable trajectory before that, but they supercharged it. Now that housing prices went through the roof and everyone refinanced, it's going to take a long time to work that through the system and the high rates in the meantime is going to destroy the RE market in the short term. I don't think it would be such a big deal except that housing & it's ancillary businesses have become such a large part of our economy. The FED painted itself into a corner with low rates - perhaps lower than they needed to be for years - and now they're going to have to walk through the paint. 

Skyline Properties
View Page
See this reply in the discussion

21 Replies

Jump to latestLatest
  • Investor · Scottsdale Austin Tuktoyaktuk · Member since 2021 · 4k+ posts · 4k+ votes
    3y
    Quote from @Scott Trench:

    I continue to have arguments with close friends and colleagues about where rates are headed in the next year. And, while it's anyone's guess, I just continue to think that some investors are a little crazy/deluded to think that rates are coming down quickly. 

    The only way rates come down in the next year or two in a meaningful way, is if our Federal Reserve completely screwed up, the rate hikes cause a massive recession/depression, a bubble bursts, and mass job loss/deflation forces them to reverse course quickly. 

    Saying that rates are going to get back down to the 4-5% range in the next year or two, is essentially arguing that the Fed are completely out of their minds right now to keep rates where they are, will cause a huge economic disaster, panic, and reverse course quickly. 

    This is really an unreasonable argument, in my view. It's not going to happen. Even if the Federal Reserve is as dumb as some people think they are, for rates to come down, they have to self-actualize the (potential, theoretical, future) damage being done to the economy, admit defeat, panic, and rapidly reduce rates.

    Guys - that is a bad bet in my opinion. The Federal Reserve are not some bunch of quacks who have no idea what they are doing. They are pretty good at their jobs. And, I bet that the Federal Reserve Board got to where they are by being confident, strong economic careerists. Even if they ARE as wrong as some of the pundits say, they aren't going to panic and undo rates overnight. 

    I believe that our Federal Reserve is not some bunch of idiots. They screwed up two years ago and let inflation get out of hand. They have aggressively fought that inflation with clearly effective economic policy since. They have caused economic pain, but not disaster. GDP continues to grow, employment remains high. Inflation is nearing it's target. 

    A far more reasonable bet is that the Fed does exactly what they say they are going to do - they raise rates another 25-50 bps. They stop. The yield curve normalizes. The current rates set in, and we continue on our merry way with a new "normal" for Federal Funds rate for the next few years, and asset values reflect the new order. 

    I keep getting called crazy for calling the yield curve normalizing in the next year or two, and the 10-year marching to 5%, 5.5%, and beyond. But, I think that this is the obvious, logical outcome of the current Fed Policy and believing what they are saying. In my view, it's simply going to happen. And I am planning accordingly.

    There is an election coming. If the Fed wants Biden re-elected, rates will go down.
  • Benjamin AakerPro Member
    Rental Property Investor · Brandon, SD · Member since 2015 · 1k+ posts · 1k+ votes
    3y

    I'm in agreement with @Scott Trench. I'll add that one flashy metric that makes the Fed happy is the US inflation rate, which has come down and affirms that the Fed is 'doing the right thing'. I think they have been pretty reactionary to that rate. Additionally, the unemployment rate remains low, at 3.5%. We need to look to that number. If it rises, I'm betting we will see a decrease in the rate, but that doesn't seem to be happening any time soon.

    Inflation is nearly where the Fed wants it to be, and unemployment is low. There is no incentive to increase rates.

    I'm looking for those low interest rate loan terms to come due in the next 2 years. Borrowers will need to refinance at higher rates, causing their returns to plummet. These will be the sellers who will finally realize that they need to price with the current rates in mind. At that point, the bankers will be the best people to help find properties.

    What are you doing to plan for this possibility?

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    3y
    Quote from @Benjamin Aaker:

    I'm in agreement with @Scott Trench. I'll add that one flashy metric that makes the Fed happy is the US inflation rate, which has come down and affirms that the Fed is 'doing the right thing'. I think they have been pretty reactionary to that rate. Additionally, the unemployment rate remains low, at 3.5%. We need to look to that number. If it rises, I'm betting we will see a decrease in the rate, but that doesn't seem to be happening any time soon.

    Inflation is nearly where the Fed wants it to be, and unemployment is low. There is no incentive to increase rates.

    I'm looking for those low interest rate loan terms to come due in the next 2 years. Borrowers will need to refinance at higher rates, causing their returns to plummet. These will be the sellers who will finally realize that they need to price with the current rates in mind. At that point, the bankers will be the best people to help find properties.

    What are you doing to plan for this possibility?


    I go fishing with my Banker and keep him very close.
  • JD MartinBusiness Member
    Moderator
    Rock Star Extraordinaire · Northeast, TN · Member since 2015 · 10k+ posts · 16k+ votes
    3y

    Here is my best guess at what is going to happen in the not too distant future:

    1. Housing & real estate as a percent of GDP is going to decline, perhaps dramatically, as things start to seize up or downsize. No inventory because no one wants to give up 3% interest rate mortgages for 7% mortgages. No buyers because no one can afford 500k houses at 7% rates. So the housing market stabilizes but far, far smaller than it has been. All of the ancillary businesses that depend on constant buy & sell of housing start to collapse - furniture stores, refinance officers, real estate agents. 

    2. Commercial real estate that is financed with variable rates starts to have a much higher rate of default. MFH projects that depended on "cashing out" every 3-5 years become albatrosses that can't find buyers and can't raise rents without increasing vacancies.

    3. REITs start to fail because of the cash required to prop up the investments.

    4. New construction sputters and stalls because of the high cost of labor and materials coupled with high mortgage rates. 

    5. Eventually the FED lowers rates to try to combat all of the above. Whether that's in a year or 5 years there's no way to know. 

    One thing I think is for certain is that the FED doesn't like to admit defeat. Dropping rates to zero at the outset of COVID was foolish and unnecessary. RE and housing may have been on a long-term unsustainable trajectory before that, but they supercharged it. Now that housing prices went through the roof and everyone refinanced, it's going to take a long time to work that through the system and the high rates in the meantime is going to destroy the RE market in the short term. I don't think it would be such a big deal except that housing & it's ancillary businesses have become such a large part of our economy. The FED painted itself into a corner with low rates - perhaps lower than they needed to be for years - and now they're going to have to walk through the paint. 

    Skyline Properties
    View Page
  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    3y

    @Scott Trench

    I am One of the select few that agree with you.

    I would be surprised if rates go back down to 2-3% and if they do not it means everyone who has a house at that rate will create some great generational wealth.

    If they do drop fast it’s because of a major event in the markets. I see rates staying 5-7% and housing going down 3-5% yoy for next several years for wages to catch up to the growth. I don’t see it popping yet because too much equity and people with low rates to cause a mass sell off

    What I am seeing though is a big uptick in 2nd mortgages which are typically used to pay down credit card debt so those with spending problems will rack up that debt again

    7e investments53 Reviews
  • V.G JasonPro Member
    Investor · Member since 2022 · 3k+ posts · 3k+ votes
    3y

    I talk to my wealth manager. This guy is one of one and just has an absolute great pulse of the market. Of course he's been wrong sometimes, but I trust his conviction. We literally just talked about where we think 2024 goes, and overall rates in the next 1-3 years on Thursday.

    His view; Taiwanese election goes properly-- rates will trend down 1.25-1.75% basis points into US election(Q4 '24). Call it 4-4.5 Fed Funds rate.  If it goes wrong, we will be more aggressive based on Chinese intel and could take rates down by 3-4%, and quick. His current bet is that China is in no position right now to engage in war, and will wait until the US election to familiarize themselves with the right approach. In that meantime(between Taiwanese/US election), the expectation of cyber war will be frothy. Fed Funds will be high 3s, low 4s by EOY '24. That's bearish from what I gather on folks here. We aren't going back to 2-4% mortgage rates until the next real labor dropping recession, usually 7-12 years. Think Fed funds sticks north of 2.5% indefinitely. 

    He believes the housing market will get hit hard in those loose markets by Q1 '24, and we'll see much more of a balanced market into Q2 '25 with supply materially picking up once Fed Funds gets into the low 3s. And that we've already seen the true material recession in the markets, and that was Oct '22-Jan'23.

  • Member since 2019 · 7k+ posts · 4k+ votes
    3y
    Quote from @Scott Trench:

    I continue to have arguments with close friends and colleagues about where rates are headed in the next year. And, while it's anyone's guess, I just continue to think that some investors are a little crazy/deluded to think that rates are coming down quickly. 

    The only way rates come down in the next year or two in a meaningful way, is if our Federal Reserve completely screwed up, the rate hikes cause a massive recession/depression, a bubble bursts, and mass job loss/deflation forces them to reverse course quickly. 

    Saying that rates are going to get back down to the 4-5% range in the next year or two, is essentially arguing that the Fed are completely out of their minds right now to keep rates where they are, will cause a huge economic disaster, panic, and reverse course quickly. 

    This is really an unreasonable argument, in my view. It's not going to happen. Even if the Federal Reserve is as dumb as some people think they are, for rates to come down, they have to self-actualize the (potential, theoretical, future) damage being done to the economy, admit defeat, panic, and rapidly reduce rates.

    Guys - that is a bad bet in my opinion. The Federal Reserve are not some bunch of quacks who have no idea what they are doing. They are pretty good at their jobs. And, I bet that the Federal Reserve Board got to where they are by being confident, strong economic careerists. Even if they ARE as wrong as some of the pundits say, they aren't going to panic and undo rates overnight. 

    I believe that our Federal Reserve is not some bunch of idiots. They screwed up two years ago and let inflation get out of hand. They have aggressively fought that inflation with clearly effective economic policy since. They have caused economic pain, but not disaster. GDP continues to grow, employment remains high. Inflation is nearing it's target. 

    A far more reasonable bet is that the Fed does exactly what they say they are going to do - they raise rates another 25-50 bps. They stop. The yield curve normalizes. The current rates set in, and we continue on our merry way with a new "normal" for Federal Funds rate for the next few years, and asset values reflect the new order. 

    I keep getting called crazy for calling the yield curve normalizing in the next year or two, and the 10-year marching to 5%, 5.5%, and beyond. But, I think that this is the obvious, logical outcome of the current Fed Policy and believing what they are saying. In my view, it's simply going to happen. And I am planning accordingly.


     from historical perspective, the Fed is always always make reverse V turn and never a reverse U turn or even |__| turn LOL
    they would bankrupt the banks and the gov./financial sector if they kept 5% rate for too long. 

    This "V" pattern is never coincidental, it has been planned since long long time, covid just accelerate this.

  • Mike TerryPro Member
    Investor · Fort Myers, FL · Member since 2015 · 293 posts · 278 votes
    3y

    Thank you @Scott Trench.  This a quite a thoughful and compelling discussion. What is the economic projections of extended 7+% mortgage rates?  I presume a stagnant market, with only necessary sales (death, divorce, downsizing, and relocations).  Do investors become defensive and hunker down reducing aquisitions, because few deals pencil?  Do we see any event where rental supply sharply increases lowering rents?  Obviously variable commercial debt will put pressure on margins and profits.  It all seems pretty pessimistic for housing.  So I guess we are in a slowly declining market with low transacations, lower econonmic activity, increased unemployment and a gradual moderation in rates. I am stacking cash and it is paying a reasonable return and keeping my eye out for an outlier deal.  Thoughts?

  • Quincy MA · Member since 2022 · 16 posts · 16 votes
    3y

    Great discussion point, @Scott Trench. 

    Below is my theory/prediction on this topic -

    As per fed's notes from last meeting, there is one more rate hike this year which will be bring fed-fund rate to 5.25-5.5% (probably in Sep and not Nov). Once that is complete, there will be a pause for next 6 months to gauge how the economy is doing. The effects will take sometime to fully sink in. 

    The stronger the labor market, the longer it will take for the higher rates to sink in and the longer it takes for higher rates to sink in, the longer it will take for fed to start looking at dropping them. As a result, imo, there are a very slim chance rates may drop by the end of 2024. Assuming the general election will have some influence on rates, I don't anticipate the rates to be dropped by more than 100 bps, which will bring the fed fund rate closer 4.5-4.75% (mortgage rates in the low 6s.) This drop will still not be good enough for housing inventory to go up as majority of the people will still have their rates locked in around 3-4% mark. It will take all of 2025 and may be some part of 2026 or the mortgage rates to go back to 4-4.5% mark.(depending primarily on the labor market as inflation would be fairly under control by then).

    As a result, I don't anticipate housing prices to drop anytime soon due to high demand and low supply. Best strategy, I believe, is to buy properties which cash flow. They are harder to find and may become even harder for next few months. I am still actively looking for my next deal but until I find it, I have parked my money in CDs that are giving a good 4.5-5% return. 

  • Rental Property Investor · Murrieta, CA · Member since 2020 · 338 posts · 344 votes
    3y

    @Scott Trench
    I think you need to dive a little deeper into the economic numbers and look more at history. In history the Fed always massively cut rates when a problem arises/breaks. I agree what they say they are going to do but the fact is if you look at history, they are always wrong b/c they are looking at past data. Like trying to drive forward looking out the rearview mirror. There has not been a recession where we have had a positive steepening with the curve uninverting by the long end going up. What happens is all yields fall and the short end just falls faster. The Fed has control of the curve from 2yrs and under. They do not control LD UST. The yield curve has been predicting low growth and inflation potential for almost 2 years now. 

    GDP terrible numbers Q1 was boosted by a one off from auto sales in January. Without that it would have been negative. Outlook for autos is flat to declining for the year so that doesn't look promising. Manufacturing continues to struggle which always falls first going to a recession. Without goods what is the service sector going to sell me. Look to Germany/Euro Zone or China. EuroZone usually leads us by a couple of months. Look how Germany had a hit to manufacturing and now their services rolled over. In a recession things do not move in a straight line.

    Employment that is easy to debunk. that is a late cycle indicator. No one gets fired before the recession. New orders are contracting, and now backlogs have been contracting. If you read reports employers are labor hoarding b/c they want to hold on to their employees. As they run through their backlogs and see that the recovery is a pipe dream, they will begin with the layoffs. Most of employment numbers are coming from retail and hospitality, which in general are lower paying jobs and you are losing jobs in higher paying sectors. Over the last two months 1000 PT employees were hired and 600 FT employees were fired. Thats why your unemployment rate lowered b/c there are more workers in the work force.

    I do agree with you that people who think the Fed cutting rates is a good thing are sadly mistaken. If you look at history, it is never a good thing when the Fed cuts rate and usually the bottom of the recession is after the yield curve un-inverts and Fed is done cutting rates. Economy, stocks, assets have been inflated but government intervention. Whether that was lockdowns, shutting down the world economy, which led to supply shocks, or you talk about the one-time stimuli that was injected into the system. These all led to speculation and one-offs. Ca had a "surplus" not b/c of anything to do with policy or economic growth it was b/c they were given money by the federal government. Now they have a bigger deficit then before the pandemic. Retail savings accounts spiked when we were getting stimulus monies. Now the stimulus stops and we are below pre-pandemic levels, right before student loans are going to restart.

    You do not move out the risk curve when the yields are inverted. There will be a premium for safe and liquid assets. Make sure you have reserves, you are cash flow positive, and you protect your assets. Which everyone should have been doing for the better part of 18months.

  • Robin SimonBusiness Member
    Lender · Austin, TX · Member since 2022 · 5k+ posts · 4k+ votes
    3y

    Rates can not be this high for any significant amount of time (any much longer) considering the Federal Government Debt Load and vertical increase in interest expense.  The only two options are A) massive cuts in spending or B) allowing inflation/money printing / rates back to zero.

    Gotta bet on B) because its 100x more palatable and people don't comprehend inflation cutting standard of living versus direct cuts

  • JD MartinBusiness Member
    Moderator
    Rock Star Extraordinaire · Northeast, TN · Member since 2015 · 10k+ posts · 16k+ votes
    3y
    Quote from @Robin Simon:

    Rates can not be this high for any significant amount of time (any much longer) considering the Federal Government Debt Load and vertical increase in interest expense.  The only two options are A) massive cuts in spending or B) allowing inflation/money printing / rates back to zero.

    Gotta bet on B) because its 100x more palatable and people don't comprehend inflation cutting standard of living versus direct cuts


     This is a good point and one I forgot to mention when I was posting. The heavy deficit we have been running as a nation for the past 20 years is going to be a major factor that will force interest rates lower. 

    Skyline Properties
    View Page
  • Investor · Austin, TX · Member since 2021 · 9k+ posts · 5k+ votes
    3y
    Quote from @Account Closed:
    Quote from @Scott Trench:

    I continue to have arguments with close friends and colleagues about where rates are headed in the next year. And, while it's anyone's guess, I just continue to think that some investors are a little crazy/deluded to think that rates are coming down quickly. 

    The only way rates come down in the next year or two in a meaningful way, is if our Federal Reserve completely screwed up, the rate hikes cause a massive recession/depression, a bubble bursts, and mass job loss/deflation forces them to reverse course quickly. 

    Saying that rates are going to get back down to the 4-5% range in the next year or two, is essentially arguing that the Fed are completely out of their minds right now to keep rates where they are, will cause a huge economic disaster, panic, and reverse course quickly. 

    This is really an unreasonable argument, in my view. It's not going to happen. Even if the Federal Reserve is as dumb as some people think they are, for rates to come down, they have to self-actualize the (potential, theoretical, future) damage being done to the economy, admit defeat, panic, and rapidly reduce rates.

    Guys - that is a bad bet in my opinion. The Federal Reserve are not some bunch of quacks who have no idea what they are doing. They are pretty good at their jobs. And, I bet that the Federal Reserve Board got to where they are by being confident, strong economic careerists. Even if they ARE as wrong as some of the pundits say, they aren't going to panic and undo rates overnight. 

    I believe that our Federal Reserve is not some bunch of idiots. They screwed up two years ago and let inflation get out of hand. They have aggressively fought that inflation with clearly effective economic policy since. They have caused economic pain, but not disaster. GDP continues to grow, employment remains high. Inflation is nearing it's target. 

    A far more reasonable bet is that the Fed does exactly what they say they are going to do - they raise rates another 25-50 bps. They stop. The yield curve normalizes. The current rates set in, and we continue on our merry way with a new "normal" for Federal Funds rate for the next few years, and asset values reflect the new order. 

    I keep getting called crazy for calling the yield curve normalizing in the next year or two, and the 10-year marching to 5%, 5.5%, and beyond. But, I think that this is the obvious, logical outcome of the current Fed Policy and believing what they are saying. In my view, it's simply going to happen. And I am planning accordingly.

    There is an election coming. If the Fed wants Biden re-elected, rates will go down.

     There are a lot more factors that go into interest rates than presidential candidates. I do not believe they will lower rates, economy is still strong after the hikes. 

  • Investor · Scottsdale Austin Tuktoyaktuk · Member since 2021 · 4k+ posts · 4k+ votes
    3y
    Quote from @Eliott Elias:
    Quote from @Account Closed:
    Quote from @Scott Trench:

    I continue to have arguments with close friends and colleagues about where rates are headed in the next year. And, while it's anyone's guess, I just continue to think that some investors are a little crazy/deluded to think that rates are coming down quickly. 

    The only way rates come down in the next year or two in a meaningful way, is if our Federal Reserve completely screwed up, the rate hikes cause a massive recession/depression, a bubble bursts, and mass job loss/deflation forces them to reverse course quickly. 

    Saying that rates are going to get back down to the 4-5% range in the next year or two, is essentially arguing that the Fed are completely out of their minds right now to keep rates where they are, will cause a huge economic disaster, panic, and reverse course quickly. 

    This is really an unreasonable argument, in my view. It's not going to happen. Even if the Federal Reserve is as dumb as some people think they are, for rates to come down, they have to self-actualize the (potential, theoretical, future) damage being done to the economy, admit defeat, panic, and rapidly reduce rates.

    Guys - that is a bad bet in my opinion. The Federal Reserve are not some bunch of quacks who have no idea what they are doing. They are pretty good at their jobs. And, I bet that the Federal Reserve Board got to where they are by being confident, strong economic careerists. Even if they ARE as wrong as some of the pundits say, they aren't going to panic and undo rates overnight. 

    I believe that our Federal Reserve is not some bunch of idiots. They screwed up two years ago and let inflation get out of hand. They have aggressively fought that inflation with clearly effective economic policy since. They have caused economic pain, but not disaster. GDP continues to grow, employment remains high. Inflation is nearing it's target. 

    A far more reasonable bet is that the Fed does exactly what they say they are going to do - they raise rates another 25-50 bps. They stop. The yield curve normalizes. The current rates set in, and we continue on our merry way with a new "normal" for Federal Funds rate for the next few years, and asset values reflect the new order. 

    I keep getting called crazy for calling the yield curve normalizing in the next year or two, and the 10-year marching to 5%, 5.5%, and beyond. But, I think that this is the obvious, logical outcome of the current Fed Policy and believing what they are saying. In my view, it's simply going to happen. And I am planning accordingly.

    There is an election coming. If the Fed wants Biden re-elected, rates will go down.

     There are a lot more factors that go into interest rates than presidential candidates. I do not believe they will lower rates, economy is still strong after the hikes. 

    What Metric are you using that indicates the economy is "strong"?
  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    3y

    @Mike Hern

    I go off onlyfans influencers monthly revenue as how I view economic conditions.

    7e investments53 Reviews
  • Investor · Scottsdale Austin Tuktoyaktuk · Member since 2021 · 4k+ posts · 4k+ votes
    3y
    Quote from @Chris Seveney:

    @Mike Hern

    I go off onlyfans influencers monthly revenue as how I view economic conditions.

    Very good. Is it UP or DOWN?
  • Scottsdale, AZ · Member since 2019 · 435 posts · 248 votes
    3y
    Quote from @Robin Simon:

    Rates can not be this high for any significant amount of time (any much longer) considering the Federal Government Debt Load and vertical increase in interest expense.  The only two options are A) massive cuts in spending or B) allowing inflation/money printing / rates back to zero.

    Gotta bet on B) because its 100x more palatable and people don't comprehend inflation cutting standard of living versus direct cuts


     This is important.  The Fed does not base policy off our Gov't Debt issuance, but it has to play a role in behind the scenes meeting, policy making, and/or the next Fed president

  • Robin SimonBusiness Member
    Lender · Austin, TX · Member since 2022 · 5k+ posts · 4k+ votes
    3y
    Quote from @Zach Wain:
    Quote from @Robin Simon:

    Rates can not be this high for any significant amount of time (any much longer) considering the Federal Government Debt Load and vertical increase in interest expense.  The only two options are A) massive cuts in spending or B) allowing inflation/money printing / rates back to zero.

    Gotta bet on B) because its 100x more palatable and people don't comprehend inflation cutting standard of living versus direct cuts


     This is important.  The Fed does not base policy off our Gov't Debt issuance, but it has to play a role in behind the scenes meeting, policy making, and/or the next Fed president


     yup. they won't say it out loud but of course its the elephant in the room

  • Investor · Austin, TX · Member since 2021 · 9k+ posts · 5k+ votes
    3y
    Quote from @Account Closed:
    Quote from @Eliott Elias:
    Quote from @Account Closed:
    Quote from @Scott Trench:

    I continue to have arguments with close friends and colleagues about where rates are headed in the next year. And, while it's anyone's guess, I just continue to think that some investors are a little crazy/deluded to think that rates are coming down quickly. 

    The only way rates come down in the next year or two in a meaningful way, is if our Federal Reserve completely screwed up, the rate hikes cause a massive recession/depression, a bubble bursts, and mass job loss/deflation forces them to reverse course quickly. 

    Saying that rates are going to get back down to the 4-5% range in the next year or two, is essentially arguing that the Fed are completely out of their minds right now to keep rates where they are, will cause a huge economic disaster, panic, and reverse course quickly. 

    This is really an unreasonable argument, in my view. It's not going to happen. Even if the Federal Reserve is as dumb as some people think they are, for rates to come down, they have to self-actualize the (potential, theoretical, future) damage being done to the economy, admit defeat, panic, and rapidly reduce rates.

    Guys - that is a bad bet in my opinion. The Federal Reserve are not some bunch of quacks who have no idea what they are doing. They are pretty good at their jobs. And, I bet that the Federal Reserve Board got to where they are by being confident, strong economic careerists. Even if they ARE as wrong as some of the pundits say, they aren't going to panic and undo rates overnight. 

    I believe that our Federal Reserve is not some bunch of idiots. They screwed up two years ago and let inflation get out of hand. They have aggressively fought that inflation with clearly effective economic policy since. They have caused economic pain, but not disaster. GDP continues to grow, employment remains high. Inflation is nearing it's target. 

    A far more reasonable bet is that the Fed does exactly what they say they are going to do - they raise rates another 25-50 bps. They stop. The yield curve normalizes. The current rates set in, and we continue on our merry way with a new "normal" for Federal Funds rate for the next few years, and asset values reflect the new order. 

    I keep getting called crazy for calling the yield curve normalizing in the next year or two, and the 10-year marching to 5%, 5.5%, and beyond. But, I think that this is the obvious, logical outcome of the current Fed Policy and believing what they are saying. In my view, it's simply going to happen. And I am planning accordingly.
    There is an election coming. If the Fed wants Biden re-elected, rates will go down.

     There are a lot more factors that go into interest rates than presidential candidates. I do not believe they will lower rates, economy is still strong after the hikes. 

    What Metric are you using that indicates the economy is "strong"?

     Un-employment rate is still low. Real estate market has not crashed. 

  • Member since 2022 · 21 posts · 5 votes
    3y

    I have heard from several realtors here in socal that they are being told by economists that rates will be cut in '24 because of the election, and they are preparing to be in a very busy, multiple offer scenario with home prices jumping. 

  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    3y

    I actually think the Fed are dumb.I think the Fed are dumb.  That is with all due respect to the person I actually know on the Board.  Yes they are super intelligent but not smart.  
    a.   They can’t beat back inflation with current government spending.

    b.  Forget the exact figures.  But the Fed has very little capacity or power as historically.  Fed debt was like 20% of GDP when they took rates up to 20%.   Now Fed debt measured and unmeasured (social, Medicare, etc large baby boomers) is multiple factors of National GDP.

    c.  Inflation primary drivers right now are shortage of labor and fuel costs.  Fuel costs can go down with just an election.  Labor costs could go down if the federal government tackled immigration.  Otherwise wage inflation is here to stay for 20 years as baby boomers cycle out.

    d.  Fed for their benefit should let inflation stay high.  This is the only way to pay off debt with cheaper dollars.   Otherwise they have to print more money causing more inflation.  

    WHO CARES:  Look at it from a personal position.  
    A.  We do commercial.  Our debt is tied to 20 year balloon SBA, 10 year SBA participating SBA bank and 7 years traditional commercial loans  ( 7 versus 5 because we are loyal to our banks, renewed last year).    Over the next 7 year time frame we will have so much equity built up we don’t care what the interest rate will be.  

    B.  We sold our largest debt property last year and took a lot of profit off the table.  Paid some debt down, but paid cash for strategic land locations for potential growth or resale.  In a good debt to equity position.

    C.  Just talked with our bankers this morning on a new project.  Showed them stress test in the financial model.  Using 7%, but say it goes to 10% before the project is completed. We fail, but still cash flow positive.   Just not a Great deal.  My point is do several stress tests.   Not just your normal deal analysis.  Know what failure looks like.  Even at 30% occupancy we are cash flow positive.

    D.  Know your overall debt to equity position and your cash flow position.  Compare your next deal versus your total portfolio.  Each deal should stand on its own two feet.  But know how aggressive things outside your realm of control before it impacts your overall health.

    E.  What happens if you die?  Look up my post on that topic.  Know you have your bases covered.  Then go get aggressive.  

    Federal actions needed to take us out of long term inflation:  ( I love inflation for our investments and Cashflow).

    A.  Authorize Keystone pipeline.  Authorize just one new oil refinery or nuclear plant.  Just one.

    B.  Continue to allow illegal immigration (which I strongly disagree with),  Speed up green card program for seasonal workers.  Open up white collar immigration. 

    C.  Stop taxing money made overseas if it is brought back into the US by corporations.

    All of the above are strokes of a pen.  If inflation goes down in one week.  The Fed can take interest rates back down in one week.  


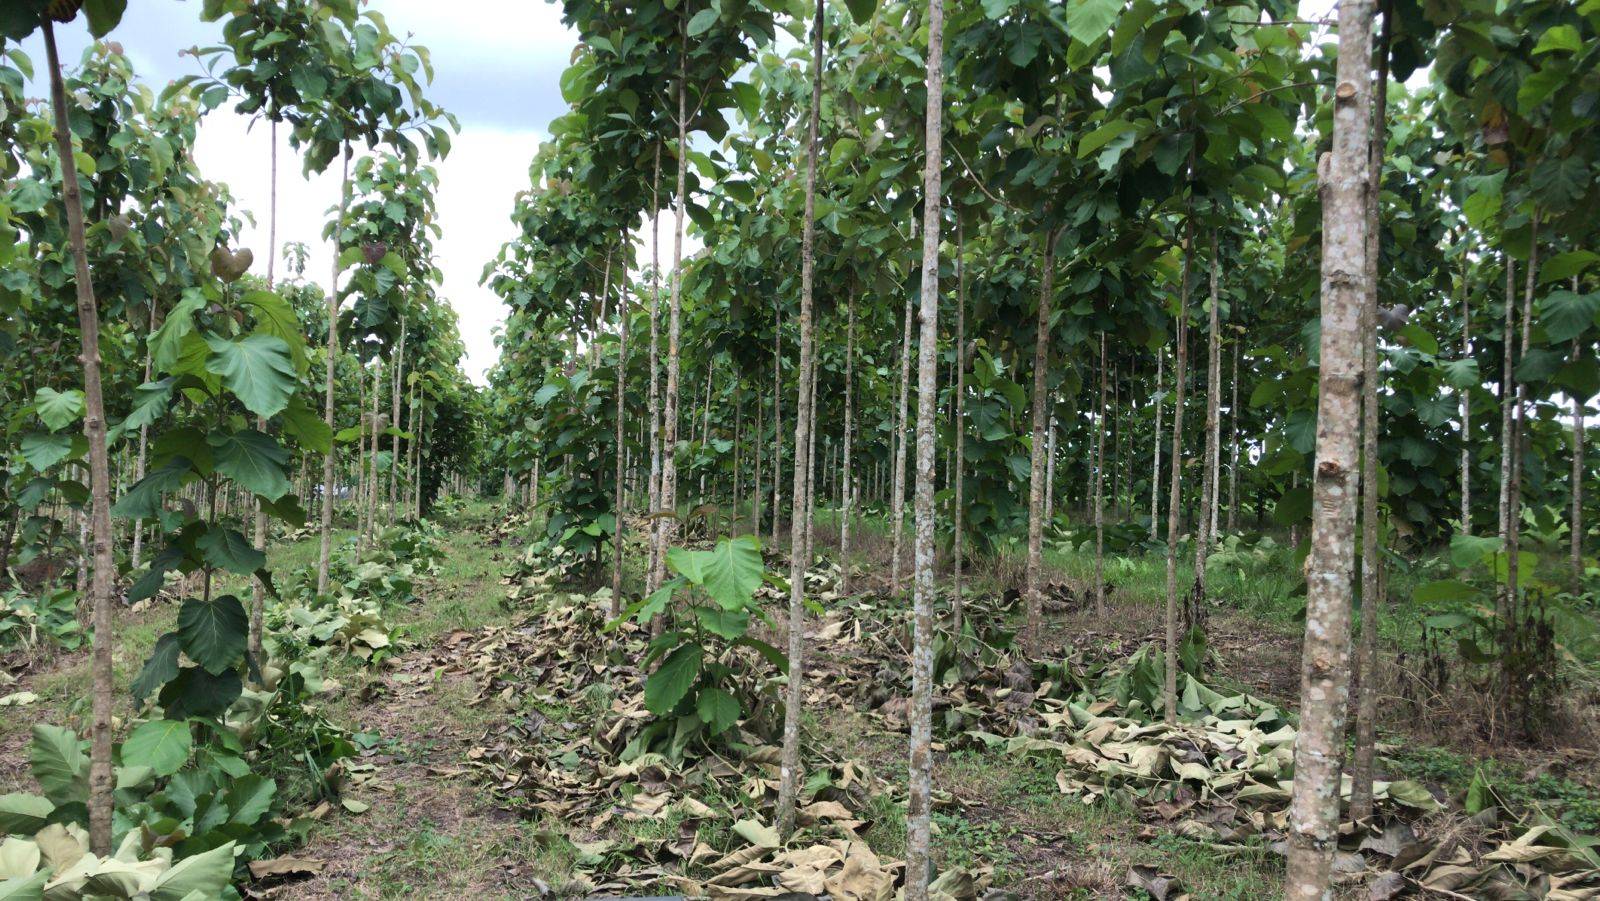
    If the above doesn’t happen we will keep investing in Teak plantations in Belize.  Actually continue to do that no matter what happens for the fun of it.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.