Due On Sale Clause About to Become More Common?

Due On Sale Clause About to Become More Common?

Realtor · Boulder, CO · Member since 2016 · 3k+ posts · 5k+ votes

We haven't seen that many due on sale clauses being enforced by lenders over the past decade or so. At the same time, we're seeing some gurus selling strategies like subto as if there is no risk of triggering a DOSC. More and more investors are looking to assume low-interest loans rather than deal with reduced cashflow thanks to today's interest rates. It was before my time, but my understanding is that triggering a DOSC was more common in the 80's during a similar rising interest rate environment like we find ourselves in now.  Lenders are probably more likely to enforce their right to call the loan if they feel their security is at risk in the hands of an unvetted buyer, or they believe they can make more money if the buyer applies for a new loan. It seems like it is becoming good business for lenders to start enforcing (they may actually also benefit by getting these 2-3% interest loans off their books). Are we about to see an uptick in due on sale clause enforcement? Curious to hear what some lenders and folks who have been around a minute think about this...

    21Reply
    880 views

    Most Popular Reply

    Investor · Tempe, AZ · Member since 2016 · 20 posts · 50 votes
    3y

    We have had the due on sale clause called 4 times this month... but knowing your way around it is crucial. Either A: revert to a lease option with the option price being the mortgage balance when the option is executed... or B: Use an executory contract instead of SubTo. Land Contract. Contract for Deed. Agreement for Sale etc. I talk about this on my youtube channel. 

    See this reply in the discussion

    185 Replies

    Jump to latestLatest
    • Jay HinrichsBusiness Member
      Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
      2y
      Quote from @Matt W.:
      Quote from @Jay Hinrichs:
      Quote from @James Hamling:
      Quote from @Jonathan R McLaughlin:

      @James Hamling agree very much with the general sentiment, but I think you are conflating criminal law and civil law. Breach of contract makes you liable for damages, but isn't a criminal act. 

      Does sound like a great way to get sued and lose though.

      I get where your coming from on that. But something being civilly illegal does not make it any more legal, illegal is illegal. 

      And keep in mind, in this day and age, one can argue such an action become criminally liable. For example, stating a component of fraud, or theft by swindle. Or, one the gov. loves to bring in, wire transfer illegal in whatever measure pulling from civil into criminal. 

      In a SubTo deal, one party argues "no, he told me it was all a-ok and nothing would happen, and now bank is _____, he lied to me, he's a con-man, I was conned", now it's no longer civil is it? 

      As @Jay Hinrichs said, it's not something to toy with unless someone really knows, not just thinks they know but really truly holds commanding knowledge, and resources, for all facet's of SubTo. 

      It's playing with plutonium. Lot's of power potential that can go horrifically wrong real fast mishandled. 

      Maybe I can clarify this a little Both as a buyer of sub too and a Lender of hard money for many decades.

      These transactions are defined by the terms of the Mortgages , Deeds of Trust , or Deed to secure debt or what ever type of debt instrument that is state specific.

      And as you read through these documents many are 5 to 20 pages long.. But virtually all of them will have a numbered chapter that is titled EVENTS OF DEFAULT

      its under that chapter that we find the following in 98% of all of these security documents. They will read that if the borrower does this:    Fails to pay tax's,  Fails to maintain the property ( commits waste) , fails to provide insurance  or ALIENATES the title.. Alienation of title includes selling the asset or any of the other methods talked about like land contracts transferring equitable interest etc.  

      Its under the Events of Default Clause that the holder of the note would rely on a remedy. However the event of default just gives the holder or beneficiary of the security interest the RIGHT to accelerate all payments and call the note due.. The holder of the note or beneficiary is NOT obligated to do so..

      So just like not paying your tax's or insurance is an event of default just like selling sub too but it is not illegal to not pay your property tax's  just gives the lenders certain rights.

      The major issues come to play as James pointed out when there is lack of disclosure to the seller and a note does get called and puts them in a terrible position. Along with bad actors using this method to get into props with very little down and then ripping rents and never paying on the mortgage because its not in their name.. I do know 2 people in Oregon that did this and ended up in Prison. I was interviewed by the FBI on one case.


      Thanks everyone, just to clarify, I'm looking to move my properties into LLCs for the (however thin) liability protection. I'm not into Sub2.


      there is no personal liability protection in a single member LLC.. there is protection if you have unrelated members in your LLC .  If there was to be a lawsuit and your a single member they will just sue you personally anyway.. so I would not get all hung up on thinking you need to transfer for liability purposes.
    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Matt W.:
      Quote from @Jay Hinrichs:
      Quote from @James Hamling:

      Thanks everyone, just to clarify, I'm looking to move my properties into LLCs for the (however thin) liability protection. I'm not into Sub2.

      In MN when using the SOS "fast-file" online system to form a LLC it states, CLEARLY but often missed by people, Single member LLC's are a disregarded entity and legally held as sole proprietor for all legal purposes.

      Meaning in plain English; it's just you, by a different name.

      I suggest researching into "the asset island method". BUT, know it's overkill for the vast majority of persons. An umbrella policy or other insurance policies can often lend similar desired protections in a much more realistic and simplistic manner.


    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Account Closed:
      Quote from @James Hamling:
      Quote from @Account Closed:
      Quote from @Matt W.:
      Quote from @Account Closed:

      @Steve K. I don’t understand why everyone gives so much anxiety to the due on sale clause. There is a simple solution. Just notify your lender of what you are planning on doing ahead of time. If they tell you no, then stop and find a different strategy. If they say yes, then you are golden and can proceed. Communication is easy people. Just communicate and it is not an issue.

      Dave, I tried this with my 3 mortgages (attempting to move into LLCs on my attorney's advice, he also said to request written permission) but each lender only would give me a form that you fill out AFTER the fact, notifying them that you have done a transfer. This seems like a huge trap to me. How did you get them to give you permission?
      Your attorney said to get written permission so he has something to argue in court if it needs to be done. If you notify your lender, they are obligated to say "no". You will not find a lender that says "yes". There are reasons for that which are beyond this post.

      The reality is you can move the proeprties into your LLC without written permission or notifying your lender. You are not violating a law. You are violating an agreement. Those are two very different things. There are solutions to the Due on Sale Situation. Now, should you move it into an LLC? That's up to you. 

      Uhm..... When contract's (agreement's) are governed by, the law, violating an agreement (breach of contract) would be an unlawful act, would it not? 

      If it is a breach of contract to do such action, no, it's not true or accurate to say a person "can" do that anymore than it is to say a person "can" rob a bank. Yes, one can do the action but doing it and doing it free of negative repercussions are 2 very different things. 

      If a person put's themself into a situation where a lender can exercise a DOS, you better have contingency plan's for "if". Assuming it simply won't happen, is failure to plan. Failing to plan, is planning to fail.

      Personally, I am not comfortable with anyone hovering an ax over my neck, confident they simply won't use it "cause". It's a finance institute of one form or fashion, they will use it if it's in there best interest, and that means the person who holds the button to drop that ax. Something happens in there job, your head could be the price of there career improvement. 

      Let's view this another way, a tenant applies to rent who was convicted of burning down a previous landlords property. They have rented 20 others places without incident, only burned down 1. Would you rent to them?     Why not?     Risk of being the 1, right? Exactly. 

      Contracts are not law. You misunderstand. They are agreements.
      When violated, contracts state what the remedy may be. It can be a simple solution or it can be through a civil trial for damages.

      You are confusing maybe, fraud, equity skimming, wire fraud and fraudulent schemes and artifices which have clear definitions. They are brought through criminal trial. They have to be charged, brought to trial, proven and convicted before they are enforced. 

      A prosecutor doesn't have jurisdiction over a broken agreement, such as a due on sale clause. 

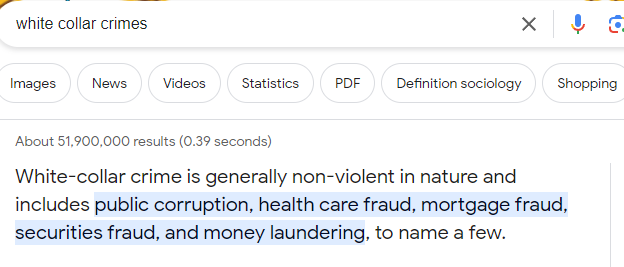
      I suggest you maybe discuss this with someone familiar in white-collar crimes, I think you'd find there input "enlightening". 

    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Account Closed:
      Quote from @James Hamling:

      I suggest you maybe discuss this with someone familiar in white-collar crimes, I think you'd find there input "enlightening". 

      Great. Where'd you get your law degree?

      Well, if you call finding out this info a "law degree" than I'd have to say via google.... 

    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Account Closed:
      Quote from @James Hamling:
      Quote from @Account Closed:
      Quote from @James Hamling:

      I suggest you maybe discuss this with someone familiar in white-collar crimes, I think you'd find there input "enlightening". 

      Great. Where'd you get your law degree?

      Well, if you call finding out this info a "law degree" than I'd have to say via google.... 

      Hmmm, no definition of what "mortgage fraud" is. What is 'mortgage fraud"?
    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Account Closed:
      Quote from @James Hamling:
      Quote from @Account Closed:
      Quote from @James Hamling:
      Quote from @Account Closed:
      Quote from @James Hamling:

      Fraud for property generally involves material misrepresentation or omission of information with the intent to deceive or mislead a lender into extending credit that would likely not be offered if the true facts were known. 


      Oh, so, you mean like say, get a person to transfer deed into your name on property while retaining there mortgage acquired under there name, there credit, there income, but now doing things in a manner to convey the benefits of said mortgage financing unto yourself who financing party never approved, reassigned to, or even has knowledge of....... You mean like that? 

      And of course there would be no pattern of such, say like doing it multiple times...... 

      Or your inability to qualify for said financing if you had to acquire it yourself right, I mean, no way, of course you have financial capacity to more than qualify for the mortgage financing right. It's not like you only swaggered into it with a few thousand in total capital, right....... 

      Look, it's obvious you have decided your right, it's all great grand and groovy, and no amount of something as obnoxious as fact's are gonna get in your way. So fine, DO-IT. 

      But if find yourself trying to make the same argument's as the proud owner of some shinny new matching bracelet's, remember; we tried to warn you. 

    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Account Closed:
      Quote from @James Hamling:
      Quote from @Account Closed:
      Quote from @James Hamling:
      Quote from @Account Closed:
      Quote from @James Hamling:
      Quote from @Account Closed:
      Quote from @James Hamling:

      Fraud for property generally involves material misrepresentation or omission of information with the intent to deceive or mislead a lender into extending credit that would likely not be offered if the true facts were known. 


      Oh, so, you mean like say, get a person to transfer deed into your name on property while retaining there mortgage acquired under there name, there credit, there income, but now doing things in a manner to convey the benefits of said mortgage financing unto yourself who financing party never approved, reassigned to, or even has knowledge of....... You mean like that? 

      And of course there would be no pattern of such, say like doing it multiple times...... 

      Or your inability to qualify for said financing if you had to acquire it yourself right, I mean, no way, of course you have financial capacity to more than qualify for the mortgage financing right. It's not like you only swaggered into it with a few thousand in total capital, right....... 

      Look, it's obvious you have decided your right, it's all great grand and groovy, and no amount of something as obnoxious as fact's are gonna get in your way. So fine, DO-IT. 

      But if find yourself trying to make the same argument's as the proud owner of some shinny new matching bracelet's, remember; we tried to warn you. 

      Please provide case law where that has happened. Where the only violation was changing title without paying off the loan.

      I will hop right on that Sir, soon as fund retainer account to do research work for ya.... 

    • Tom GimerBusiness Member
      DMV · Member since 2017 · 3k+ posts · 3k+ votes
      2y

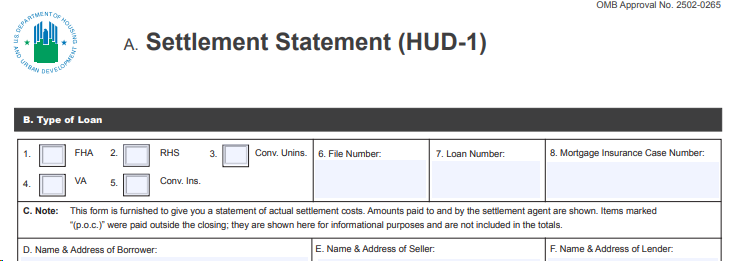
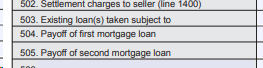
      I'm sure HUD put a specific line item (503) on the settlement statement to help people commit fraud... wtf

      https://www.hud.gov/sites/documents/1.PDF

      Gimer Law516 Reviews
    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Account Closed:
      Quote from @James Hamling:

      Here, @James Hamling: ,  @Tom Gimer:  is helping us out a little bit. Since he does closings, I trust his work. No one says Tom is endorsing or not endorsing the process, but it is what it is.
      I think we all agree that being fully transparent is beneficial to real estate investing.


      "I think we all agree that being fully transparent is beneficial to real estate investing"....

      Let's try LEGALLY REQUIRED. 

      Look, your all hammering away dead-set of getting me to say SubTo is perfectly legal, it's great, everyone with $1k who joined a group, watched a YT video, go out and do it and all will be fine. But it just ISNT SO! 

      I am sorry that you don't like the fact's, they are the fact's none-the-less. 

      If you've got diddly-squat for financial capacity to buy a property, secure the financing yourself, like 99% of those chasing the SubTo-Rainbow today, YES, it means you ARE at risk of getting yourself in a hell of a lot of legal trouble, which COULD be civil OR criminal. 

      If you got diddly-squat for financial capacity, there is a lot of risk of something going bad during operation of the property. A furnace breaks and no $ to fix it, tenant's leave, "seller" say "wtf, why is there no payment on the mortgage" and buyer says "well, I have no rent's coming in, furnace broke, it was like $8k to fix it, i don't have $8k, i was getting $300mnth, I have $1,500. And now pipes froze cause no heat, and now it's $14k more to fix pipes, I gotta walk away" and "seller" says "like hell you will, you destroyed my property, you messed up my credit, now I'm getting foreclosure warnings from bank, YOU CHEATED ME". 

      And guess what, is that person going to do EVERYTHING they can to throw you under the bus and roll back and fourth over your corpse, HECK-YEAH they will!    And who is the A.G. going to favor? You, the "investor" with your ten's of dollars and week's/month's of experience? Or the home owner, who's saying he was conned, was left with mortgage, told to transfer deed, going into foreclosure, was promised it was all 100%, was told this that and the other....... 

      YOU-WILL-LOOSE. 

      The "seller" will want your head. The bank will be happy to have your head. The A.G. will salivate at opportunity to add another head to the pike's that they can coin "predatory investor" to help further there career. 

      The vast majority pursuing SubTo today are doing it BECAUSE they have no financial capacity otherwise, which makes them the most at-risk persons for doing SubTo. Lend's the highest potential for such folly. 

      @Jay Hinrichs has stated right here 1st hand knowledge of persons that have gone to prison on this very thing. 

      Yet, here we are with the "but... but.... but..."'s. 

      As I said, GO DO IT THEN, I don't care what stupidity other's do. People do dumb stuff every day, but don't expect me to call bed-sheet-sky-diving "safe", because it ain't. 

      There is correct, safe'ish ways to do things, than there is the "guru-told-me" golden-ticket EZ-peezy BS way's that will result in a lot of people with a lot of regret. 

      As Jay and I have warned, WAY too many of the people grasping to this SubTo method SHOULDN'T do it. Are some fully capable, OF COURSE, but the way it is today most think it's how they will "get rich" with no/bad credit and little to no $.    That is INTENSLY risky, failure % is wildly HIGH. And when it comes unraveled, implications CAN BE extreme, INCLUDING jail/prison time for it. 

      To say it's safe, simple, "aaahhh banks won't do anything" is simply NOT true. The banks MAY not do anything, MAY. Things go south, I assure, with absolute certainty, the banks WILL, ruthlessly, mercilessly, do anything/everything at there disposal. And so will the "sellers".

    • Investor · Scottsdale Austin Tuktoyaktuk · Member since 2021 · 4k+ posts · 4k+ votes
      2y
      Quote from @James Hamling:

      @James Hamling: It looks like you've been reading my posts. I thank you. But here is where your confusion is: I state, pretty clearly I think, that doing SubTos when you are underfunded is very, very foolish.

      Subject To – Why You Need Money To Buy Using "Subject To" (SubTo) - Safely, Legally

      https://www.biggerpockets.com/forums/311/topics/1141313-subj...

      Using Subject To, to Get "Free" Properties - A Quick Guideline

      https://www.biggerpockets.com/forums/311/topics/1060320-usin...

      SubTo - Before You Spend A Lot of Money on Subject To - Read This - Wisdom at Work

      https://www.biggerpockets.com/forums/50/topics/1141525-subto...

      Of course, I teach Subject To & Lease Options to people "One on One", to keep people out of trouble. Can't allow mistakes here.

      I am told & believe that the "SubTo Community" is Videos and "group think" with NO "One on One" training,  meaning if you have a question, you can ask neophytes who give their opinion, but not based on experience. That approach is very dangerous. 

      And your concerns are well founded regarding the "SubTo Community" which teaches "zero down", "overleveraging" (you can use other people's money to overleveage to get the deal), "hiding the transaction", the guru of which doesn't even use Title Reports. That fact was posted earlier, giving the recording number as proof. Devotees of the "guru" poo pahed it, to their peril. The "guru", to his credit, admitted that he had 4 SubTos Due on Sales called in one week. Underfunded investors, IMHO, would be spending time in jail if that happened to them.

      I get several investors weekly from that group, who's SubTos I'm working on to straighten out. If we don't resolve the issues, they are likely to be sued.

      People could save themselves the risk if they would just use the right teachers.

    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Account Closed:
      Quote from @James Hamling:

      @James Hamling: It looks like you've been reading my posts. I thank you. But here is where your confusion is: I state, pretty clearly I think, that doing SubTos when you are underfunded is very, very foolish.

      Subject To – Why You Need Money To Buy Using "Subject To" (SubTo) - Safely, Legally

      https://www.biggerpockets.com/forums/311/topics/1141313-subj...

      Using Subject To, to Get "Free" Properties - A Quick Guideline

      https://www.biggerpockets.com/forums/311/topics/1060320-usin...

      SubTo - Before You Spend A Lot of Money on Subject To - Read This - Wisdom at Work

      https://www.biggerpockets.com/forums/50/topics/1141525-subto...

      Of course, I teach Subject To & Lease Options to people "One on One", to keep people out of trouble. Can't allow mistakes here.

      I am told & believe that the "SubTo Community" is Videos and "group think" with NO "One on One" training,  meaning if you have a question, you can ask neophytes who give their opinion, but not based on experience. That approach is very dangerous. 

      And your concerns are well founded regarding the "SubTo Community" which teaches "zero down", "overleveraging" (you can use other people's money to overleveage to get the deal), "hiding the transaction", the guru of which doesn't even use Title Reports. That fact was posted earlier, giving the recording number as proof. Devotees of the "guru" poo pahed it, to their peril. The "guru", to his credit, admitted that he had 4 SubTos Due on Sales called in one week. Underfunded investors, IMHO, would be spending time in jail if that happened to them.

      I get several investors weekly from that group, who's SubTos I'm working on to straighten out. If we don't resolve the issues, they are likely to be sued.

      People could save themselves the risk if they would just use the right teachers.


      I actually hadn't read any of your stuff previously, was just "knowledge vomiting" from my own head and opinion. 

      Your post here, while I have not gone through the link's yet, seem's to squarely hit the nail on the head. And I know exactly whom your talking of, and some may be shocked to find I have a full INSIDERS vision of it all. Yes, full access, so not outsider uninformed of what's being said, taught, promoted, and NOT said, taught etc.. 

      And with that again, nail hit squarely on the head. 

      People arguing such-and-such "Guru" is doing it and doing great, yeah, and how much is that "Guru" taking in student fee's per week/month? It's well over a million, well over. 

      Why do people not get the readily OBVIOUS; "Guru's" are selling there PROGRAM, not actually DOING the deals. If they were selling DOING, it would be; 1-on-1, JV's, etc.. They are selling HOPEIUM. REI Hopeium.

    • Realtor · Boulder, CO · Member since 2016 · 3k+ posts · 5k+ votes
      2y

      Reviving this old thread... Have we seen an uptick in DOSC six months later?

      Pace said he had 4 in one month earlier in this thread and in this video from a few months ago he says he's had 10 now. Later in the video he says his students have had 12: https://www.google.com/search?q=pace+morby+due+on+sale+claus...

      So that's a big increase considering he said he had seen zero previously among himself or his students. He also says that he's using an executory contract (or land contract in Texas) to get around them and has never lost a house. 

      He does not mention any downside to reverting to an executory contract/ lease option/ land contract. 

      My understanding is that although it can work, these types of legal agreements have big downsides compared to sub to. For example unlike sub to, in an executory or land contract the seller stays in title which means all the risks are there for them getting liens and having those attach to the property or other typical title problems, plus having to pay closing costs and having a new higher rate when you need to eventually exercise the option. That's not exactly a good alternative to sub to. 

      Also, even if it's true that is has been working to avoid the DOSC so far, my understanding is that any "outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests" can trigger the DOSC (quoting the bank definition of transfer or sale), meaning that banks could still call these loans due despite the executory contract/land contract if they so choose. 

      Is anyone else seeing an uptick in DOSC being called besides Pace and his students?

      @Account Closed

    • Realtor · Boulder, CO · Member since 2016 · 3k+ posts · 5k+ votes
      2y
      Quote from @Account Closed:
      Quote from @Steve K.:

      Reviving this old thread... Have we seen an uptick in DOSC six months later?

      Pace said he had 4 in one month earlier in this thread and in this video from a few months ago he says he's had 10 now. Later in the video he says his students have had 12: https://www.google.com/search?q=pace+morby+due+on+sale+claus...

      So that's a big increase considering he said he had seen zero previously among himself or his students. He also says that he's using an executory contract (or land contract in Texas) to get around them and has never lost a house. 

      He does not mention any downside to reverting to an executory contract/ lease option/ land contract. 

      My understanding is that although it can work, these types of legal agreements have big downsides compared to sub to. For example unlike sub to, in an executory or land contract the seller stays in title which means all the risks are there for them getting liens and having those attach to the property or other typical title problems, plus having to pay closing costs and having a new higher rate when you need to eventually exercise the option. That's not exactly a good alternative to sub to. 

      Also, even if it's true that is has been working to avoid the DOSC so far, my understanding is that any "outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests" can trigger the DOSC (quoting the bank definition of transfer or sale), meaning that banks could still call these loans due despite the executory contract/land contract if they so choose. 

      Is anyone else seeing an uptick in DOSC being called besides Pace and his students?

      @Account Closed @Tom Gimer @Chris Seveney @James Hamling @Jay Hinrichs

      @Steve K.: I don't even know where to start. He is doing Subject To all wrong, with the wrong sellers, using the wrong lenders for 2nd position (to cover closing costs and carrying costs), there should not be 2nd lenders involved at all, he doesn't care about over leveraging. He doesn't understand how to have insurance coverage, he doesn't use title reports when taking on lenders, he promotes wholesaling Subject Tos, and yes, he gets the Due on Sale totally wrong. 

      You are correct that he promotes switching the Subject To to an Executory contract which by definition and by the Due on Sale, explicitly violates the very Due on Sale Clause he says it avoids. There is even more, but space limits the response.

      Yes, I believe people will get sued and some may go to jail. It will not be a pretty sight. But, hey, tell him that. He says he has trained 4,000 “students” as of the date of that video at $8,800 each, for a princely sum of $35,200,000.

      So, there are two options:

      1. He doesn't have a clue what he is doing, but he knows how to promote and make money which is the most important thing to him or

      2. He knows he is going to hurt an awful lot of people, but he doesn't care.

      I don't know which it is.


       So I take it that you're not buying that he actually successfully overcame those 10 DOSC he says he used executory contracts to avoid? I mean with $35M to fall back on, why not just pay the bank off? 

    • Chris SeveneyBusiness Member
      Moderator
      Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
      2y
      Quote from @Steve K.:

      Reviving this old thread... Have we seen an uptick in DOSC six months later?

      Pace said he had 4 in one month earlier in this thread and in this video from a few months ago he says he's had 10 now. Later in the video he says his students have had 12: https://www.google.com/search?q=pace+morby+due+on+sale+claus...

      So that's a big increase considering he said he had seen zero previously among himself or his students. He also says that he's using an executory contract (or land contract in Texas) to get around them and has never lost a house. 

      He does not mention any downside to reverting to an executory contract/ lease option/ land contract. 

      My understanding is that although it can work, these types of legal agreements have big downsides compared to sub to. For example unlike sub to, in an executory or land contract the seller stays in title which means all the risks are there for them getting liens and having those attach to the property or other typical title problems, plus having to pay closing costs and having a new higher rate when you need to eventually exercise the option. That's not exactly a good alternative to sub to. 

      Also, even if it's true that is has been working to avoid the DOSC so far, my understanding is that any "outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests" can trigger the DOSC (quoting the bank definition of transfer or sale), meaning that banks could still call these loans due despite the executory contract/land contract if they so choose. 

      Is anyone else seeing an uptick in DOSC being called besides Pace and his students?

      @Account Closed @Tom Gimer @Chris Seveney @James Hamling @Jay Hinrichs


      I have not seen an uptick, but I also do not deal in the subto world. I have not heard a lot about it either. Why? Most likely because the residential market is a $12T market and my guess the amount loans sold via UPB on subto is less than $100M a year. I know Ken and Mike and their team are successful at it along with William Tingle, but they are realistic and not making it sound like its a trillion dollar industry like others make it out to be.

      7e investments53 Reviews
    • Real Estate Broker · Minneapolis, MN · Member since 2011 · 5k+ posts · 6k+ votes
      2y
      Quote from @Steve K.:

      Reviving this old thread... Have we seen an uptick in DOSC six months later?

      Pace said he had 4 in one month earlier in this thread and in this video from a few months ago he says he's had 10 now. Later in the video he says his students have had 12: https://www.google.com/search?q=pace+morby+due+on+sale+claus...

      So that's a big increase considering he said he had seen zero previously among himself or his students. He also says that he's using an executory contract (or land contract in Texas) to get around them and has never lost a house. 

      He does not mention any downside to reverting to an executory contract/ lease option/ land contract. 

      My understanding is that although it can work, these types of legal agreements have big downsides compared to sub to. For example unlike sub to, in an executory or land contract the seller stays in title which means all the risks are there for them getting liens and having those attach to the property or other typical title problems, plus having to pay closing costs and having a new higher rate when you need to eventually exercise the option. That's not exactly a good alternative to sub to. 

      Also, even if it's true that is has been working to avoid the DOSC so far, my understanding is that any "outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests" can trigger the DOSC (quoting the bank definition of transfer or sale), meaning that banks could still call these loans due despite the executory contract/land contract if they so choose. 

      Is anyone else seeing an uptick in DOSC being called besides Pace and his students?

      @Account Closed @Tom Gimer @Chris Seveney @James Hamling @Jay Hinrichs


      I can't speak to the #'s of DOSC for SubTo, which I see as ticking time-bombs and am NOT a fan of. But to my C4D's, the instrument I use to LEGALLY effect the exact same outcome as SubTo, I have had a grand total of 0 DOSC called, ever. 

      I simply don't understand the point of SubTo when there is a many generations old existing legal instrument readily available for use.  

    • Real Estate Investor · Middle TN and Southern KY · Member since 2014 · 72 posts · 26 votes
      2y
      Quote from @Steve K.:

      Quote from @Pace Jordan Morby:

      We have had the due on sale clause called 4 times this month... but knowing your way around it is crucial. Either A: revert to a lease option with the option price being the mortgage balance when the option is executed... or B: Use an executory contract instead of SubTo. Land Contract. Contract for Deed. Agreement for Sale etc. I talk about this on my youtube channel. 


      Wouldn't the downside of doing any of those things be that if the existing owner gets any liens or judgments, they will still attach to the property? If so that's a big additional risk for the buyer. Also I don't think it's that clear that any of these tactics would actually prevent the bank from enforcing the due on sale. For example according to this, it seems that transferring the title is not required for the DOS to be triggered:

      http://law.justia.com/cfr/title12/12-5.0.1.1.54.0.83.2.html

      From the bank definition of sale or transfer: "For purposes of this definition, a sale or transfer means the conveyance of real property of any right, title or interest therein, whether legal or equitable, whether voluntary or involuntary, by outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests."

      That reads to me very clearly that the granting of any legal or equitable interest in or to a property secured by a mortgage can trigger the DOS, which would include any lease option, land contract, contract for deed etc. as it clearly states in the defintion. I'm not a lawyer or anything, this is just coming from what I've learned on here, there are many valuable old threads about this topic on here like this one:

      https://www.biggerpockets.com/forums/83/topics/86029-subject....

      and this one:

      https://www.biggerpockets.com/forums/311/topics/183825-due-o..

      How is it working our for you in practice?

      They/"US Bank" took a house from me that had never been behind or late. By the grace of GOD the tenant/buyers were wanting out, and they had never been late or missed a pyment. Took good care of the property as well. 

       I told them they could stay there at no charge till the bank evicted them and made them sign a hold harmless. Thank GOD I didn't get sued! 

      Oh I tried everything. Even my mentor at that time and this was 15 years ago, tried getting on the phone with them. He offered them several senarios like Pace talks about. They couldn't be reasoned with. They had no common sense what so ever.  He had over 120 houses sub to at that time as well, and was in complete shock!! 

      I told them that it'd be over a year that they will miss this income/payments, plus added cost of attorneys, property management and selling fees. 

      Over a year later it finally sold and they lost their BUTT!!! 

      I will not touch another sub to EVER again. There is nothing like being able to sleep at night knowing I have title to my houses that I buy with cash or loans and no one can take them from me on a whelm. (long as loan is paid) 

      By the way, I had this house 2 years at the time and the loan was low interest for that time. 

      Don't say: it never happens, or it will never happen to me cause I have strategies around it! It can and WILL happen again. 

      I still get sick thinking about it. 


    • Jay HinrichsBusiness Member
      Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
      2y
      Quote from @Steve K.:

      Reviving this old thread... Have we seen an uptick in DOSC six months later?

      Pace said he had 4 in one month earlier in this thread and in this video from a few months ago he says he's had 10 now. Later in the video he says his students have had 12: https://www.google.com/search?q=pace+morby+due+on+sale+claus...

      So that's a big increase considering he said he had seen zero previously among himself or his students. He also says that he's using an executory contract (or land contract in Texas) to get around them and has never lost a house. 

      He does not mention any downside to reverting to an executory contract/ lease option/ land contract. 

      My understanding is that although it can work, these types of legal agreements have big downsides compared to sub to. For example unlike sub to, in an executory or land contract the seller stays in title which means all the risks are there for them getting liens and having those attach to the property or other typical title problems, plus having to pay closing costs and having a new higher rate when you need to eventually exercise the option. That's not exactly a good alternative to sub to. 

      Also, even if it's true that is has been working to avoid the DOSC so far, my understanding is that any "outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests" can trigger the DOSC (quoting the bank definition of transfer or sale), meaning that banks could still call these loans due despite the executory contract/land contract if they so choose. 

      Is anyone else seeing an uptick in DOSC being called besides Pace and his students?

      @Account Closed @Tom Gimer @Chris Seveney @James Hamling @Jay Hinrichs


      yes any conveyance you me anyone else can think about will allow an acceleration of the note IF the hold of said note chooses to.  the big thing not one is talking about is.. you have tax implications when you sell sub to.. you have tax implications when you deed it back and then buy again etc etc. theres more to it than the simple concepts or statements U have a transaction that needs to be reported to the IRS.   As for seeing more DOS invoked I dont work directly with those doing sub too in my day to day.. we are selling brand new construction and doing JV deals with flippers there is no debt to take sub to and sales are all cash to us.
    • Ronald RohdePro Member
      Attorney · Dallas, TX · Member since 2016 · 5k+ posts · 2k+ votes
      2y

      I haven't seen an uptick, I get maybe 1-2 every few months

    • Realtor · Boulder, CO · Member since 2016 · 3k+ posts · 5k+ votes
      2y
      Quote from @Ronnie C.:
      Quote from @Steve K.:

      Quote from @Pace Jordan Morby:

      We have had the due on sale clause called 4 times this month... but knowing your way around it is crucial. Either A: revert to a lease option with the option price being the mortgage balance when the option is executed... or B: Use an executory contract instead of SubTo. Land Contract. Contract for Deed. Agreement for Sale etc. I talk about this on my youtube channel. 


      Wouldn't the downside of doing any of those things be that if the existing owner gets any liens or judgments, they will still attach to the property? If so that's a big additional risk for the buyer. Also I don't think it's that clear that any of these tactics would actually prevent the bank from enforcing the due on sale. For example according to this, it seems that transferring the title is not required for the DOS to be triggered:

      http://law.justia.com/cfr/title12/12-5.0.1.1.54.0.83.2.html

      From the bank definition of sale or transfer: "For purposes of this definition, a sale or transfer means the conveyance of real property of any right, title or interest therein, whether legal or equitable, whether voluntary or involuntary, by outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests."

      That reads to me very clearly that the granting of any legal or equitable interest in or to a property secured by a mortgage can trigger the DOS, which would include any lease option, land contract, contract for deed etc. as it clearly states in the defintion. I'm not a lawyer or anything, this is just coming from what I've learned on here, there are many valuable old threads about this topic on here like this one:

      https://www.biggerpockets.com/forums/83/topics/86029-subject....

      and this one:

      https://www.biggerpockets.com/forums/311/topics/183825-due-o..

      How is it working our for you in practice?

      They/"US Bank" took a house from me that had never been behind or late. By the grace of GOD the tenant/buyers were wanting out, and they had never been late or missed a pyment. Took good care of the property as well. 

       I told them they could stay there at no charge till the bank evicted them and made them sign a hold harmless. Thank GOD I didn't get sued! 

      Oh I tried everything. Even my mentor at that time and this was 15 years ago, tried getting on the phone with them. He offered them several senarios like Pace talks about. They couldn't be reasoned with. They had no common sense what so ever.  He had over 120 houses sub to at that time as well, and was in complete shock!! 

      I told them that it'd be over a year that they will miss this income/payments, plus added cost of attorneys, property management and selling fees. 

      Over a year later it finally sold and they lost their BUTT!!! 

      I will not touch another sub to EVER again. There is nothing like being able to sleep at night knowing I have title to my houses that I buy with cash or loans and no one can take them from me on a whelm. (long as loan is paid) 

      By the way, I had this house 2 years at the time and the loan was low interest for that time. 

      Don't say: it never happens, or it will never happen to me cause I have strategies around it! It can and WILL happen again. 

      I still get sick thinking about it. 


      Sorry that happened to you. That seems like a more realistic result than just “talking to the bank” and having them agree to let the arrangement continue. Anyone who has ever tried to talk to the bank about anything knows how that goes. Watching some of these videos and finding lots of red flags like that which beginners wouldn’t catch but experienced folks will know is b.s. For example there is one video where at the beginning he says he had never dealt with the DOSC before and he called up the bank president, and asked him what to do, and the bank president actually tells him to use an executory contract and at that point he says he had used that method plenty of times before… so was is the first time or were there several times before? It’s obviously a made up story and the idea of getting the bank president on the phone is preposterous. In that story the bank president looks through a file cabinet to find the file. Sorry that’s just absurd and unbelievable. I’m surprised people don’t see through these gaping holes in the stories in these videos. Even in his main commercial that keeps popping up on my feed, he says at the beginning how he learned all about creative financing from his dad early on, and then less than a minute later he says he wishes he had learned these techniques earlier so he didn’t waste so many years breaking his back as a carpenter… which one is it? I’m surprised more people haven’t caught these self-contradictions and obviously fake stories. 
    • Jay HinrichsBusiness Member
      Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
      2y
      Quote from @Ronald Rohde:

      I haven't seen an uptick, I get maybe 1-2 every few months


       Mr. Rohde

      When you say 1 or 2 are you referring to a lender hiring you to issue a NOD and start the process of foreclosure ?

    • Jay HinrichsBusiness Member
      Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
      2y
      Quote from @Steve K.:
      Quote from @Ronnie C.:
      Quote from @Steve K.:

      Quote from @Pace Jordan Morby:

      We have had the due on sale clause called 4 times this month... but knowing your way around it is crucial. Either A: revert to a lease option with the option price being the mortgage balance when the option is executed... or B: Use an executory contract instead of SubTo. Land Contract. Contract for Deed. Agreement for Sale etc. I talk about this on my youtube channel. 


      Wouldn't the downside of doing any of those things be that if the existing owner gets any liens or judgments, they will still attach to the property? If so that's a big additional risk for the buyer. Also I don't think it's that clear that any of these tactics would actually prevent the bank from enforcing the due on sale. For example according to this, it seems that transferring the title is not required for the DOS to be triggered:

      http://law.justia.com/cfr/title12/12-5.0.1.1.54.0.83.2.html

      From the bank definition of sale or transfer: "For purposes of this definition, a sale or transfer means the conveyance of real property of any right, title or interest therein, whether legal or equitable, whether voluntary or involuntary, by outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests."

      That reads to me very clearly that the granting of any legal or equitable interest in or to a property secured by a mortgage can trigger the DOS, which would include any lease option, land contract, contract for deed etc. as it clearly states in the defintion. I'm not a lawyer or anything, this is just coming from what I've learned on here, there are many valuable old threads about this topic on here like this one:

      https://www.biggerpockets.com/forums/83/topics/86029-subject....

      and this one:

      https://www.biggerpockets.com/forums/311/topics/183825-due-o..

      How is it working our for you in practice?

      They/"US Bank" took a house from me that had never been behind or late. By the grace of GOD the tenant/buyers were wanting out, and they had never been late or missed a pyment. Took good care of the property as well. 

       I told them they could stay there at no charge till the bank evicted them and made them sign a hold harmless. Thank GOD I didn't get sued! 

      Oh I tried everything. Even my mentor at that time and this was 15 years ago, tried getting on the phone with them. He offered them several senarios like Pace talks about. They couldn't be reasoned with. They had no common sense what so ever.  He had over 120 houses sub to at that time as well, and was in complete shock!! 

      I told them that it'd be over a year that they will miss this income/payments, plus added cost of attorneys, property management and selling fees. 

      Over a year later it finally sold and they lost their BUTT!!! 

      I will not touch another sub to EVER again. There is nothing like being able to sleep at night knowing I have title to my houses that I buy with cash or loans and no one can take them from me on a whelm. (long as loan is paid) 

      By the way, I had this house 2 years at the time and the loan was low interest for that time. 

      Don't say: it never happens, or it will never happen to me cause I have strategies around it! It can and WILL happen again. 

      I still get sick thinking about it. 


      Sorry that happened to you. That seems like a more realistic result than just “talking to the bank” and having them agree to let the arrangement continue. Anyone who has ever tried to talk to the bank about anything knows how that goes. Watching some of these videos and finding lots of red flags like that which beginners wouldn’t catch but experienced folks will know is b.s. For example there is one video where at the beginning he says he had never dealt with the DOSC before and he called up the bank president, and asked him what to do, and the bank president actually tells him to use an executory contract and at that point he says he had used that method plenty of times before… so was is the first time or were there several times before? It’s obviously a made up story and the idea of getting the bank president on the phone is preposterous. In that story the bank president looks through a file cabinet to find the file. Sorry that’s just absurd and unbelievable. I’m surprised people don’t see through these gaping holes in the stories in these videos. Even in his main commercial that keeps popping up on my feed, he says at the beginning how he learned all about creative financing from his dad early on, and then less than a minute later he says he wishes he had learned these techniques earlier so he didn’t waste so many years breaking his back as a carpenter… which one is it? I’m surprised more people haven’t caught these self-contradictions and obviously fake stories. 

      so lets talk reality here..  talking to the Bank its going to be far and few between that the mortgages these folks are taking sub to is still owned or controlled by the "Bank" the loans were sold within months of origination and maybe MERS has it ( sliced and diced) and for sure your dealing with a servicer.. who is not going to negotiate one bit.. now if you happen to have a sub to with a portfolio lender and you can actually talk to someone who is a decision maker thats different but I submit those loans will be a small fraction of the deals being done.

      One of my sub to's back in the day the loan was portfolio with a small town CU and when we took it over the seller walked in and told them what they did.. And about a week later I get the notice from the bank that the Alienation of title clause in the debt instrument is being invoked and I had a short window to pay it off or they were going to foreclose.. We paid it off.  In my mind you MUST have the cash to these mortgages off if your going to engage in these transactions.
    • Realtor · Boulder, CO · Member since 2016 · 3k+ posts · 5k+ votes
      2y
      Quote from @Jay Hinrichs:
      Quote from @Steve K.:
      Quote from @Ronnie C.:
      Quote from @Steve K.:

      Quote from @Pace Jordan Morby:

      We have had the due on sale clause called 4 times this month... but knowing your way around it is crucial. Either A: revert to a lease option with the option price being the mortgage balance when the option is executed... or B: Use an executory contract instead of SubTo. Land Contract. Contract for Deed. Agreement for Sale etc. I talk about this on my youtube channel. 


      Wouldn't the downside of doing any of those things be that if the existing owner gets any liens or judgments, they will still attach to the property? If so that's a big additional risk for the buyer. Also I don't think it's that clear that any of these tactics would actually prevent the bank from enforcing the due on sale. For example according to this, it seems that transferring the title is not required for the DOS to be triggered:

      http://law.justia.com/cfr/title12/12-5.0.1.1.54.0.83.2.html

      From the bank definition of sale or transfer: "For purposes of this definition, a sale or transfer means the conveyance of real property of any right, title or interest therein, whether legal or equitable, whether voluntary or involuntary, by outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests."

      That reads to me very clearly that the granting of any legal or equitable interest in or to a property secured by a mortgage can trigger the DOS, which would include any lease option, land contract, contract for deed etc. as it clearly states in the defintion. I'm not a lawyer or anything, this is just coming from what I've learned on here, there are many valuable old threads about this topic on here like this one:

      https://www.biggerpockets.com/forums/83/topics/86029-subject....

      and this one:

      https://www.biggerpockets.com/forums/311/topics/183825-due-o..

      How is it working our for you in practice?

      They/"US Bank" took a house from me that had never been behind or late. By the grace of GOD the tenant/buyers were wanting out, and they had never been late or missed a pyment. Took good care of the property as well. 

       I told them they could stay there at no charge till the bank evicted them and made them sign a hold harmless. Thank GOD I didn't get sued! 

      Oh I tried everything. Even my mentor at that time and this was 15 years ago, tried getting on the phone with them. He offered them several senarios like Pace talks about. They couldn't be reasoned with. They had no common sense what so ever.  He had over 120 houses sub to at that time as well, and was in complete shock!! 

      I told them that it'd be over a year that they will miss this income/payments, plus added cost of attorneys, property management and selling fees. 

      Over a year later it finally sold and they lost their BUTT!!! 

      I will not touch another sub to EVER again. There is nothing like being able to sleep at night knowing I have title to my houses that I buy with cash or loans and no one can take them from me on a whelm. (long as loan is paid) 

      By the way, I had this house 2 years at the time and the loan was low interest for that time. 

      Don't say: it never happens, or it will never happen to me cause I have strategies around it! It can and WILL happen again. 

      I still get sick thinking about it. 


      Sorry that happened to you. That seems like a more realistic result than just “talking to the bank” and having them agree to let the arrangement continue. Anyone who has ever tried to talk to the bank about anything knows how that goes. Watching some of these videos and finding lots of red flags like that which beginners wouldn’t catch but experienced folks will know is b.s. For example there is one video where at the beginning he says he had never dealt with the DOSC before and he called up the bank president, and asked him what to do, and the bank president actually tells him to use an executory contract and at that point he says he had used that method plenty of times before… so was is the first time or were there several times before? It’s obviously a made up story and the idea of getting the bank president on the phone is preposterous. In that story the bank president looks through a file cabinet to find the file. Sorry that’s just absurd and unbelievable. I’m surprised people don’t see through these gaping holes in the stories in these videos. Even in his main commercial that keeps popping up on my feed, he says at the beginning how he learned all about creative financing from his dad early on, and then less than a minute later he says he wishes he had learned these techniques earlier so he didn’t waste so many years breaking his back as a carpenter… which one is it? I’m surprised more people haven’t caught these self-contradictions and obviously fake stories. 

      so lets talk reality here..  talking to the Bank its going to be far and few between that the mortgages these folks are taking sub to is still owned or controlled by the "Bank" the loans were sold within months of origination and maybe MERS has it ( sliced and diced) and for sure your dealing with a servicer.. who is not going to negotiate one bit.. now if you happen to have a sub to with a portfolio lender and you can actually talk to someone who is a decision maker thats different but I submit those loans will be a small fraction of the deals being done.

      One of my sub to's back in the day the loan was portfolio with a small town CU and when we took it over the seller walked in and told them what they did.. And about a week later I get the notice from the bank that the Alienation of title clause in the debt instrument is being invoked and I had a short window to pay it off or they were going to foreclose.. We paid it off.  In my mind you MUST have the cash to these mortgages off if your going to engage in these transactions.

       Yeah I've had issues when my loans have been sold and with loan servicing companies processing payments before and things like that. Getting anyone on the phone who knows how to take care of even the simplest issue is challenging enough. The idea of the actual bank president picking up the phone and thumbing through an actual file cabinet to find the paper file himself personally is hilarious. I don't see how his students believe these obviously made up stories. 

    • V.G JasonPro Member
      Investor · Member since 2022 · 3k+ posts · 3k+ votes
      2y

      If he's made over $35million in guru fees, yet this niche market is a sub $100M market how is this really sub-to training instead of just guru propaganda? The market to teach it is 1/3 the market itself?

    • Realtor · Boulder, CO · Member since 2016 · 3k+ posts · 5k+ votes
      2y
      Quote from @Account Closed:
      Quote from @Chris Seveney:
      Quote from @Steve K.:

      Reviving this old thread... Have we seen an uptick in DOSC six months later?

      Pace said he had 4 in one month earlier in this thread and in this video from a few months ago he says he's had 10 now. Later in the video he says his students have had 12: https://www.google.com/search?q=pace+morby+due+on+sale+claus...

      So that's a big increase considering he said he had seen zero previously among himself or his students. He also says that he's using an executory contract (or land contract in Texas) to get around them and has never lost a house. 

      He does not mention any downside to reverting to an executory contract/ lease option/ land contract. 

      My understanding is that although it can work, these types of legal agreements have big downsides compared to sub to. For example unlike sub to, in an executory or land contract the seller stays in title which means all the risks are there for them getting liens and having those attach to the property or other typical title problems, plus having to pay closing costs and having a new higher rate when you need to eventually exercise the option. That's not exactly a good alternative to sub to. 

      Also, even if it's true that is has been working to avoid the DOSC so far, my understanding is that any "outright sale, deed, installment sale contract, land contract, contract for deed, leasehold interest with a term greater than three years, lease-option contract or any other method of conveyance of real property interests" can trigger the DOSC (quoting the bank definition of transfer or sale), meaning that banks could still call these loans due despite the executory contract/land contract if they so choose. 

      Is anyone else seeing an uptick in DOSC being called besides Pace and his students?

      @Account Closed @Tom Gimer @Chris Seveney @James Hamling @Jay Hinrichs


      I have not seen an uptick, but I also do not deal in the subto world. I have not heard a lot about it either. Why? Most likely because the residential market is a $12T market and my guess the amount loans sold via UPB on subto is less than $100M a year. I know Ken and Mike and their team are successful at it along with William Tingle, but they are realistic and not making it sound like its a trillion dollar industry like others make it out to be.

      I just responded to a "Subto student from the "community"  with this

      ********************************* 

      His comments; Pace teaches several strategies with due on sale.

      My Response:

      @Luis Ramos: First, I want to thank you for taking the time to engage the post here.

      Now referring to Your Comment:

      "then deed back the property to seller and using a title company perform an executory contract. Secondly, if this fails, he offers insurance through Equity Assurance that basically pay offs the underlying note through refinance. If this fails, then perform a land trust strategy"

      Please don’t take this as disputing your sincerity. I do believe you are sincere. This is simply addressing common misconceptions Mr. Morby either knows aren’t true and has an agenda to make people think they are true, or he is terribly misinformed. I’m not sure of which.

      I know this is a very looonnng post, but it is packed with what anyone in Mr. Morby’s “community” or anyone considering Mr. Morby’s “community” needs to be advised of and consider. This is not an exhaustive list. Just addressing the comments made previously.

      The Subto “community” is 4 blind men describing an elephant (look it up) and perpetuating wrong information.

      Yes, Subject To is legal when you do it legally and safely.

      However, Here Is Reality:

      1. When you deed the property back to the seller, you create all sorts of problems.
      2. But, Take hope, there are solutions. However, Mr. Morby is not presenting those solutions, whatever his motive may be. But, let’s see, he claims 4,000 students at the previous $8,800 fee, so about $35,200,000 he has made on this. That doesn’t go unnoticed by regulators. I think he has since bumped up his fee.

      So, here we go:

        1. Deeding back Does Not Stop the Due on Sale. You have already violated the DOS and the bank can choose to foreclose regardless of any further actions you take.
        2. You can not "un-ring the bell". Once the DOS has been violated, it has been violated.
        3. Yes, banks are enforcing the DOS.
        4. It actually “red flags” the account at the bank for further review.
        5. As the bank looks, then sees Two deed transfers in such a short time on one property, then another transfer to a Land Trust and the loan isn’t being paid off, hmm, they say, “something fishy is going on here and it may be illegal”.
        6. Contrary to popular belief, banks aren’t stupid.
        7. No bank is going to risk liability to protect you and ignore that you violated the DOS. That's crazy talk.
        8. You have messed up the bank’s underwriting risk liability on that account. That is not a small thing.
        9. Banks are audited for “suspicious account activities” and a notice gets sent to the FBI. Part of the “Homeland Security thing” You know, drugs, terrorism, etc
        10. You can be sued and criminally charged for up to 7 years after the transaction. How lucky do you feel?
        11. Banks will probably increase their enforcement because Mr. Morby has made it a mockery by saying things like “banks don’t care” , “people who have No Money can buy using Subject To’, “he can buy overleveraged properties”, “he can use gator lenders” for closing and carrying costs”, and he can change the status of the title if he gets caught. That is all sufficient to establish a fact pattern of actions that will have serious consequence for him.
        12. If I was the FBI, I assure you I am not, I would join the Subto “community” and start gathering what I need in order to bring charges and win my case.
        13. Hmmm, I wonder if it would fall under the RICO statutes. Just kidding (sort of).
        14. A lawsuit will cost you $25,000 to $125,000 and a year and a half of your life. With no guarantee of winning. Yes, the seller can sue you. The state can sue you. The Federal govt can sue you. Over what you say? "I haven't done anything wrong". Then why did the DOS get called? Why did you violate those state laws you aren’t even aware of?
        15. Subject To is legal, when done legally. But what I never see addressed are the secondary violations that uneducated Subject To investors inevitably commit. That takes experience to know about. From what I’ve seen, that maturity and experience is sadly lacking in the “community”. Or, do you think regulators are as dumb as a brick?
        16. I go on, The seller has no obligation to take it back
        17. If the seller takes it back, they have no obligation to resell to you, and they might not and there is nothing you can do about it.
        18. The seller likely won’t play that game, they will lose trust in your ability to do Subject To legally and safely and refuse to transfer back.
        19. You may not be able to even find the seller to try to transfer back.
        20. If you do Subject To incorrectly and the DOS gets called, you may not even learn about it until it's too late. Too bad, so sad.
        21. There are additional closing costs that have to be paid
        22. You may trigger an investigation by regulators
        23. Each time you change title it’s likely that taxes are due – explain that to the IRS
        24. You’ve messed up title insurance big time
        25. You have probably invalidated the homeowner’s/landlord insurance.
        26. If any of this confuses you, DO NOT DO SUBJECT TO until you are taught properly

      That’s what comes immediately to mind from my 30 years of doing & teaching Subject To

      1. Executory Contracts by definition violate the same Due on Sale that just got called
        1. Here is the actual wording of the Due on sale clause

      18. Transfer of the Property or a Beneficial Interest in Borrower. As used in this Section 18, "Interest in the Property" means any legal or beneficial interest in the Property, including, but not limited to, those beneficial interests transferred in a bond for deed, contract for deed, installment sales contract or escrow agreement, the intent of which is the transfer of title by Borrower at a future date to purchaser.

      1. In a recent video he said he has discontinued “Equity Assurance”
        1. Has he restarted it?
        2. I believe he has totally walked away from any kind of “Assurance” program. Assurance is NOT Insurance.
      1. Land Trust – he says in his recent video on Due on Sale that he has had 10 Due on sales called recently and his students have had a couple of dozen called, that they had put into Land Trusts
        1. Facts are stubborn things. Land Trusts don’t work.

      Any reference to Mr. Morby comes from videos he has recently released on youtube and is publicly available.

      I would be curious though, to see if Mr. Morby says something in his groups that isn’t covered here. Can you check with the folks at Discord and get updated information?

      Click to enlarge

      Very short answer is yes I've had the due on sale clause called on me 10 times

      real estate the bank doesn't care if you buy the house subject to


      executory contract becasue it gets rid of the due on sale clause altogether


      20,000 of those members are actual trained students of mine


       Thank you Ken, for laying it all out. Here I was beginning to think I was the crazy one.

    • Morris County, NJ · Member since 2020 · 5k+ posts · 2k+ votes
      2y

      @V.G Jason Yeah, that's probably a big clue that something is wrong.  But, I feel lots of these video influencers basically draw a "cult-like" following, for lack of better term.  

      Also, how was the $100m market size determined?  Sorry if it was in this thread, with all the replies its too much to scroll through.  If its by the loan size of the loans being affected by subj-to then, its not even what people are really making, at least in the near term.  In subj-to people are "saving/making" money from the interest differential in using the old loan.

      Anyway, i guess there are multiple ways to consider it.  But, it seems people have paid more money to him than whats been "saved" using this technique...

    Join the conversationCreate a free account to reply, vote on answers and follow this thread.