HELP!! I need loan advice!
Investor · Member since 2023 · 73 posts · 32 votes
Right now I'm getting a triplex inspected for purchase in lake Charles, Louisiana and I'm trying to work with a local lender. They said they cannot do 10% down with PMI because they said if it's three doors they consider it more commercial so they're offering me 15% down but my rate is 8.75%. they also told me it was a dscr but on the disclosure they have conventional checked off right now I told then we need to talk more but to be honest I've only used them so far. I'm tempted to start shopping around and I was curious what anybody had to say on this platform in regards to this. My credit score is at 810 and I have very low debt.
Broker here -- the rate environment is a mess right now with everything moving this week, so 6.5% at 25% down on a triplex from a local lender is actually pretty decent if it's truly a conventional product with no points. Rocket at 6.99% was pricing you retail and not shopping it, so good move to go local.
On the DSCR confusion: what your first lender called "conventional/non-QM" and "DSCR" in the same breath is typical of a shop that doesn't know how to explain their own product. DSCR is a non-QM loan. Conventional is Fannie/Freddie. They're not the same thing. If the disclosure says conventional, that's what it is, but at 8.75% with 15% down that's not a conforming rate at all, so something was off with that quote.
The $125k DSCR minimum issue is real. At 20% down on a $150k property your loan is $120k, and a lot of the bigger non-QM shops won't touch files under $100k or $125k. Even the ones that go lower price you at a heavy penalty. On a file like this, conventional is probably the better path anyway. DSCR closing costs run 2-3 points on top of lender fees, which eats a lot of return on a smaller loan.
You can shop around but 15% down payment will have higher rates, have you checked what 20-25% down would show? Also many lenders won't do 15% down so keep that in mind.
I see, ok, Ill ask what rates I could get with more down. I'll let you know what they say!
@Caleb Brown Just got off the phone with rocket mortgage, they said I have to put 25% down for an investment property, but my rate would be 6.99%. I'm going to see what the local lender says.
@Caleb Brown Just got off the phone with rocket mortgage, they said I have to put 25% down for an investment property, but my rate would be 6.99%. I'm going to see what the local lender says.
@Caleb Brown Just got off the phone with rocket mortgage, they said I have to put 25% down for an investment property, but my rate would be 6.99%. I'm going to see what the local lender says.
Ok, thanks, didnt even think about closing costs. I told him to just shoot me the quote via email and Ill keep it in my back pocket.
I did learn that you need to put 20% for a DSCR and the base amount needs to be above 125K. So since the property I was looking at is 150k I would not qualify for a DSCR because the base amount would be 120k....I would be 5k short.
Hey Richard!
Two sides of things here:
1. I don't know the deal in entirety but 8.75% at 15% down on a 3 unit building isn't terrible. Since DSCR does not have Mortgage Insurance the rate with less than 20% down it's just way higher than need be, I would hope they showed you the alternative of 20% down. You could see a full 2% difference in rate depending on again prepayment penalties and points.
I would hope they're at least not making you pay points though, and what kind of prepayment penalty were you considering? I would not recommend above a 1 year 15% down since your equity will grow and you'll have the opportunity to refinance to a lower rate.
2. it's actually not abnormal for some documents to read conventional even on a DSCR loan. even though it is a non-qualified mortgage it is in the same family as conventional. So no need to be alarmed about that
if you do have other questions or if it'd be helpful to go through some possible other options feel free to reach out. Not physically located in Louisiana though I am familiar my college roommate grew up on the east side of the state in Patterson
She wrote me back, she said It is conventional/non QM. That is the way the DCSR is reflected in the system. She is alos going to look into what difference it would make if I put more down. I'll also ask about prepayment penalty, and what my options are there. Thanks for reminding me. Completely forgot about that as well.
Hey Richard!
Two sides of things here:
1. I don't know the deal in entirety but 8.75% at 15% down on a 3 unit building isn't terrible. Since DSCR does not have Mortgage Insurance the rate with less than 20% down it's just way higher than need be, I would hope they showed you the alternative of 20% down. You could see a full 2% difference in rate depending on again prepayment penalties and points.
I would hope they're at least not making you pay points though, and what kind of prepayment penalty were you considering? I would not recommend above a 1 year 15% down since your equity will grow and you'll have the opportunity to refinance to a lower rate.
2. it's actually not abnormal for some documents to read conventional even on a DSCR loan. even though it is a non-qualified mortgage it is in the same family as conventional. So no need to be alarmed about that
if you do have other questions or if it'd be helpful to go through some possible other options feel free to reach out. Not physically located in Louisiana though I am familiar my college roommate grew up on the east side of the state in Patterson
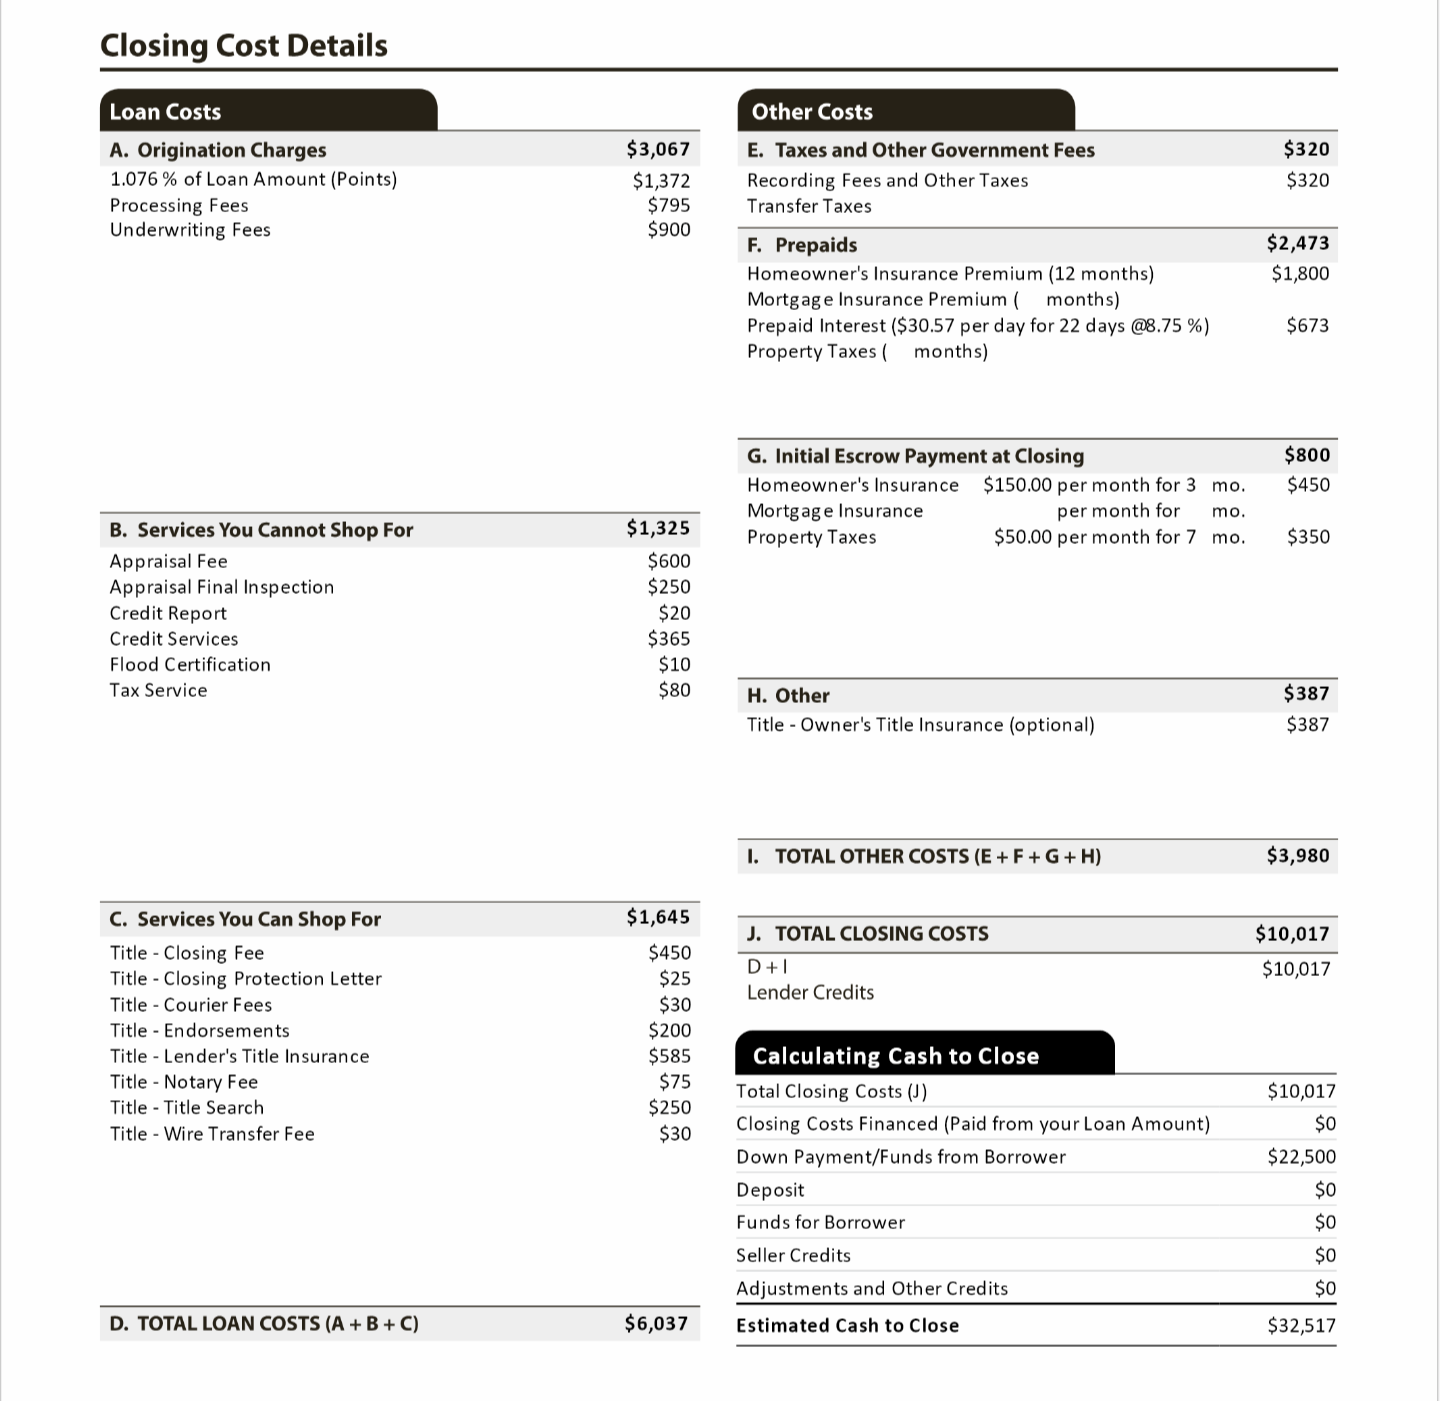
@Richard Billingsley thats pretty fair for this situation assuming a 0 or a 1 year prepayment penalty. Erik is right if you take a higher prepayment penalty then you may see high 7's. Rates changed a lot this week so make sure it's locked
@Richard Billingsley thats pretty fair for this situation assuming a 0 or a 1 year prepayment penalty. Erik is right if you take a higher prepayment penalty then you may see high 7's. Rates changed a lot this week so make sure it's locked
Right now I'm getting a triplex inspected for purchase in lake Charles, Louisiana and I'm trying to work with a local lender. They said they cannot do 10% down with PMI because they said if it's three doors they consider it more commercial so they're offering me 15% down but my rate is 8.75%. they also told me it was a dscr but on the disclosure they have conventional checked off right now I told then we need to talk more but to be honest I've only used them so far. I'm tempted to start shopping around and I was curious what anybody had to say on this platform in regards to this. My credit score is at 810 and I have very low debt.
8.75% is pretty high. Realistically on an 85% LTV DSCR loan you should be in the mid to high 7s. If you put 20% down you'd be looking at 6s range.

Ok the local lender got back with me. They are able to get a 25% down, 6.5 rate. The market is going crazy right now... No points added and no lenders credits.
Broker here -- the rate environment is a mess right now with everything moving this week, so 6.5% at 25% down on a triplex from a local lender is actually pretty decent if it's truly a conventional product with no points. Rocket at 6.99% was pricing you retail and not shopping it, so good move to go local.
On the DSCR confusion: what your first lender called "conventional/non-QM" and "DSCR" in the same breath is typical of a shop that doesn't know how to explain their own product. DSCR is a non-QM loan. Conventional is Fannie/Freddie. They're not the same thing. If the disclosure says conventional, that's what it is, but at 8.75% with 15% down that's not a conforming rate at all, so something was off with that quote.
The $125k DSCR minimum issue is real. At 20% down on a $150k property your loan is $120k, and a lot of the bigger non-QM shops won't touch files under $100k or $125k. Even the ones that go lower price you at a heavy penalty. On a file like this, conventional is probably the better path anyway. DSCR closing costs run 2-3 points on top of lender fees, which eats a lot of return on a smaller loan.
Good luck with it. If that 6.5% isn't locked yet, get it done today -- rates were up again this morning and this market can move fast.
Good luck with it. If that 6.5% isn't locked yet, get it done today -- rates were up again this morning and this market can move fast.
Monday you'll be locked and ready to go. Good luck with it.
Rates are going to be different depending on the loan product and the mortgage broker and lender you are working with. Rates in the 6s and 7s are doable as of the date of this posting if your credit is higher as mentioned and you are putting more money down. If you are not doing a conventional/ debt to income (DTI) loan where the loan is structured around your debt to income ratios, then investment property program guidelines such as DSCR programs will vary based on the mortgage broker and/or lender you're working with. There's often overlap for DSCR programs but what can vary between lending companies is LTV limits depending on the property, the money needed to put down for the property or programs specifically for short term rentals (STRs) among other guideline differences.

Right now I'm getting a triplex inspected for purchase in lake Charles, Louisiana and I'm trying to work with a local lender. They said they cannot do 10% down with PMI because they said if it's three doors they consider it more commercial so they're offering me 15% down but my rate is 8.75%. they also told me it was a dscr but on the disclosure they have conventional checked off right now I told then we need to talk more but to be honest I've only used them so far. I'm tempted to start shopping around and I was curious what anybody had to say on this platform in regards to this. My credit score is at 810 and I have very low debt.
You’re right to pause here — a few things in that scenario don’t fully line up.
First, a true DSCR loan wouldn't be labeled as "conventional" on disclosures, and it typically wouldn't involve PMI. That alone is worth getting clarified because it sounds like they may be trying to fit the deal into a box that doesn't quite match the product.
Second, for a triplex, most lenders fall into two buckets:
Residential (1–4 units) → conventional or DSCR
Commercial (5+ units)
So calling a 3-unit “commercial” is a bit of a stretch — some banks do it internally, but it’s not standard across the board.
On the terms:
15% down at 8.75% isn’t crazy in today’s market, but with your 810 credit and low debt, you should definitely have options to compare
Especially on a DSCR product, where the focus is more on the property's income vs. your personal profile
Bottom line: you should absolutely shop this.
Not because it’s a bad deal — but because:
You want clarity on the loan type
You want to compare structure (DSCR vs conventional)
And make sure you’re not leaving better terms on the table
At JCREIG Capital Funding, we work with investors on small multifamily like this all the time:
DSCR loans (no income docs, no PMI)
Flexible down payment options
Clear structure so you know exactly what you’re getting
If you want, I can take a look at the deal and show you how it would be structured on our side so you can compare apples to apples before making a decision.
Yeah sure but I heard the market is crazy right now and to lock in rates now before they jump up. Are you licenced in Louisiana?
I completely understand—there’s definitely been a lot of movement in the market lately, so it makes sense to explore your options carefully.
We actually work with many investors out of Louisiana. If you’d like, I can take a look at your deal and walk you through how it would be structured on our side. That way, you can compare everything apples to apples before making a final decision and feel confident you’re choosing the best option. Let me know.
Ok, I sent you a message!
Richard, you’re right to pause—there are a couple things here that don’t fully line up.
A triplex is still considered residential (1–4 units), so it shouldn't automatically be treated as commercial. Also, DSCR and conventional are two completely different loan types, so seeing both mentioned like that is definitely worth clarifying.
With an 810 score and low debt, you should generally have multiple options, including lower down payment structures depending on how the property is being classified (owner-occupied vs investment).
The 15% down / 8.75% might not be wrong but it’s very scenario-specific, and I wouldn’t rely on a single lender here, especially with mixed signals.
At a minimum, I’d get a second opinion just to compare structure, not just rate small differences in setup can have a big impact on your long-term numbers.
Are you occupying the property or is this an purely an investment property?
Are you occupying the property or is this an purely an investment property?
A few things worth clarifying here.
The lender is right that triplexes are treated differently — most conventional lenders require 15-25% down on a 3-unit property and won't allow PMI. That part checks out.
But 8.75% for an 810 credit score with low debt is significantly above market even for investment property. Current market for a 3-unit conventional purchase with 15% down and that credit profile is roughly 7.25-7.75% depending on the lender. You're being quoted nearly 1% above where you should be.
The DSCR vs conventional discrepancy on the disclosure is a real red flag. Those are completely different loan products with different underwriting. Get clarity on exactly what loan type they're originating before proceeding.
With an 810 score you have strong negotiating leverage. Get at least two more quotes from lenders who specifically do investment property financing — a local credit union and a mortgage broker who works with investors. The broker especially will have access to multiple lenders competing for your business.
There's a tool that benchmarks rates against actual market data if you want to verify what's competitive for your specific profile before locking — fairrate.online. No lender affiliation.
Right now I'm getting a triplex inspected for purchase in lake Charles, Louisiana and I'm trying to work with a local lender. They said they cannot do 10% down with PMI because they said if it's three doors they consider it more commercial so they're offering me 15% down but my rate is 8.75%. they also told me it was a dscr but on the disclosure they have conventional checked off right now I told then we need to talk more but to be honest I've only used them so far. I'm tempted to start shopping around and I was curious what anybody had to say on this platform in regards to this. My credit score is at 810 and I have very low debt.
Hey Tanya,
There are a few moving parts here, and some of what you were told may depend on occupancy, loan type, and how the property is being classified.
A triplex can often fall under residential financing, but terms can vary based on owner-occupied vs investment, conventional vs DSCR, reserves, and lender overlays.
With an 810 score and low debt, I’d definitely want full clarity before proceeding—especially if the disclosures don’t match the conversations so far.
Sometimes the biggest issue isn’t the property—it’s being placed with the wrong loan structure.
quick question - did they explain why they classified it that way?
No they didn't. I walked away from the deal and now am working with a DSCR broker called harmonical.ai. Thanks for helping, you're awesome.
Right now I'm getting a triplex inspected for purchase in lake Charles, Louisiana and I'm trying to work with a local lender. They said they cannot do 10% down with PMI because they said if it's three doors they consider it more commercial so they're offering me 15% down but my rate is 8.75%. they also told me it was a dscr but on the disclosure they have conventional checked off right now I told then we need to talk more but to be honest I've only used them so far. I'm tempted to start shopping around and I was curious what anybody had to say on this platform in regards to this. My credit score is at 810 and I have very low debt.
Lenders that do conventional / DTI-based loans / DSCR Loans have to jam different things into systems not meant for it (i.e. a triplex into a system built for vanilla properties) -- so confusing boxes will be checked and you'll likely end up dealing with this sort of thing. If DSCR is your only option for whatever reason (if thats what they are saying to you), you are probably better off going with a national broker/lender that does DSCR Only or else it'll likely be a mess (which it sounds like it already is)

No, thank you. I actually found a team on Harmonial.ai that is really good. I actually walked away from that property after the inspection. But you're right, finding a broker is the way to go.
nice!! you have to let me know about them. Hopefully it works out for you buddy. Happy friday :)
You need to pull your file and shop this deal immediately. Your lender is completely misrepresenting the guidelines. A triplex is not a commercial asset—it falls strictly under residential 1-4 unit guidelines. Furthermore, if they have 'Conventional' checked on your disclosure, it is not a DSCR loan. They are running a full-documentation personal loan while charging you an inflated 8.75% business rate.
Here is the reality for an investment triplex: Under true conventional rules, you cannot do 10% down (the absolute floor is 15% down with PMI). However, with your 810 credit score and low debt, your conventional interest rate should be significantly lower than 8.75%
In my honest opinion you have 2 options available:
(1)
Take your deal to a dedicated residential mortgage broker today. Ask them for a standard Conventional 15% Down Investment Loan. You will easily clear their underwriting, keep your down payment at 15%, and slash that interest rate dramatically
(2)
Utilize a institutional non-QM platform. They recognize that a triplex is a residential 1-4 unit asset, avoiding the inflated 8.75% 'commercial' pricing your local bank is trying to apply
By running this through a specialized investor platform, you can lock in a clean Conventional 15% Down Investment Mortgage that actually mirrors your 810-credit profile. Alternatively, you can pivot to their True DSCR program, which entirely ignores your personal tax returns and approves the loan based strictly on the triplex’s rental revenue.
Right now I'm getting a triplex inspected for purchase in lake Charles, Louisiana and I'm trying to work with a local lender. They said they cannot do 10% down with PMI because they said if it's three doors they consider it more commercial so they're offering me 15% down but my rate is 8.75%. they also told me it was a dscr but on the disclosure they have conventional checked off right now I told then we need to talk more but to be honest I've only used them so far. I'm tempted to start shopping around and I was curious what anybody had to say on this platform in regards to this. My credit score is at 810 and I have very low debt.
@Richard Billingsley
An 810 credit score and low debt put you in a strong position. Before switching lenders, I'd compare the full picture—not just the interest rate, but also the required down payment, PMI (if applicable), lender fees, and how they're classifying the property. One question: are you planning to owner-occupy the triplex, or is this strictly an investment purchase?
Everything is going to be just strictly investment. No owner occupied.
Just chiming in to the Conventional terminology
if my memory serves me correctly all conventional means according to the NMLS course is, that it's a 30-year fixed rate.
So yes, a DSCR can be classified as conventional even though it is not a confirming or qualified mortgage

