Does Velocity Banking work????
Member since 2019 · 187 posts · 74 votes
Hey everyone ive been hearing about and researching VELOCITY BANKING alot lately. Seems too good to be true. Any of you experts have experience in this field and can confirm or deny? Thanks everyone!
Nick
Paying off a low interest mortgage instead of acquiring profitable assets is counter intuitive to creating wealth. It's a distraction, it's just creating a fancy name "Velocity Banking" and treating it like a magic wand without testing the financial math behind the whole philosophy. It's a gimmick
@Victor S.
Thank you sir. Very much. My head was starting to hurt.
It’s like “if you use VB you have to make all these extra payments on your heloc and it goes so quick! VS just make minimum payments. See VB banking works!” Completing ignoring the tens of thousands of additional actually dollars from your wallet to your heloc over this 5 years.
This is like Gatorade saying “drinking Gatorade and five years of hard training beats drinking water and sitting on the couch every time!”
I just thought of “super duper light speed banking banking house hack system” just now. As soon as you buy your house sell everything else you own and write a check and pay off the mortgage of the first day. Boom! No mortgage payments ever! I need a book deal.
electrolytes. that's what the plants crave....
velocity banking does indeed sound intriguing, until you actually realize what it is.
... and what do you think it actually is? (Could be interesting to hear yet another misconception.)
paying your loan off early due to increased principal payments via saving more of your take-home income? obviously, this doesn't sound as catchy.
paying your loan off early due to increased principal payments via saving more of your take-home income? obviously, this doesn't sound as catchy.
Well, that would work if you have the cash flow, but that's not Velocity Banking.
So before this post dies has anyone actually found a bank that does this?? I have combed through the ghettos of the internet and have not found any bank that actually pulls directly to and from of a loan on a daily basis
So before this post dies has anyone actually found a bank that does this?? I have combed through the ghettos of the internet and have not found any bank that actually pulls directly to and from of a loan on a daily basis
That's not how Velocity Banking works.
That said, of course, some (HE)LOCs have a "checkbook" you can use like your regular checking account. Check with your lender. Ask them about the features of their Equity and personal / unsecured Line Of Credit products.
This subject has been beaten to death on BP several times.... will rocket to 10+ pages very quickly......
You will get a few that absolutely swear it works better than just making extra payments on the mortgage..... you can show them all the math you want and they wont budge......but the majority on BP feel otherwise
My opinion...... it can work.... but not any better than just making extra payments to the mortgage and is not even close to being worth the hassle to run the system to make it work.... so I passed
If accelerating your home loan is your only goal, then the whole Velocity Banking approach may be overkill for you.
There is MUCH MORE to Velocity Banking than just accelerating your home loan. That's just the prime example everyone uses of its benefits.
And what, pray tell, is the "MUCH MORE" of velocity banking, as defined by your MLL group?
Well, in the first place, my "group" is not MLM - never has been, is not now, never will be.
If you want to know about Velocity Banking, take the class. I'm not going to attempt to summarize 16 hours of material in a forum post.
If you were as clever as you like to think you are, you'd have figured it out by now, anyway. This thread alone includes all the pieces and then some.
Ahhhh you know someone is debating from a position of knowledge and confidence when they resort to ad hominem attacks about the those who disagree with them's intelligence and reading abilities.
We obviously have different definitions of MLM... And I'm sorry I don't need 16hrs of my time and $1600+ gone; [FV=PV(1+r)^t] tells me everything I need to know. Is that formula covered in any of the classes?
MLM - Multi-level Marketing has but one definition - Google is your friend. The organization I'm with does direct marketing - there's a distinct difference - and is modeled after the insurance industry.
The amortization formula (thanx for the refresher) and others may be discussed in more than one of the 60+ classes / 500+ hours of education we have available. We do not "teach" the mathematics of the financial / banking / lending industries, at least not much beyond Capitalization Rates, rates of return, and so on. For the rest of it, a financial calculator or an app to emulate one - I'm partial to 10Bii - suffices nicely. I have someone in my group who is quite fluent in Excel - his input was valuable developing my Loan Acceleration Example spreadsheet; for the rest, I fell back on my 37 years as a system programmer / IT developer.
Interesting, and you have said that you are an instructor in your MLM Direct Marketing group?
Show me where I said that ...
One of my mentors holds that you should "dig your well BEFORE you get thirsty".
It's already too late to do this. Had folks with equity in their home or other property that could be leveraged gotten a line of credit secured by their home or other property BEFORE the COVID-19 related shutdowns, they'd have the slack in their finances that they may need to weather any lay-offs or other loss of income they may experience during this time.
So, among the many benefits of Velocity Banking, be sure to include financial flexibility for when things go wrong in ways that few can foresee.
If you just pay extra on principal then lose your primary income, there's no fallback, no "slack in the budget". Using a (HE)LOC as your velocity account can provide slack when you need it.
Gotta have it ahead of time, of course. Laid-off with little or no income is no time to go looking for credit!
David that is a good point. I have been using the lines I have for awhile now. These lines are both in first lien position. I'm starting to wonder if these lines can be frozen or reduced during these times. Do you have a. opinion on this? Thanks.
David that is a good point. I have been using the lines I have for awhile now. These lines are both in first lien position. I'm starting to wonder if these lines can be frozen or reduced during these times. Do you have a. opinion on this? Thanks.
Dirk, I would suggest for anyone to contact their lenders before anything come up and see what can be done. Some banks have offered 0% interest to allow borrowers to pay down principal. Worse you can get is, "sorry we're not offering anything." I know Capital One has said they're not offering anything at this moment, but Discover has offered some breaks. Short answer: Call and speak with the lenders.
Hope this helps anyone who may have a similar question.
David that is a good point. I have been using the lines I have for awhile now. These lines are both in first lien position. I'm starting to wonder if these lines can be frozen or reduced during these times. Do you have a. opinion on this? Thanks.
I'd go with Sonny on this one. Contact your lender(s) and see what they offer, if anything.
i was gonna say, how will this tie into covid situation... it's all gravy until that heloc gets called by the bank.
Your first lien will likely get called first.
i was gonna say, how will this tie into covid situation... it's all gravy until that heloc gets called by the bank.
Your first lien will likely get called first.
To clarify, you are saying that if you have a first position mortgage and a HELOC on a property, the mortgage is more likely to get called first with the HELOC remaining unfrozen?
... and the answer is, as always, "It depends". Contact your lender about your own financial situation.
(Edit)
Let me expand on that a bit, since you don't understand Velocity Banking ...
If your first position lien goes into default, it may very well be that your velocity account ((HE)LOC, etc.) is still receiving your payroll or other direct deposits and so is either still current or less behind than an inflexible first with a fixed payment amount.
So, yes - the first lien is more likely to be called than the second.
Hope that helps ...
Gonna try to paste this from a Facebook post ... it's a graphic, so I can't just copy and paste the text ...
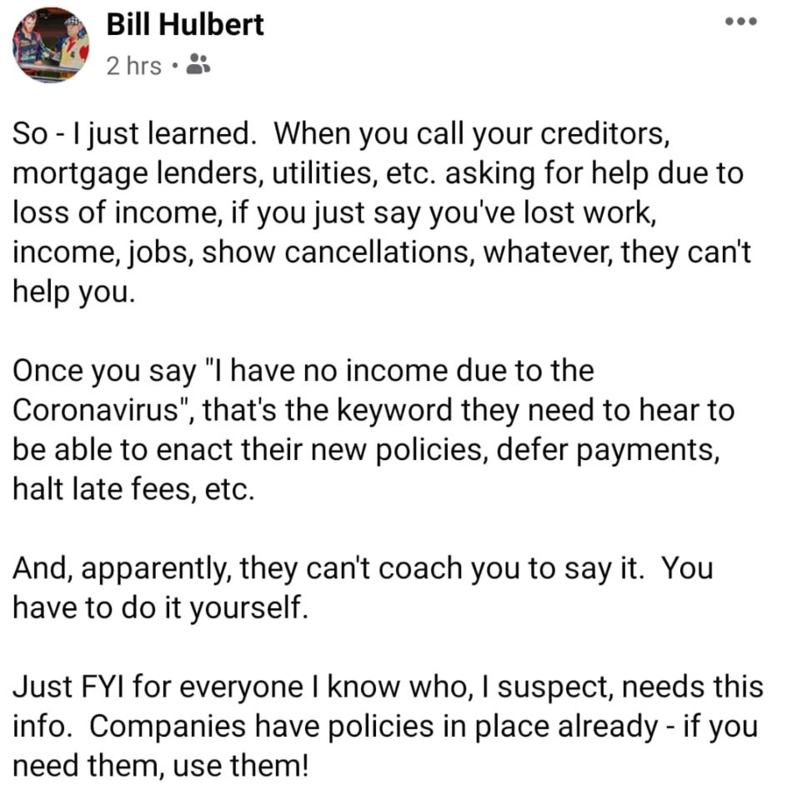
So, the key is to identify yourself as someone affected by the COVID-19 situation. That's "the key" to whatever they have which can help you, apparently ...
i was gonna say, how will this tie into covid situation... it's all gravy until that heloc gets called by the bank.
Your first lien will likely get called first.
To clarify, you are saying that if you have a first position mortgage and a HELOC on a property, the mortgage is more likely to get called first with the HELOC remaining unfrozen?
... and the answer is, as always, "It depends". Contact your lender about your own financial situation.
David, you said "Your first lien will likely get called first."
Did you mean by that statement that if you have a mortgage and a HELOC, on the whole, the mortgage is more likely to get called?
I am trying to clarify your position since your statement was unclear.
Sorry what I'm saying is the Heloc is in first position and there is no other lien. The properties were free and clear before opening the lines. The reason I was bringing it up was back in 2008 I was not investing and I heard a lot of stories about line reduction and lines being frozen. I just wanted to hear from someone that may have had that experience. Velocity banking is great I use it everyday and have for the last two years. It just makes me question paying off debt with big chunks and not knowing if my cash flow will fluctuate or dry up. The government has stopped eviction proceedings. That could cause even the best tenant to second guess paying. I know Bradon Turner has put out videos about dealing with tenants at this time but every tenant is different just like every unit is different. I guess it is best to have a uniform policy for this regardless if you have debt on units or not instead of a case by case basis. Then you hear stories of landlords of the year reducing or foregoing rent. I really cant agree 100 percent with that. Show me the money lol. That is the risk I guess with any loc it can catch you in the middle of velocity banking and catch you off guard.
I have recently started to use infinite banking as well. I like this a little better you build up a big reserve in whole life insurance policy then use that as your loc. Sorry not to.change the subject but using both those forms of banking together can be very powerful.