Curious if anyone has had any recent quotes on 30 year loans for an investment property.
I'm looking at something this weekend in Kentucky. Excellent credit and a 30% downpayment. My credit union quoted me 6.375% but they won't finance a log home. The in-state lender recommended by my realtor quoted me 7.0% if I paid $1300 towards points, which to me seemed ridiculous; back in April when we put an offer down on a property in Indiana we were quoted 7.0 without points. I'm trying to figure out which of these is the anomaly.
Hey @Dina Schmid, so things are really in flux right now and I expect to see some better rates in a couple weeks.
The best I have seen locally are from smaller lenders. Local S&L's and credit unions.
5.99% with no points right now is the best I have seen. It is for WA state properties only.
Thanks. I'd love to get 5.99% without points. Makes me think the 7.00% with a points (it was a fraction of a point, but still) is the anomoly and I can do better.
Any tips on how to find them from out of state? I'm looking in a neighboring state, at an area 2.5 hour drive from home.
So what I would do is look at all registered lenders in the states surrounding your state.
Look for "local" lenders. That can be hard to tell. Bank of America, obviously national. Bluegrass Savings and Loan, Volunteer State Credit Union...that sort of thing.
Here there is Olympia Federal. Portfolio lender that only lends in WA state.
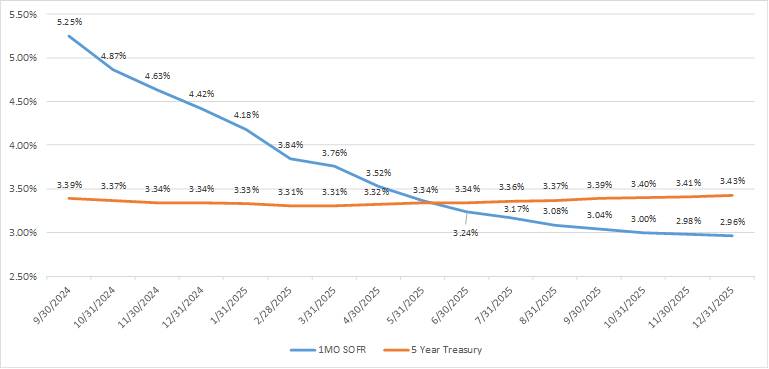
Echoing what many others are stating here. Rates and LLPAs move around all the time with lenders. There is some element of timing when getting pricing. A FED reduction of 0.50bps does NOT mean rates will drop 0.50%. People misunderstand this all the time. Most mortgage companies follow one of these indexes; 5yr Treasury Bond, 10yr Treasury Bond, SOFR, or WSJ (mostly Hard Money follows this one). Watch how these indexes move and you will get a much better sense of how the markets are actually reacting.
STRs usually have a pricing hit to them versus a LTR with most lenders as well. I am closing LTRs in the low 6's to mid 6's with 1yr prepayment penalties at par pricing (no points) at 75LTV on purchases right now. Changing that to STR pushes the rate up to mid to high 6's, possibly low 7's. That could change in two weeks... Lol.
Any tips on how to find them from out of state? I'm looking in a neighboring state, at an area 2.5 hour drive from home.
So what I would do is look at all registered lenders in the states surrounding your state.
Look for "local" lenders. That can be hard to tell. Bank of America, obviously national. Bluegrass Savings and Loan, Volunteer State Credit Union...that sort of thing.
Here there is Olympia Federal. Portfolio lender that only lends in WA state.
The time you spend could save you a full point.
Thanks for taking the time to answer my quetion. Really appreciate it! I will start searching and calling around this afternoon.
Do you have access to a LOC in some way? I just got a 4.99% rate but it is a 3 year lock 30 year amortization or a 5.25% 1 year interest only. I'm likely taking the 1 year interest only and will refi then. My regular LOC is charging 7% today without points but it changes daily. I'm happy with a one year interest only commitment as I don't think the rates will get to there that quickly. BTW, this is with Morgan Stanley.
You are going to have an issue with it being a true log home. A lot of lenders don't want to touch those. Are you sure its a true log home and isn't just a stick built home with log siding and tongue and groove on the inside?
As for rate, it is an investment property so I don't know of anybody getting 6 or below on investment. But 6.5 should be doable. Maybe 6.25 even.
Do you have access to a LOC in some way? I just got a 4.99% rate but it is a 3 year lock 30 year amortization or a 5.25% 1 year interest only. I'm likely taking the 1 year interest only and will refi then. My regular LOC is charging 7% today without points but it changes daily. I'm happy with a one year interest only commitment as I don't think the rates will get to there that quickly. BTW, this is with Morgan Stanley.
Interesting strategy but I don't think that's one we'd be comfortable with. Thanks for sharing.
You are going to have an issue with it being a true log home. A lot of lenders don't want to touch those. Are you sure its a true log home and isn't just a stick built home with log siding and tongue and groove on the inside?
As for rate, it is an investment property so I don't know of anybody getting 6 or below on investment. But 6.5 should be doable. Maybe 6.25 even.
The sellers have listed it as a log home. I've been questioning whether it's truly a log home myself and do suspect it's actually log siding. Earlier this morning I sent a message to my CU's mortgage loan officer asking if they would cover log siding. The response was that he doesn't know and would have to look into it and get back to me on Monday!
Do you have access to a LOC in some way? I just got a 4.99% rate but it is a 3 year lock 30 year amortization or a 5.25% 1 year interest only. I'm likely taking the 1 year interest only and will refi then. My regular LOC is charging 7% today without points but it changes daily. I'm happy with a one year interest only commitment as I don't think the rates will get to there that quickly. BTW, this is with Morgan Stanley.
Interesting strategy but I don't think that's one we'd be comfortable with. Thanks for sharing.
Curious as to why you wouldn’t be comfortable with this? In my mind, the risk is interest rates going up which I’m not seeing that happen but of course I could be wrong. Back in the day, late 90’s my first purchase was a combo loan of an interest only ARM (interest rates were high then) at 80% LTV with a second loan loan for another 15% (I think this one was an ARM or fixed, don’t remember) and 5% cash down. This allowed me to remove mortgage insurance. I paid extra principal monthly regardless. Got me through the storm of very high interest rates (much different than today, I remember thinking 5.25% was a huge win!), built equity and refinanced when rates came down. After the 2006 crash, I don’t think you can get interesting options like this anymore but I credit this (along with not spending above what I could actually afford) getting me into real estate and building equity. Anyway, long story to better understand why you wouldn’t be comfortable with this.
Im repping a lot of buyers right now and I am seeing basically 6.5-7.5. Obviously all different types of programs. 6.375% sounded good but a shame they will not do log. I agree to not spend on points now if you can avoid it, you will probably be refinancing to lower rate anyways in 18-24 months. Good luck!
Do you have access to a LOC in some way? I just got a 4.99% rate but it is a 3 year lock 30 year amortization or a 5.25% 1 year interest only. I'm likely taking the 1 year interest only and will refi then. My regular LOC is charging 7% today without points but it changes daily. I'm happy with a one year interest only commitment as I don't think the rates will get to there that quickly. BTW, this is with Morgan Stanley.
Interesting strategy but I don't think that's one we'd be comfortable with. Thanks for sharing.
Curious as to why you wouldn’t be comfortable with this? In my mind, the risk is interest rates going up which I’m not seeing that happen but of course I could be wrong. Back in the day, late 90’s my first purchase was a combo loan of an interest only ARM (interest rates were high then) at 80% LTV with a second loan loan for another 15% (I think this one was an ARM or fixed, don’t remember) and 5% cash down. This allowed me to remove mortgage insurance. I paid extra principal monthly regardless. Got me through the storm of very high interest rates (much different than today, I remember thinking 5.25% was a huge win!), built equity and refinanced when rates came down. After the 2006 crash, I don’t think you can get interesting options like this anymore but I credit this (along with not spending above what I could actually afford) getting me into real estate and building equity. Anyway, long story to better understand why you wouldn’t be comfortable with this.
It all comes down to personal financial situations and tolerances for risk, debt, etc. I don't think this is the best option for us.
We have a winner! I called local banks and found 6.125% with reasonable closing costs. I was honestly dreading doing the calling, but am so glad I did.
I have to give a shout out to @Michael Baum because I honestly would have never thought to call local banks directly when trying to get a house from OOS.
WOOT! So glad you found something that would work. Frankly I never use a national lender for anything. Small credit unions and the like are my go to.
I would look at a nationwide lender like some of the folks on the board here for a project as well.
Gratz @Dina Schmid! Now get yer a$$ in gear and go buy the property!! :)
The forward treasury curve suggests that the Fed needs to decrease the fed funds rate 200-250 basis points from Sep-24 to Dec-25 for us treasury (and mortgage rates) to stay flat to where they are (i.e., us treasury (and mortgage rates) have already priced in future Fed expectations and mortgage rates will go up or down if the Fed cuts less or more than 200-250 basis points). The chart above would be better if it had the 10-year rather than 5-year treasury rate but the thesis is the same.
Do you have access to a LOC in some way? I just got a 4.99% rate but it is a 3 year lock 30 year amortization or a 5.25% 1 year interest only. I'm likely taking the 1 year interest only and will refi then. My regular LOC is charging 7% today without points but it changes daily. I'm happy with a one year interest only commitment as I don't think the rates will get to there that quickly. BTW, this is with Morgan Stanley.
is this loan secured by your primary residence as a HELOC or are you borrowing against your stock/bond portfolio ?
This one is borrowing against a stock portfolio but our Heloc just sent out a reduced rate also but still much higher than this.
I am under contract on an A-Frame to STR in Black Mountain, NC (if it survived the storm) and I couldn't use the DSCR for STR because they messed up 2023 after crushing 2022 on Airbnb.
I am at 30% down, 1.75 points, 6.875% with no prepayment penalties - $1,644/month. Purchase price is $410,000. Safe revenue when I am up and running full STR in the Spring is 50k, but I think I can do closer to 75k and up with a few tweaks.