New multifamily investor seeking advice
Member since 2025 · 22 posts · 12 votes
Hello everyone! My name is Randy Kinder and I am getting ready to purchase my first multi-family live-in property in or near Orange County, CA. So far I have been looking at San Clemente, beach cities, or university housing options (specifically UC Irvine or Chapman). I would like advice on where to go for analysis tools (calculators, spreadsheets) and am eager to learn from anyone’s general investing experience, especially specific experience you may have in the Orange County or Inland Empire housing markets. Thanks for taking the time to read this, and I am looking forward to getting more involved in this community!
Zillow has decent rental data—you can check what similar properties are renting for in your target area. Also check LoopNet and Crexi for multifamily listings.
Before committing to an agent, talk with several local ones to get a feel for the market. @Dan H. has strong experience in Southern California and might be a good resource.
Be cautious with listings: many agents post “market rents” or claim “upside potential” without sharing actual leases. Always ask for current rents and copies of leases—especially in small multifamily properties with mixed unit types (e.g., a studio, 2-bed, and 3-bed). Good underwriting starts with real numbers. Get inspections and sewer inspections.
Thanks for the call out.
I am in San Diego. It has similarities to OC but also differences.
RE investing is more challenging than it was a few years ago. I am in the camp the appreciation will be modest in the near term. I am also of the belief that high LTV MF with market rare financing will be cash negative. This implies that the investment should be viewed as a long term investment for it to achieve a good return.
2 recent national studies both showed that in virtually every large US city, it is initially cheaper to rent then to purchase. This is true for virtually all MF in OC purchased at high LTV using market rate financing.
If you plan to hold less than 10 years, you likely can do better in other more passive investments.
I am unsure what the OP knows about CA MF RE.
Are you aware of rent control? Do you understand some residences must get insurance from CA fair plan that is not fair for anyone? Do you understand the property tax readjusts at purchase? 1.2% is fairly safe for underwriting. Do you understand all the expenses and what should be expected? If you do not know what the 50% rule is, look into it. In San Diego a monthly rent to cost ratio of 0.7% for mls is fairly good, but will bleed cash at high LTV with market financing.
I am in negotiation on 6 units right now. It will be cash flow negative at purchase but likely is a better deal than 99.9% of the deals currently out there. This tells you what I think of the cash flow of the average RE investor purchase.
It is my view there are only a few paths in RE in my primary market (and most other RE markets) at this moment 1) patience. I am thinking years of patience. My market has historically out performed virtually all other markets. Over the long term I believe this will continue. Other markets have the same challenges as y market contrary to the posts from OOS agents. I am not that patient. 2) value adds. For the most part these require work and have risk but there are few markets that do better than my market via value adds. My last purchase is up over $1m above my costs in 3.5 years. 3) alternate rent models (rent by room, STR, MTR). These require work. Pay a pm and the profit is significantly reduced 4) alternative below market financing such as assumable, owner finance, wraps, sub to, etc 5) path of progress. Buy in areas that appreciation will far exceed the general market. It there a large major infrastructure development somewhere? In my market they recently completed a multi billion dollar Chula Vista bay front redevelopment. Already approved but early in the process are a large enhancement of a secondary airport (brown field) and the midway rising development which includes a new arena, retail, and residential development. With such large and costly development, these areas seem likely to out appreciate the general local RE market.
Do conservative underwriting. Recognize traditional rent ready LTR purchases with market financing it is likely a long term investment.
Good luck
@Dan H.
Thanks for taking the time to share from your extensive knowledge and experience. I also appreciate the "reality check" tone of your message, as it can be easy to get excited and overly optimistic about new opportunities like this.
I am new to CA MF RE, so I don't know a ton. I do know some of the things you were alluding to, and am generally aware that California loves to overregulate nearly everything which makes me more cautious than I otherwise would be.
I hear you loud and clear that high LTV MF with current market rate financing is currently expected to be a long game. I am hoping that a rate drop + refinance in the (hopefully near) future might occur and improve the picture - is that naive/unlikely? In any case, I am on board for the long / patient game.
Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE? That's another thing I have looked into recently, but the MF RE seemed like a better option assuming a hold period of > 10 years.
I did not know about the CA fair plan - that's good to be aware of and I will keep an eye on it.
Thanks for the advice you give at the end of the post concerning wise paths to take. I have added those to my notes and will keep them in mind. i didn't consider alternative below market financing - I will take a look at that.
Thanks again, and blessings to you.
>Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE?
I do not know about trust deeds.
However, let's go with my premise that when you first purchase it will be significant cash negative when including all expenses/revenue impacts (piti, cap ex/maintenance, PM (always include pm in underwriting even if self managing because your time has value and circumstances change), vacancy, bookkeeping, portion of asset protection (umbrella, LLC, etc, and miscellaneous (this includes things like unexpected utilities for example from a slab leak, not fair to charge the tenant (I recently had a $2k unexpected water fee for a water leak), legal fees for various consultations, eviction fee, or the recently mandated stair and balcony inspections, etc. it is a fairly small percent on a San Diego rent but would not be so small on a cheap Midwest rent). Add my expectation appreciation will be flattish for the near term. Since 2022, I have done my under writing with 0% appreciation for 5 years, then I use a little below historical market appreciation. The last 2 years this flattish has been quite accurate (2022 San Diego had ok appreciation so I was a year early in my flattish prediction). The implication is at 5 years you may have $0 return or even be negative. Then add in the selling costs to exit when you choose to exit (6% to 9% is common for San Diego if your not an RE agent). You can see why I am stating to expect at least a 10 year hold (any shorter, unless you use another besides patience of the list I provided, you are unlikely to achieve a return that justifies the effort.
By 10 years I expect the investment likely will look good. The leverage magnifies the appreciation. you also get equity pay down. Maybe by year 5 you have real cash flow (meaning enough to cover sustained maintenance/ cap ex) and all other expenses). will it look good compared to Mag7? S&P 500? Note those are more passive investments than residential RE. Residential RE should whoop passive investment options to be worth the effort. Whooping the other option’s expectations likely requires more than patience; it will require one or more of the other options I listed for good RE return.
My recommendation is before you make a choice, read a book on passive investing options. If you go with a syndicator, choose one that track record of success predates GFC.
Good luck
@Randy Kinder have you tried the tools here on BP yet?
Zillow has decent rental data—you can check what similar properties are renting for in your target area. Also check LoopNet and Crexi for multifamily listings.
Before committing to an agent, talk with several local ones to get a feel for the market. @Dan H. has strong experience in Southern California and might be a good resource.
Be cautious with listings: many agents post “market rents” or claim “upside potential” without sharing actual leases. Always ask for current rents and copies of leases—especially in small multifamily properties with mixed unit types (e.g., a studio, 2-bed, and 3-bed). Good underwriting starts with real numbers. Get inspections and sewer inspections.
Thanks for the call out.
I am in San Diego. It has similarities to OC but also differences.
RE investing is more challenging than it was a few years ago. I am in the camp the appreciation will be modest in the near term. I am also of the belief that high LTV MF with market rare financing will be cash negative. This implies that the investment should be viewed as a long term investment for it to achieve a good return.
2 recent national studies both showed that in virtually every large US city, it is initially cheaper to rent then to purchase. This is true for virtually all MF in OC purchased at high LTV using market rate financing.
If you plan to hold less than 10 years, you likely can do better in other more passive investments.
I am unsure what the OP knows about CA MF RE.
Are you aware of rent control? Do you understand some residences must get insurance from CA fair plan that is not fair for anyone? Do you understand the property tax readjusts at purchase? 1.2% is fairly safe for underwriting. Do you understand all the expenses and what should be expected? If you do not know what the 50% rule is, look into it. In San Diego a monthly rent to cost ratio of 0.7% for mls is fairly good, but will bleed cash at high LTV with market financing.
I am in negotiation on 6 units right now. It will be cash flow negative at purchase but likely is a better deal than 99.9% of the deals currently out there. This tells you what I think of the cash flow of the average RE investor purchase.
It is my view there are only a few paths in RE in my primary market (and most other RE markets) at this moment 1) patience. I am thinking years of patience. My market has historically out performed virtually all other markets. Over the long term I believe this will continue. Other markets have the same challenges as y market contrary to the posts from OOS agents. I am not that patient. 2) value adds. For the most part these require work and have risk but there are few markets that do better than my market via value adds. My last purchase is up over $1m above my costs in 3.5 years. 3) alternate rent models (rent by room, STR, MTR). These require work. Pay a pm and the profit is significantly reduced 4) alternative below market financing such as assumable, owner finance, wraps, sub to, etc 5) path of progress. Buy in areas that appreciation will far exceed the general market. It there a large major infrastructure development somewhere? In my market they recently completed a multi billion dollar Chula Vista bay front redevelopment. Already approved but early in the process are a large enhancement of a secondary airport (brown field) and the midway rising development which includes a new arena, retail, and residential development. With such large and costly development, these areas seem likely to out appreciate the general local RE market.
Do conservative underwriting. Recognize traditional rent ready LTR purchases with market financing it is likely a long term investment.
Good luck
@Dan H.
Thanks for taking the time to share from your extensive knowledge and experience. I also appreciate the "reality check" tone of your message, as it can be easy to get excited and overly optimistic about new opportunities like this.
I am new to CA MF RE, so I don't know a ton. I do know some of the things you were alluding to, and am generally aware that California loves to overregulate nearly everything which makes me more cautious than I otherwise would be.
I hear you loud and clear that high LTV MF with current market rate financing is currently expected to be a long game. I am hoping that a rate drop + refinance in the (hopefully near) future might occur and improve the picture - is that naive/unlikely? In any case, I am on board for the long / patient game.
Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE? That's another thing I have looked into recently, but the MF RE seemed like a better option assuming a hold period of > 10 years.
I did not know about the CA fair plan - that's good to be aware of and I will keep an eye on it.
Thanks for the advice you give at the end of the post concerning wise paths to take. I have added those to my notes and will keep them in mind. i didn't consider alternative below market financing - I will take a look at that.
Thanks again, and blessings to you.
>Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE?
I do not know about trust deeds.
However, let's go with my premise that when you first purchase it will be significant cash negative when including all expenses/revenue impacts (piti, cap ex/maintenance, PM (always include pm in underwriting even if self managing because your time has value and circumstances change), vacancy, bookkeeping, portion of asset protection (umbrella, LLC, etc, and miscellaneous (this includes things like unexpected utilities for example from a slab leak, not fair to charge the tenant (I recently had a $2k unexpected water fee for a water leak), legal fees for various consultations, eviction fee, or the recently mandated stair and balcony inspections, etc. it is a fairly small percent on a San Diego rent but would not be so small on a cheap Midwest rent). Add my expectation appreciation will be flattish for the near term. Since 2022, I have done my under writing with 0% appreciation for 5 years, then I use a little below historical market appreciation. The last 2 years this flattish has been quite accurate (2022 San Diego had ok appreciation so I was a year early in my flattish prediction). The implication is at 5 years you may have $0 return or even be negative. Then add in the selling costs to exit when you choose to exit (6% to 9% is common for San Diego if your not an RE agent). You can see why I am stating to expect at least a 10 year hold (any shorter, unless you use another besides patience of the list I provided, you are unlikely to achieve a return that justifies the effort.
By 10 years I expect the investment likely will look good. The leverage magnifies the appreciation. you also get equity pay down. Maybe by year 5 you have real cash flow (meaning enough to cover sustained maintenance/ cap ex) and all other expenses). will it look good compared to Mag7? S&P 500? Note those are more passive investments than residential RE. Residential RE should whoop passive investment options to be worth the effort. Whooping the other option’s expectations likely requires more than patience; it will require one or more of the other options I listed for good RE return.
My recommendation is before you make a choice, read a book on passive investing options. If you go with a syndicator, choose one that track record of success predates GFC.
Good luck
You’ve provided a really good list of items to underwrite, thanks for that! I have included some of these items already but not others, so I will add them to the underwriting calc. I had set the PM value to 0% assuming I would do all the work, but as you say circumstances change so I should probably set that to around 4-5% of monthly rent value, to represent a shared labor with PM.
Your most impactful advice is to assume 0% appreciation for first 5 years. I punched this into my calculator and it leads to very low ROI that wouldn't be worth pursuing unless owned longer. I was told by a prospective lender to assume 6% appreciation and 5% seller fee for my model - these numbers are far more optimistic than yours, perhaps misleading as you say.
I agree that residential RE should whoop passive investing to be worth it, especially since I have a full time job as an engineer so time is precious.
I will tune up the underwriting calculation with the categories and values you’ve mentioned, and look more into passive investing options, and compare the 2 to come to a decision.
Thanks again for taking the time to provide advice to someone like me who is learning the ropes, I appreciate it.
@Randy Kinder your local and in luck. Check out this meet-up tonight where you can get all your questions answered by experts in their fields.
OCREIN - Learn How to Use PropstreamOCREIN - Learn How to Use Propstream
Good Investing...
@Randy Kinder your local and in luck. Check out this meet-up tonight where you can get all your questions answered by experts in their fields.
OCREIN - Learn How to Use PropstreamOCREIN - Learn How to Use Propstream
Good Investing...
@Joe Homs Thanks for the invitation! Bummer, I live in Irvine so would have loved to come but had plans this evening. When will the next one occur?
@Joe Homs Awesome thanks Joe, I just signed up for it.
@Quinton Brown Thanks for the suggestion! I just took a look at them. I am going to activate the 7-day Pro Membership trial in a couple of days and check them out.
@Bradley Buxton Thanks for the solid advice! I will be sure to check out the resources you recommended for setting rent, MF listings, and the agent you recommended. As a R&D engineer, I am a hard numbers guy for sure so won't settle for vaguely worded assurances. I have added these items to my checklist/ to-do list. Blessings to you
Hey Randy,
I get it, Orange County is pricey and tough for cash flow. If you’re open to out-of-state options, the Midwest has great opportunities in B and C grade neighborhoods, with lower entry costs, solid rental income, and room for appreciation. You can find undervalued multi-family properties that let you rehab, rent, and scale faster while keeping costs manageable.
@Arman Ahmed thanks for reaching out and providing this suggestion! I am not opposed to considering out of state options, especially if they present good deals. However, in that case I would like things to be pretty hands-off since I work full time and have a vibrant community life in Southern California. Do you see such hands-off kinds of opportunities there? If so, I would be interested.
I'd recommend starting with the BiggerPockets rental calculator just to get comfortable with the assumptions. Once you're serious about a deal, build a simple spreadsheet and plug in your real estimates for repairs, vacancy, insurance, utilities, and rent comps. A lot of new investors underestimate CapEx and vacancy, especially in high-end markets, so it helps to be conservative.

I'd recommend starting with the BiggerPockets rental calculator just to get comfortable with the assumptions. Once you're serious about a deal, build a simple spreadsheet and plug in your real estimates for repairs, vacancy, insurance, utilities, and rent comps. A lot of new investors underestimate CapEx and vacancy, especially in high-end markets, so it helps to be conservative.
@Kerlous Tadres Thanks a lot for your advice. I plan on activating the 7-day BP Pro trial tomorrow and checking out as many of the calculators and Pro resources I can over the next week, so I will check out the rental one you mention and get a feel for assumptions and common values used. My current calculator acknowledges the values you've mentioned, but I have been warned about being too optimistic regarding Capex, property management, and especially appreciation, and now you mention vacancy so i will also keep my eye on that. Thanks again for taking the time to provide advice, I really appreciate it.
Zillow has decent rental data—you can check what similar properties are renting for in your target area. Also check LoopNet and Crexi for multifamily listings.
Before committing to an agent, talk with several local ones to get a feel for the market. @Dan H. has strong experience in Southern California and might be a good resource.
Be cautious with listings: many agents post “market rents” or claim “upside potential” without sharing actual leases. Always ask for current rents and copies of leases—especially in small multifamily properties with mixed unit types (e.g., a studio, 2-bed, and 3-bed). Good underwriting starts with real numbers. Get inspections and sewer inspections.
Thanks for the call out.
I am in San Diego. It has similarities to OC but also differences.
RE investing is more challenging than it was a few years ago. I am in the camp the appreciation will be modest in the near term. I am also of the belief that high LTV MF with market rare financing will be cash negative. This implies that the investment should be viewed as a long term investment for it to achieve a good return.
2 recent national studies both showed that in virtually every large US city, it is initially cheaper to rent then to purchase. This is true for virtually all MF in OC purchased at high LTV using market rate financing.
If you plan to hold less than 10 years, you likely can do better in other more passive investments.
I am unsure what the OP knows about CA MF RE.
Are you aware of rent control? Do you understand some residences must get insurance from CA fair plan that is not fair for anyone? Do you understand the property tax readjusts at purchase? 1.2% is fairly safe for underwriting. Do you understand all the expenses and what should be expected? If you do not know what the 50% rule is, look into it. In San Diego a monthly rent to cost ratio of 0.7% for mls is fairly good, but will bleed cash at high LTV with market financing.
I am in negotiation on 6 units right now. It will be cash flow negative at purchase but likely is a better deal than 99.9% of the deals currently out there. This tells you what I think of the cash flow of the average RE investor purchase.
It is my view there are only a few paths in RE in my primary market (and most other RE markets) at this moment 1) patience. I am thinking years of patience. My market has historically out performed virtually all other markets. Over the long term I believe this will continue. Other markets have the same challenges as y market contrary to the posts from OOS agents. I am not that patient. 2) value adds. For the most part these require work and have risk but there are few markets that do better than my market via value adds. My last purchase is up over $1m above my costs in 3.5 years. 3) alternate rent models (rent by room, STR, MTR). These require work. Pay a pm and the profit is significantly reduced 4) alternative below market financing such as assumable, owner finance, wraps, sub to, etc 5) path of progress. Buy in areas that appreciation will far exceed the general market. It there a large major infrastructure development somewhere? In my market they recently completed a multi billion dollar Chula Vista bay front redevelopment. Already approved but early in the process are a large enhancement of a secondary airport (brown field) and the midway rising development which includes a new arena, retail, and residential development. With such large and costly development, these areas seem likely to out appreciate the general local RE market.
Do conservative underwriting. Recognize traditional rent ready LTR purchases with market financing it is likely a long term investment.
Good luck
@Dan H.
Thanks for taking the time to share from your extensive knowledge and experience. I also appreciate the "reality check" tone of your message, as it can be easy to get excited and overly optimistic about new opportunities like this.
I am new to CA MF RE, so I don't know a ton. I do know some of the things you were alluding to, and am generally aware that California loves to overregulate nearly everything which makes me more cautious than I otherwise would be.
I hear you loud and clear that high LTV MF with current market rate financing is currently expected to be a long game. I am hoping that a rate drop + refinance in the (hopefully near) future might occur and improve the picture - is that naive/unlikely? In any case, I am on board for the long / patient game.
Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE? That's another thing I have looked into recently, but the MF RE seemed like a better option assuming a hold period of > 10 years.
I did not know about the CA fair plan - that's good to be aware of and I will keep an eye on it.
Thanks for the advice you give at the end of the post concerning wise paths to take. I have added those to my notes and will keep them in mind. i didn't consider alternative below market financing - I will take a look at that.
Thanks again, and blessings to you.
>Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE?
I do not know about trust deeds.
However, let's go with my premise that when you first purchase it will be significant cash negative when including all expenses/revenue impacts (piti, cap ex/maintenance, PM (always include pm in underwriting even if self managing because your time has value and circumstances change), vacancy, bookkeeping, portion of asset protection (umbrella, LLC, etc, and miscellaneous (this includes things like unexpected utilities for example from a slab leak, not fair to charge the tenant (I recently had a $2k unexpected water fee for a water leak), legal fees for various consultations, eviction fee, or the recently mandated stair and balcony inspections, etc. it is a fairly small percent on a San Diego rent but would not be so small on a cheap Midwest rent). Add my expectation appreciation will be flattish for the near term. Since 2022, I have done my under writing with 0% appreciation for 5 years, then I use a little below historical market appreciation. The last 2 years this flattish has been quite accurate (2022 San Diego had ok appreciation so I was a year early in my flattish prediction). The implication is at 5 years you may have $0 return or even be negative. Then add in the selling costs to exit when you choose to exit (6% to 9% is common for San Diego if your not an RE agent). You can see why I am stating to expect at least a 10 year hold (any shorter, unless you use another besides patience of the list I provided, you are unlikely to achieve a return that justifies the effort.
By 10 years I expect the investment likely will look good. The leverage magnifies the appreciation. you also get equity pay down. Maybe by year 5 you have real cash flow (meaning enough to cover sustained maintenance/ cap ex) and all other expenses). will it look good compared to Mag7? S&P 500? Note those are more passive investments than residential RE. Residential RE should whoop passive investment options to be worth the effort. Whooping the other option’s expectations likely requires more than patience; it will require one or more of the other options I listed for good RE return.
My recommendation is before you make a choice, read a book on passive investing options. If you go with a syndicator, choose one that track record of success predates GFC.
Good luck
You’ve provided a really good list of items to underwrite, thanks for that! I have included some of these items already but not others, so I will add them to the underwriting calc. I had set the PM value to 0% assuming I would do all the work, but as you say circumstances change so I should probably set that to around 4-5% of monthly rent value, to represent a shared labor with PM.
Your most impactful advice is to assume 0% appreciation for first 5 years. I punched this into my calculator and it leads to very low ROI that wouldn't be worth pursuing unless owned longer. I was told by a prospective lender to assume 6% appreciation and 5% seller fee for my model - these numbers are far more optimistic than yours, perhaps misleading as you say.
I agree that residential RE should whoop passive investing to be worth it, especially since I have a full time job as an engineer so time is precious.
I will tune up the underwriting calculation with the categories and values you’ve mentioned, and look more into passive investing options, and compare the 2 to come to a decision.
Thanks again for taking the time to provide advice to someone like me who is learning the ropes, I appreciate it.
Orange County is a large area. I used orange as the appreciation look up. For this century orange’ appreciation is 5.46%/year per neighborhoodscout. I want my underwriting to be conservative and would likely use no higher than 5% after the 5 years at zero forecasted appreciation.
5% could cover the realtor (in San Diego sellers are still paying buyers realtor at a large percentage - enough that my realtors state that the lawsuit mostly has only resulted in process changes) without any necessary work or closing costs. It is 1% to 4% low for the normal range in San Diego. In addition, when the market is slow buyers may want seller to pay some points to buying the loan down.
The RE agent wants you to purchase; more, they are compensated only if you buy. In addition, many are not investors. They are often clueless to holding costs. I told a realtor that was selling a house with 0.5% rent ratio who indicated 50% expense/income impact was too high that the property tax was 20% by itself. He told me it was not that high as there there is not a known answer to this. I did the math for him. He was enlightened, but it means he had little idea to holding costs. Needless to say, a 0.5% rent ratio is huge cash negative at high LTV. It would require a good/outstanding value add or great financing to be a good investment. His property was a poor investment, but it was his job to convince a buyer (sucker?) that it was a good investment. Unfortunately in the current RE market, most investment properties for sale are poor investments.
good luck
Thanks for digging up that information. I can see where the RE agent estimated 6% appreciation, which is somewhat close to that but overly optimistic. I am trying to understand why it would be beneficial to be so conservative in the calculation - is it because underperformance is too practically risky? If I wanted to predict average, not conservative, performance going into the future, should I use 5.46% appreciation every year including the first 5 years?
Like you mention, I have gotten a taste of the real estate agents wanting to sell the most expensive properties - that is the built-in bias to their trade. Also, some that I have come across are really not numbers-oriented people like me, and I am getting the impression that that isn’t too uncommon.
I’d like your take on something if you are open to helping me understand it: why do I see many RE folks approaching deals from only one angle (i.e. cash flow or appreciation or amortization or value add or tax appreciation) rather than aggregating all 5 categories together into an accurate model to sum up the financial gain of a RE investment. Is it just because it is easier to consider only 1 metric at a time? They all contribute to the financial gain so it seems they should all be considered simultaneously to provide an accurate picture. What do you think?
Some others consider my underwriting conservative, I consider it fairly accurate but hopefully a bit conservative. I really believe the most likely scenario for the near term is flattish. If you do not see any reasons the current period is unlikely to match the average for this century, then use the average for this century.
@Dave Meyer recently had a post where he covered his opinion on the various near term appreciation possibilities. I recommend the read if you have not read it. Also Dave is a numbers guy (like you? And me). I have not spent the effort to try to place accurate percentages on my own thoughts but I agree with his primary premise that virtually anything can happen but some things are more likely to happen than others and I believe (and he believes) the most likely to happen is flattish and I have held this view since the start of 2022. So 5 years of 0% appreciation is what I believe and what I have used in my underwriting for almost 4 years.
I believe a lot of people in this forum most value cash flow. And if you need cash flow to pay the bills, then you need cash flow. If you are not in a situation where the cash flow is necessary you should look at total return. However, I go the opposite extreme on the cash flow. I actively minimize cash flow because it is taxed in the year earned (I try to legally minimize my taxes). Because I believe in leverage, that is the historically typical how I deal with it but with my rates being near 3% and current rates being over 6% I have been using other means like accelerated depreciation or increased maintenance/cap ex. In addition, my market, like OC, is never going to have great cash flow for the equity. The return is typically achieved via the appreciation. My lowest appreciating RE has appreciated ~$2700/ month over its hold. I have 2 (maybe 3) that have appreciated over $10k/month over their hold. I, therefore, very much agree that the return should be by total return. I will add though that even though I do not view cash flow as certain, I do think it is more sure than relying on rent growth or appreciation especially in the short term (Long term rent growth and appreciation is a virtual certainty but maybe not at historical levels). Which also brings me to why I use less than the historical appreciation rate for this century in my underwriting. I believe 2000 to 2006 and 2011 to 2023 were incredible years for RE. Because so many years of this century has been so outstanding, I do not expect the next 25 years will do as well as the last 25 years. I did my last underwriting 5 years 0%, then 4.5% even though my market’s historical appreciation for this century approaches 6%. I believe my 4.5% is likely closer to realty than the historical 5.75%. I could be wrong, but I could be wrong in either direction.
I highly recommend you do not underwrite using 6% appreciation.
I do believe you are on the right track. One more piece of advice. Small unit count sustained maintenance/cap ex is much higher than most people use in their underwriting. If you can find someone’s spreadsheet that actually calculates this based on lifespans and costs for all items on a property, I think you will find it enlightening. On my last underwriting, I used $600/month on a single unit (which is a bit high for one unit but it was a luxury cabin in a remote Sierra location and I believe was fairly accurate).
Good luck
@Dan H.
Apologies for the late reply - I was tied up this weekend.
Interesting. I went to Dave’s page to try and look for that blog post but I couldn’t find it. In any case, it looks like you have research and experience-based reasons for the assumption of appreciation being flattish over the next several years, so I will use that too.
I am glad you brought up the topic of prioritization of cash flow vs total return. Cash flow is not absolutely necessary for me, and as you mentioned previously high LTV MF generating positive cash flow is hard to come by these days. Furthermore, it seems to me that the positive cash flow options are more competitive than high total return options (because more people want them). Also you mention the fact that the cash flow gets taxed in the year it is realized, making it undesirable from that POV. For these reasons, I agree with you that total return is the metric most significant in my case. I guess this would be represented by IRR right?
Yes your 0% for first 5 years, then 4.5% every year thereafter seems sensible to me.
I appreciate the warning about how often people undershoot the maintenance/capex values in their underwriting. Yes, I will try to find actual itemized breakdowns on which to base the estimates.
I am trying to solidify a practical action plan for buying an investment property and would be grateful for your feedback. First, I plan to establish a solid MF property underwriting model/calculator that I trust in (will build trust by vetting values and researching to ensure I have proper categories covered). Second, I plan on researching / asking this BP forum to find good general locations (with a bias towards SoCal since I would prefer a place that I live in). Third, I plan on contacting an investor-friendly RE agent in that area to look for deals, which I will plop into the modeler to evaluate the whether the IRR makes sense, and if it does I will buy. Does this sound like a good approach to you? Are there any resources or mentorship/educational programs you would recommend?
I really appreciate the advice you have given Dan. BTW how high is that rock you are jumping off in your profile pic?
As for the rock, I have heard everything from 35’ to 60’. There is about 10’ of variance based on lake fluctuation. My belief is that it is 40’ to 50’ depending on lake level, and was likely close to 50’ on that jump. I am 5’10” as reference. I have been going to that lake since I was 7 or 8 years old but waited until I was past 40 years old to do the jump. I have now done it a few times; once looking at the water with my face and had a face flop (did not feel great).
My crazy son has done a ~100’ jump and that is not his craziest jump. In this screenshot from the video, he has just started the jump (he is 6’3” for reference)
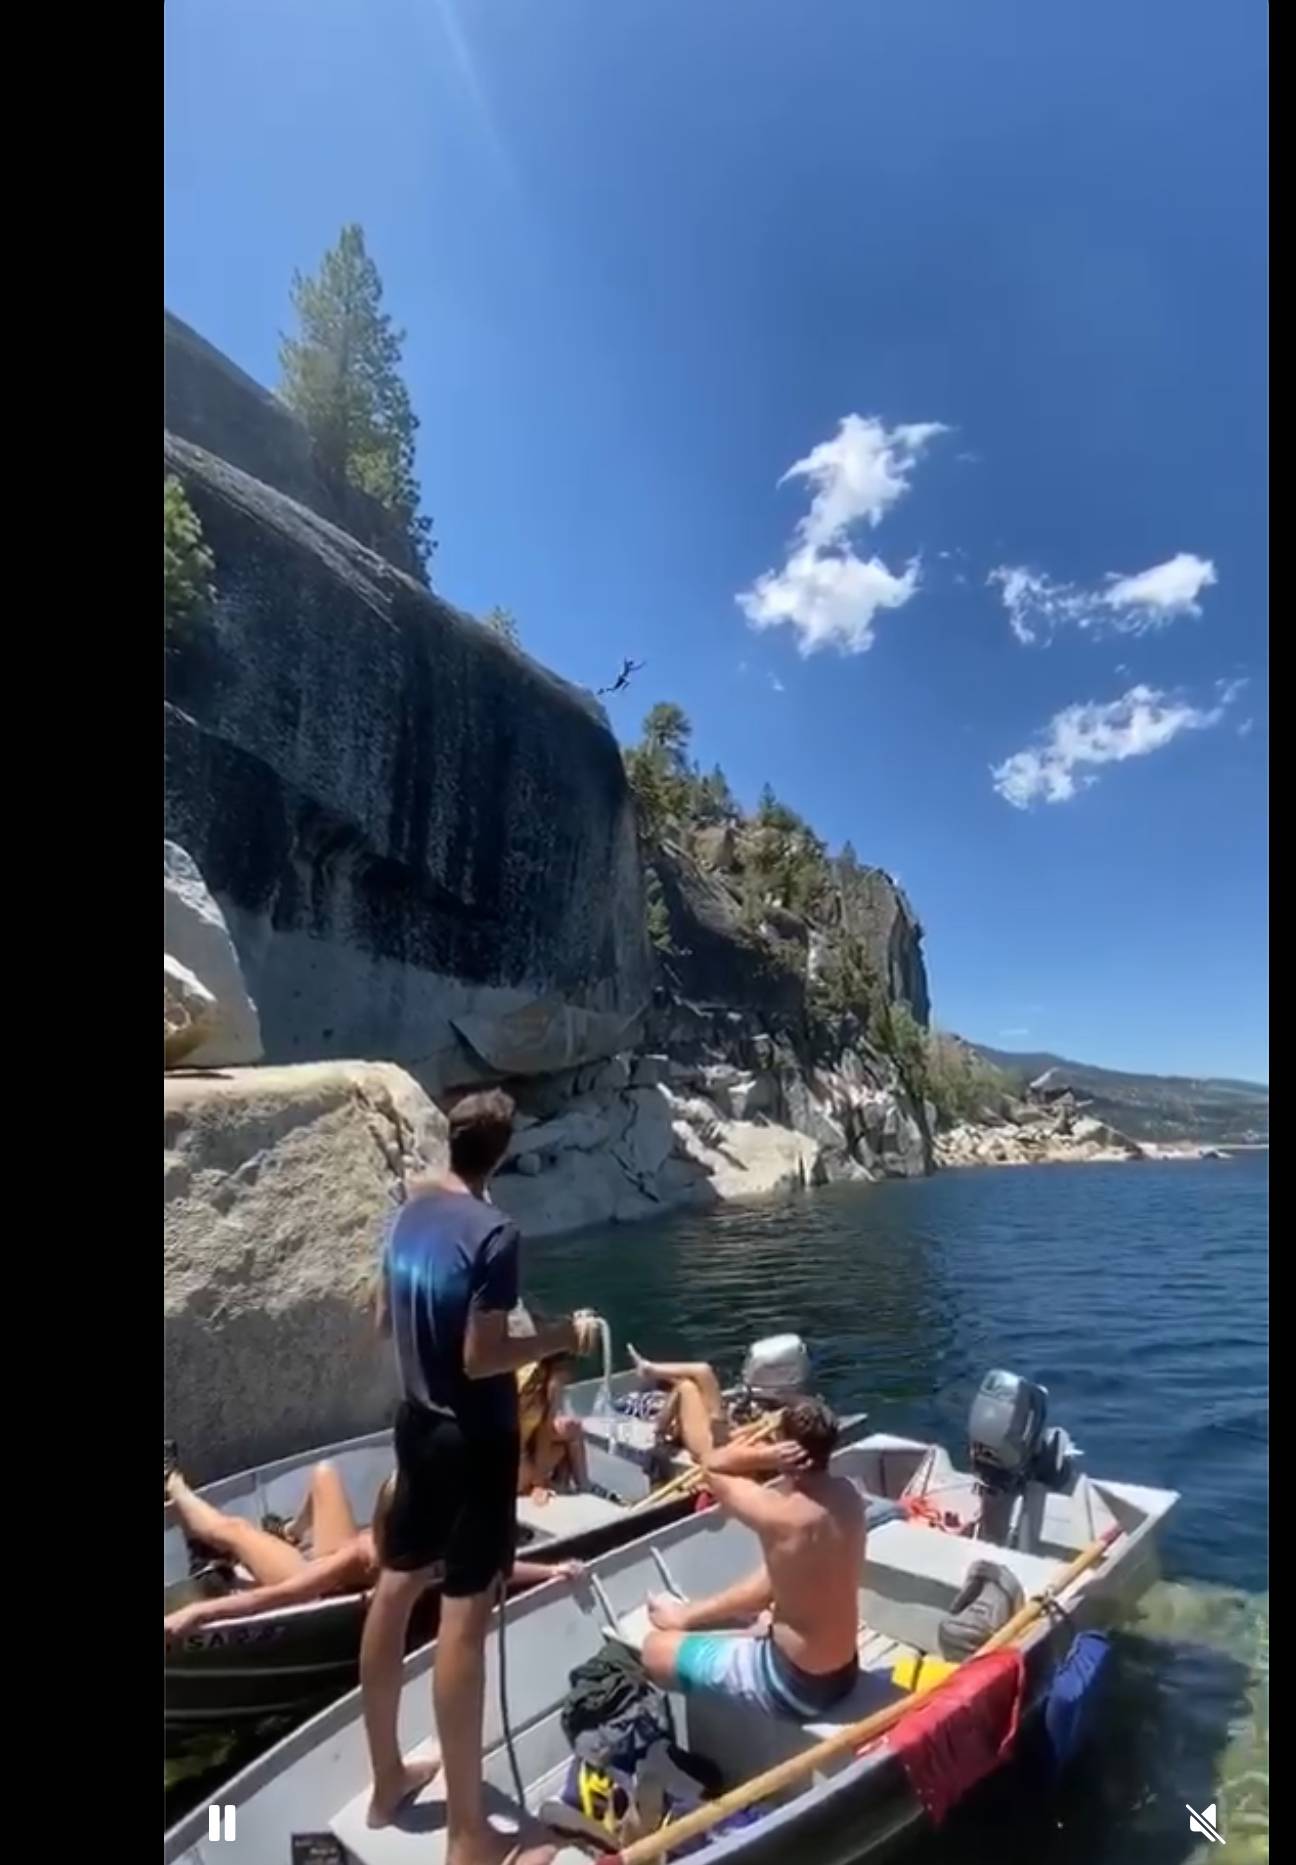
I think very little that is on the mls works as traditional LTR with current market financing and what does work often goes real fast. So I recommend you network and try to go off market. Realize off market often has risk or requires work. Rent ready stuff with zero risk usually does not have a need to sell off market. Some realtors have off market listings, but the best go to their preferred clients. Because off market is by definition not to every agent, do not commit to a duration based exclusive contract if you are interested in pursuing off market listings. Investor friendly agent should understand that you do not want to limit your sources of potential RE. Both agents I have used recently on offers understood this and the agreement was property specific.
I think IRR by itself is a bit simplistic as RE has tax savings, equity paydown (which can be included in IRR formula), leverage, and selling costs, but IRR does pretty good as it includes the cash flow and appreciation (or projected cash flow and projected appreciation). These "extras" adds complexity to the formula. It gets more complex if you can use REP or "STR loophole" (terrible name) to reduce w2 earnings. Combined with accelerated depreciation can make this complex. We qualify as REP. We could qualify via STR loophole but because we do not need it, our co-host exceeds our time spent (must be more time than anyone else). if we needed it we would pick up some items that we currently have co-host doing.
If I put $150k towards a purchase that saves me $50k in taxes (such as accelerated depreciation on $600k condo with virtually no land basis), is this the same as investing only $100k? I think it is close to the same as my net out of pocket for the year is $100k with the purchase of that property. But assuming I liquidate before I die without a 1031, that depreciation is recaptured. So with current rules, keep or 1031 until you die. Especially in CA with the advantages of prop 13. If the depreciation is never recaptured, it seems the same from my perspective.
the Dave Meyer appreciation forecast was actually a podcast. I remembered it was a blog because I read it and did not listen to it. You should be able to find it by internet searching ‘Dave Meyers BiggerPockets appreciation 2025”. To summarize in a single statement is virtually everything is possible with respect to residential appreciation, but the most likely is flattish.
good luck
Zillow has decent rental data—you can check what similar properties are renting for in your target area. Also check LoopNet and Crexi for multifamily listings.
Before committing to an agent, talk with several local ones to get a feel for the market. @Dan H. has strong experience in Southern California and might be a good resource.
Be cautious with listings: many agents post “market rents” or claim “upside potential” without sharing actual leases. Always ask for current rents and copies of leases—especially in small multifamily properties with mixed unit types (e.g., a studio, 2-bed, and 3-bed). Good underwriting starts with real numbers. Get inspections and sewer inspections.
Thanks for the call out.
I am in San Diego. It has similarities to OC but also differences.
RE investing is more challenging than it was a few years ago. I am in the camp the appreciation will be modest in the near term. I am also of the belief that high LTV MF with market rare financing will be cash negative. This implies that the investment should be viewed as a long term investment for it to achieve a good return.
2 recent national studies both showed that in virtually every large US city, it is initially cheaper to rent then to purchase. This is true for virtually all MF in OC purchased at high LTV using market rate financing.
If you plan to hold less than 10 years, you likely can do better in other more passive investments.
I am unsure what the OP knows about CA MF RE.
Are you aware of rent control? Do you understand some residences must get insurance from CA fair plan that is not fair for anyone? Do you understand the property tax readjusts at purchase? 1.2% is fairly safe for underwriting. Do you understand all the expenses and what should be expected? If you do not know what the 50% rule is, look into it. In San Diego a monthly rent to cost ratio of 0.7% for mls is fairly good, but will bleed cash at high LTV with market financing.
I am in negotiation on 6 units right now. It will be cash flow negative at purchase but likely is a better deal than 99.9% of the deals currently out there. This tells you what I think of the cash flow of the average RE investor purchase.
It is my view there are only a few paths in RE in my primary market (and most other RE markets) at this moment 1) patience. I am thinking years of patience. My market has historically out performed virtually all other markets. Over the long term I believe this will continue. Other markets have the same challenges as y market contrary to the posts from OOS agents. I am not that patient. 2) value adds. For the most part these require work and have risk but there are few markets that do better than my market via value adds. My last purchase is up over $1m above my costs in 3.5 years. 3) alternate rent models (rent by room, STR, MTR). These require work. Pay a pm and the profit is significantly reduced 4) alternative below market financing such as assumable, owner finance, wraps, sub to, etc 5) path of progress. Buy in areas that appreciation will far exceed the general market. It there a large major infrastructure development somewhere? In my market they recently completed a multi billion dollar Chula Vista bay front redevelopment. Already approved but early in the process are a large enhancement of a secondary airport (brown field) and the midway rising development which includes a new arena, retail, and residential development. With such large and costly development, these areas seem likely to out appreciate the general local RE market.
Do conservative underwriting. Recognize traditional rent ready LTR purchases with market financing it is likely a long term investment.
Good luck
@Dan H.
Thanks for taking the time to share from your extensive knowledge and experience. I also appreciate the "reality check" tone of your message, as it can be easy to get excited and overly optimistic about new opportunities like this.
I am new to CA MF RE, so I don't know a ton. I do know some of the things you were alluding to, and am generally aware that California loves to overregulate nearly everything which makes me more cautious than I otherwise would be.
I hear you loud and clear that high LTV MF with current market rate financing is currently expected to be a long game. I am hoping that a rate drop + refinance in the (hopefully near) future might occur and improve the picture - is that naive/unlikely? In any case, I am on board for the long / patient game.
Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE? That's another thing I have looked into recently, but the MF RE seemed like a better option assuming a hold period of > 10 years.
I did not know about the CA fair plan - that's good to be aware of and I will keep an eye on it.
Thanks for the advice you give at the end of the post concerning wise paths to take. I have added those to my notes and will keep them in mind. i didn't consider alternative below market financing - I will take a look at that.
Thanks again, and blessings to you.
>Speaking of more passive investments, what's your take on trust deed investing compared to Orange County MF RE?
I do not know about trust deeds.
However, let's go with my premise that when you first purchase it will be significant cash negative when including all expenses/revenue impacts (piti, cap ex/maintenance, PM (always include pm in underwriting even if self managing because your time has value and circumstances change), vacancy, bookkeeping, portion of asset protection (umbrella, LLC, etc, and miscellaneous (this includes things like unexpected utilities for example from a slab leak, not fair to charge the tenant (I recently had a $2k unexpected water fee for a water leak), legal fees for various consultations, eviction fee, or the recently mandated stair and balcony inspections, etc. it is a fairly small percent on a San Diego rent but would not be so small on a cheap Midwest rent). Add my expectation appreciation will be flattish for the near term. Since 2022, I have done my under writing with 0% appreciation for 5 years, then I use a little below historical market appreciation. The last 2 years this flattish has been quite accurate (2022 San Diego had ok appreciation so I was a year early in my flattish prediction). The implication is at 5 years you may have $0 return or even be negative. Then add in the selling costs to exit when you choose to exit (6% to 9% is common for San Diego if your not an RE agent). You can see why I am stating to expect at least a 10 year hold (any shorter, unless you use another besides patience of the list I provided, you are unlikely to achieve a return that justifies the effort.
By 10 years I expect the investment likely will look good. The leverage magnifies the appreciation. you also get equity pay down. Maybe by year 5 you have real cash flow (meaning enough to cover sustained maintenance/ cap ex) and all other expenses). will it look good compared to Mag7? S&P 500? Note those are more passive investments than residential RE. Residential RE should whoop passive investment options to be worth the effort. Whooping the other option’s expectations likely requires more than patience; it will require one or more of the other options I listed for good RE return.
My recommendation is before you make a choice, read a book on passive investing options. If you go with a syndicator, choose one that track record of success predates GFC.
Good luck
You’ve provided a really good list of items to underwrite, thanks for that! I have included some of these items already but not others, so I will add them to the underwriting calc. I had set the PM value to 0% assuming I would do all the work, but as you say circumstances change so I should probably set that to around 4-5% of monthly rent value, to represent a shared labor with PM.
Your most impactful advice is to assume 0% appreciation for first 5 years. I punched this into my calculator and it leads to very low ROI that wouldn't be worth pursuing unless owned longer. I was told by a prospective lender to assume 6% appreciation and 5% seller fee for my model - these numbers are far more optimistic than yours, perhaps misleading as you say.
I agree that residential RE should whoop passive investing to be worth it, especially since I have a full time job as an engineer so time is precious.
I will tune up the underwriting calculation with the categories and values you’ve mentioned, and look more into passive investing options, and compare the 2 to come to a decision.
Thanks again for taking the time to provide advice to someone like me who is learning the ropes, I appreciate it.
Orange County is a large area. I used orange as the appreciation look up. For this century orange’ appreciation is 5.46%/year per neighborhoodscout. I want my underwriting to be conservative and would likely use no higher than 5% after the 5 years at zero forecasted appreciation.
5% could cover the realtor (in San Diego sellers are still paying buyers realtor at a large percentage - enough that my realtors state that the lawsuit mostly has only resulted in process changes) without any necessary work or closing costs. It is 1% to 4% low for the normal range in San Diego. In addition, when the market is slow buyers may want seller to pay some points to buying the loan down.
The RE agent wants you to purchase; more, they are compensated only if you buy. In addition, many are not investors. They are often clueless to holding costs. I told a realtor that was selling a house with 0.5% rent ratio who indicated 50% expense/income impact was too high that the property tax was 20% by itself. He told me it was not that high as there there is not a known answer to this. I did the math for him. He was enlightened, but it means he had little idea to holding costs. Needless to say, a 0.5% rent ratio is huge cash negative at high LTV. It would require a good/outstanding value add or great financing to be a good investment. His property was a poor investment, but it was his job to convince a buyer (sucker?) that it was a good investment. Unfortunately in the current RE market, most investment properties for sale are poor investments.
good luck
Thanks for digging up that information. I can see where the RE agent estimated 6% appreciation, which is somewhat close to that but overly optimistic. I am trying to understand why it would be beneficial to be so conservative in the calculation - is it because underperformance is too practically risky? If I wanted to predict average, not conservative, performance going into the future, should I use 5.46% appreciation every year including the first 5 years?
Like you mention, I have gotten a taste of the real estate agents wanting to sell the most expensive properties - that is the built-in bias to their trade. Also, some that I have come across are really not numbers-oriented people like me, and I am getting the impression that that isn’t too uncommon.
I’d like your take on something if you are open to helping me understand it: why do I see many RE folks approaching deals from only one angle (i.e. cash flow or appreciation or amortization or value add or tax appreciation) rather than aggregating all 5 categories together into an accurate model to sum up the financial gain of a RE investment. Is it just because it is easier to consider only 1 metric at a time? They all contribute to the financial gain so it seems they should all be considered simultaneously to provide an accurate picture. What do you think?
Some others consider my underwriting conservative, I consider it fairly accurate but hopefully a bit conservative. I really believe the most likely scenario for the near term is flattish. If you do not see any reasons the current period is unlikely to match the average for this century, then use the average for this century.
@Dave Meyer recently had a post where he covered his opinion on the various near term appreciation possibilities. I recommend the read if you have not read it. Also Dave is a numbers guy (like you? And me). I have not spent the effort to try to place accurate percentages on my own thoughts but I agree with his primary premise that virtually anything can happen but some things are more likely to happen than others and I believe (and he believes) the most likely to happen is flattish and I have held this view since the start of 2022. So 5 years of 0% appreciation is what I believe and what I have used in my underwriting for almost 4 years.
I believe a lot of people in this forum most value cash flow. And if you need cash flow to pay the bills, then you need cash flow. If you are not in a situation where the cash flow is necessary you should look at total return. However, I go the opposite extreme on the cash flow. I actively minimize cash flow because it is taxed in the year earned (I try to legally minimize my taxes). Because I believe in leverage, that is the historically typical how I deal with it but with my rates being near 3% and current rates being over 6% I have been using other means like accelerated depreciation or increased maintenance/cap ex. In addition, my market, like OC, is never going to have great cash flow for the equity. The return is typically achieved via the appreciation. My lowest appreciating RE has appreciated ~$2700/ month over its hold. I have 2 (maybe 3) that have appreciated over $10k/month over their hold. I, therefore, very much agree that the return should be by total return. I will add though that even though I do not view cash flow as certain, I do think it is more sure than relying on rent growth or appreciation especially in the short term (Long term rent growth and appreciation is a virtual certainty but maybe not at historical levels). Which also brings me to why I use less than the historical appreciation rate for this century in my underwriting. I believe 2000 to 2006 and 2011 to 2023 were incredible years for RE. Because so many years of this century has been so outstanding, I do not expect the next 25 years will do as well as the last 25 years. I did my last underwriting 5 years 0%, then 4.5% even though my market’s historical appreciation for this century approaches 6%. I believe my 4.5% is likely closer to realty than the historical 5.75%. I could be wrong, but I could be wrong in either direction.
I highly recommend you do not underwrite using 6% appreciation.
I do believe you are on the right track. One more piece of advice. Small unit count sustained maintenance/cap ex is much higher than most people use in their underwriting. If you can find someone’s spreadsheet that actually calculates this based on lifespans and costs for all items on a property, I think you will find it enlightening. On my last underwriting, I used $600/month on a single unit (which is a bit high for one unit but it was a luxury cabin in a remote Sierra location and I believe was fairly accurate).
Good luck
@Dan H.
Apologies for the late reply - I was tied up this weekend.
Interesting. I went to Dave’s page to try and look for that blog post but I couldn’t find it. In any case, it looks like you have research and experience-based reasons for the assumption of appreciation being flattish over the next several years, so I will use that too.
I am glad you brought up the topic of prioritization of cash flow vs total return. Cash flow is not absolutely necessary for me, and as you mentioned previously high LTV MF generating positive cash flow is hard to come by these days. Furthermore, it seems to me that the positive cash flow options are more competitive than high total return options (because more people want them). Also you mention the fact that the cash flow gets taxed in the year it is realized, making it undesirable from that POV. For these reasons, I agree with you that total return is the metric most significant in my case. I guess this would be represented by IRR right?
Yes your 0% for first 5 years, then 4.5% every year thereafter seems sensible to me.
I appreciate the warning about how often people undershoot the maintenance/capex values in their underwriting. Yes, I will try to find actual itemized breakdowns on which to base the estimates.
I am trying to solidify a practical action plan for buying an investment property and would be grateful for your feedback. First, I plan to establish a solid MF property underwriting model/calculator that I trust in (will build trust by vetting values and researching to ensure I have proper categories covered). Second, I plan on researching / asking this BP forum to find good general locations (with a bias towards SoCal since I would prefer a place that I live in). Third, I plan on contacting an investor-friendly RE agent in that area to look for deals, which I will plop into the modeler to evaluate the whether the IRR makes sense, and if it does I will buy. Does this sound like a good approach to you? Are there any resources or mentorship/educational programs you would recommend?
I really appreciate the advice you have given Dan. BTW how high is that rock you are jumping off in your profile pic?
As for the rock, I have heard everything from 35’ to 60’. There is about 10’ of variance based on lake fluctuation. My belief is that it is 40’ to 50’ depending on lake level, and was likely close to 50’ on that jump. I am 5’10” as reference. I have been going to that lake since I was 7 or 8 years old but waited until I was past 40 years old to do the jump. I have now done it a few times; once looking at the water with my face and had a face flop (did not feel great).
My crazy son has done a ~100’ jump and that is not his craziest jump. In this screenshot from the video, he has just started the jump (he is 6’3” for reference)
I think very little that is on the mls works as traditional LTR with current market financing and what does work often goes real fast. So I recommend you network and try to go off market. Realize off market often has risk or requires work. Rent ready stuff with zero risk usually does not have a need to sell off market. Some realtors have off market listings, but the best go to their preferred clients. Because off market is by definition not to every agent, do not commit to a duration based exclusive contract if you are interested in pursuing off market listings. Investor friendly agent should understand that you do not want to limit your sources of potential RE. Both agents I have used recently on offers understood this and the agreement was property specific.
I think IRR by itself is a bit simplistic as RE has tax savings, equity paydown (which can be included in IRR formula), leverage, and selling costs, but IRR does pretty good as it includes the cash flow and appreciation (or projected cash flow and projected appreciation). These "extras" adds complexity to the formula. It gets more complex if you can use REP or "STR loophole" (terrible name) to reduce w2 earnings. Combined with accelerated depreciation can make this complex. We qualify as REP. We could qualify via STR loophole but because we do not need it, our co-host exceeds our time spent (must be more time than anyone else). if we needed it we would pick up some items that we currently have co-host doing.
If I put $150k towards a purchase that saves me $50k in taxes (such as accelerated depreciation on $600k condo with virtually no land basis), is this the same as investing only $100k? I think it is close to the same as my net out of pocket for the year is $100k with the purchase of that property. But assuming I liquidate before I die without a 1031, that depreciation is recaptured. So with current rules, keep or 1031 until you die. Especially in CA with the advantages of prop 13. If the depreciation is never recaptured, it seems the same from my perspective.
the Dave Meyer appreciation forecast was actually a podcast. I remembered it was a blog because I read it and did not listen to it. You should be able to find it by internet searching ‘Dave Meyers BiggerPockets appreciation 2025”. To summarize in a single statement is virtually everything is possible with respect to residential appreciation, but the most likely is flattish.
good luck
Very cool! The biggest I have ever jumped was about 40 feet somewhere at Malbu Creek a long time ago, and the first time I landed with my arms out and that did not feel good. Those are really high jumps. 100 feet is nuts - you land wrong and things could be very bad! I hope your son stays healthy for a long time. There are crazy videos of guys doing like quadruple gainers from that height on Youtube, and I am always a bit concerned for those guys.
Thanks for the recommendation to network and look off market, and the details/warnings surrounding this pursuit. I was approached recently with a duration-based exclusivity contract from some commercial agents I was talking to, and it didn’t sit right with me. Property-specific (i.e. termination upon execution of a deal) does sound better than being locked in for a fixed period of time.
My current model accounts for the things you mention (tax savings, equity paydown, leverage, selling costs, cash flow, and appreciation) but it needs some fixing up and that is why my first order of business is to solidify the model so I am prepared to underwrite accurately. I am not familiar with REP or STR loophole - I will take a look at these and see if they are feasible for me and if so I will add them to the model.
Hmmm now you have me thinking about a condo option with accelerated depreciation. Your note about the depreciation being recaptured upon liquidation is important, and I will keep that in mind.
I will also look for the Dave Meyer podcast that you are talking about.
Thanks again for your advice Dan, and for bringing a realistic, conservative approach that I should utilize. Happy Thanksgiving to you and yours!
Welcome, Randy! Great move focusing on multifamily in OC, San Clemente and university areas like UC Irvine and Chapman have strong rental demand. For tools, BiggerPockets calculators are a solid start, and if you want more depth, look into Excel models like Zuber's or REI Deal Analyzer. Happy to help if you want feedback on a deal or strategy.
Randy, great start—house hacking a small multifamily near beaches or campuses is a smart way to offset your payment while you learn. For analysis, keep it simple: use a basic rental calculator to test your buy box (conservative rent, realistic expenses), then sanity‑check with a local property manager on true rents and vacancy. Also, run at least 20 deals in your target ZIPs so patterns pop and you don’t fall in love with one listing.
Randy, great start—house hacking a small multifamily near beaches or campuses is a smart way to offset your payment while you learn. For analysis, keep it simple: use a basic rental calculator to test your buy box (conservative rent, realistic expenses), then sanity‑check with a local property manager on true rents and vacancy. Also, run at least 20 deals in your target ZIPs so patterns pop and you don’t fall in love with one listing.
Randy, great start—house hacking a small multifamily near beaches or campuses is a smart way to offset your payment while you learn. For analysis, keep it simple: use a basic rental calculator to test your buy box (conservative rent, realistic expenses), then sanity‑check with a local property manager on true rents and vacancy. Also, run at least 20 deals in your target ZIPs so patterns pop and you don’t fall in love with one listing.
Great question—you’re right to care about accuracy. Two tips: start with a simple back‑of‑napkin cash flow to decide if a deal is worth deeper work, then layer your detailed spreadsheet only on the top few. Also, keep taxes separate: plan with a CPA, but don’t bake deductions into initial deal cash flow since they don’t pay the mortgage.
@Elealeh Fulmaran Thanks for this advice! The first one makes sense to me - it would be a waste of time to overanalyze every scenario that comes my way. As for the tax deduction, shouldn't it be a part of the detailed IRR calculation, since it is ultimately realizable money I get to keep? Maybe I misunderstood.