Paid Cash for all deals Good or Bad?

Paid Cash for all deals Good or Bad?

Rental Property Investor · Dallas, TX · Member since 2020 · 10 posts · 17 votes

Hi everyone, so here’s the story. I played in the NFL for 8 years. While playing I always said that when I retired I wanted 10 properties and no debt. I was afraid that if I allowed debt to pile up while playing, and something crazy happened I could be in trouble. So while investing in real estate I did so very slowly and paid all cash for every deal. I retired this past season and I’ve been weighing the idea of refinancing my homes to take money out of them or getting a line of credit against a few properties. I currently have just over $2mil in equity in those properties. I’ve been listening to BiggerPockets faithfully for the past 9 months and I really think I’m going to start leveraging but I want to weigh all my options and not overdue it. So what I’m looking for are thoughts and suggestions on if I should refinance my current properties or if you think I should leave those properties in cash as security and leverage all future properties. Recently on a BP podcast someone said, and I don’t remember who it was. But they said they intentionally had one property completely paid off and in case something crazy happened like Covid 19 they’d take money out of that home to get through. I liked that idea but again, I’m open to others. Thanks in advance!

14Reply
149 views

Most Popular Reply

Real Estate Agent · Sandwich, MA · Member since 2014 · 974 posts · 636 votes
6y

@Joshua Robinson

Very cool story! Can you live happily off of the cash flow that the rentals are throwing off or are you yearning for more? If you're happy with the income, while you won't be optimizing your returns because of all the equity in the properties, you've already made it to the "finish line." I'm sure there will be a bunch of people who come on and say you need to leverage up in order to get better returns on your equity but there's something to be said for having peace of mind without debt.

See this reply in the discussion

33 Replies

Jump to latestLatest
  • Investor · SC NC, VA · Member since 2020 · 1k+ posts · 756 votes
    6y

    In comparison, I have always leveraged whatever debt is available. This freed up monies for to invest and max a 401k. This also Means that the equity value of my real estate is a couple times yours and most importantly - aside from my first purchase using my VA and $1500, I have NEVER used any of my paycheck to buy any property I have ever owned.

    Leverage is your friend. Do your homework in 1031 exchanges. With $2M in equity seek a lender of the Fannie/Freddie small loans ($1-7.5M) at 80% LTV and go by $10M in properties while maxing cash flow!

  • Stephen KeigheryBusiness Member
    Rental Property Investor · New Orleans, LA · Member since 2018 · 717 posts · 555 votes
    6y

    @Joshua Robinson congratulations on your success so far. It sounds like it's half time and you have a nice lead. So how do you play the second half, do you want get defensive or for stay aggressive and go for the Jugular. You could go either way really.

    If I was you I would leverage about half your property for growth and keep half paid. You should have enough to grow and also a solid safety net.

    Home Buyer Louisiana4.855 Reviews
  • Real Estate Broker · Austin, TX · Member since 2016 · 834 posts · 449 votes
    6y

    Low interest rate long term debt is preferred in this market due to the M2 money supply going up and the probability of inflation in some asset classes and deflation in others. In addition to inflation the velocity of money is and will continue to slow down which could put deflationary pressure on the dollar and certain asset classes. 

    When our currency devalues eventually due to money printing the banks/lenders will in effect be transferring wealth to you in regard to your financed properties.  

    Example

    Today 

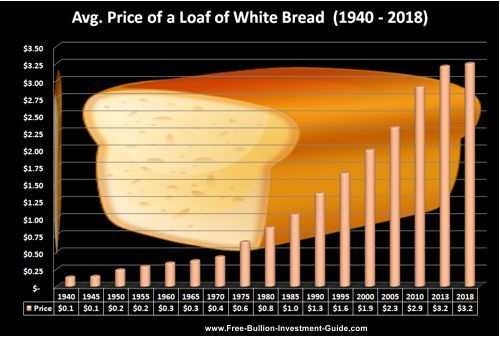
    A loaf of bread costs $2.50 and you have 100k left on a loan balance

    So it takes 40,000 loaves of bread to pay off your note currently.

    After inflation

    A loaf of bread costs $10.00 and you have 100k left on a loan balance

    So it takes 10,000 loaves of bread to pay off your note. Your 100k loan just isn't that much after adjusted for real inflation should this occur. Most economists I follow believe this is a likely scenario. 

    Inflation should generically reduce your comparative real debt along all asset classes.

    Caveats:

    1. Inflation/hyper inflation happens in asset classes that a majority of people use: food, fuel, durable goods, commodities

    2. We are talking about debt here not values of homes. Those could be inflationary or deflationary in this environment depending on your location 

    3. Adjusted for inflation we could all be in a world of hurt across all asset classes depending on the severity in purchasing terms. That could be a good time to sell!

    4. Inflation is underreported by the government so do more research to get better numbers. look up the website "shadow stats" for a more realistic number

    5. 1 roll of TOILET PAPER could be worth an ounce of gold!  (JK)

    As always, this is just my opinion.

    Danny

  • David NutakorPro Member
    Rental Property Investor · Palmdale, CA · Member since 2016 · 122 posts · 88 votes
    6y

    @Joshua Robinson, l suggest you apply for HELOC on one or two of your properties instead of refinancing. I tried both methods and HELOC was much better because the cost involved was minimal. Also, there was no significant loan origination and closing costs.

    I’m surprised to hear that your 1031 exchange didn’t go well. Please get in touch with @Dave Foster and he will make sure that you don’t lose money when doing a 1031 exchange on your property. He knows everything about 1031 exchange and he is always willing to share his experience with other investors.

    Good luck on your investment.

  • Investor · SC NC, VA · Member since 2020 · 1k+ posts · 756 votes
    6y

    I cant understand why you think in a 1031 by buying up you are losing cash.  NEVER do a 1031 where you’ll be making less cash flow than before.  The whole idea is to make more money each month while deferring capital gains, not less.

  • Real Estate Broker · Coppell, TX · Member since 2011 · 5k+ posts · 4k+ votes
    6y

    Welcome to DFW....we're glad you're here.

    Cash vs leverage.....everyone is different.   You have the Dave Ramseys of the world who say buy everything in cash.  That has worked for him.   It also worked well for the Roy Kelleys of the world.  If you've ever been to Hawaii, he is the guy who owned the Outriggers Hotels and from what I always heard paid cash for everything.  Recession hits, Covid hits, black friday hits...he is still in business.

    You have the other side of the crowd like Trump and plenty more who will leverage everything to the hilt.   It works when the market is going up, but can cause people to loose everything when the market moves against you.   Maybe like buying stocks on margin.  You look like a genius when the market is cruising along....then get wiped out on black Friday, or Covid Monday.  Plenty of highly leverage real estate investors got wiped out in 2007/2008.

    Maybe there is a balance too....where you finance 1/2 and still in a safe position.

  • Dave FosterBusiness Member
    Qualified Intermediary for 1031 Exchanges · St. Petersburg, FL · Member since 2013 · 9k+ posts · 9k+ votes
    6y

    @Joshua Robinson, It speaks to the dilemma you're pondering right now - The 1031 exchange does not cost you cash unless you are only purchasing for cash.  Most investors doing 1031s will use only the cash generated by the sale and add leverage to that to purchase their identified properties.  I love to see people acting conservatively.  And while there may be good or bad or ugly debt one thing is sure - debt = risk.  So the less debt you have the less risk you have.  But there are ways to mitigate that risk.  The 1031 exchange affords you the opportunity to shape your portfolio and add small amounts of leverage that you manage with a sharp eye to keeping your entire portfolio sustainable.

    I have many clients who keep a mix of debt free and leveraged properties.  Not one of my clients who owned properties for cash or with low debt in the last crash ever lost money.  They just waited because they could.  The key is to manage that debt and stay safe.

    The 1031 Investor5140 Reviews
  • Rental Property Investor · Dallas, TX · Member since 2020 · 10 posts · 17 votes
    6y

    @Mark H. Porter

    Sorry for the confusion, when I spoke of the 1031 exchange. Here’s a example. I have $200k in cash and a property that I sold for $200k. In doing a 1031 exchange I purchased a new property that was $300k. Remember I’ve done all cash deals, (which now as I think about it, maybe I shouldn’t have)but that’s the comfort I needed while playing. I would have to spend $100k of my cash in order to complete the transaction. This is what I meant by eventually I would run out of cash. If I wasn’t doing all cash it makes much more sense.

    Thank you all for the comments. I will personal message those who said some things that I don’t understand or quite grasps.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.