Minneapolis Duplexes: The Cheapest Communities Appreciated Fastest
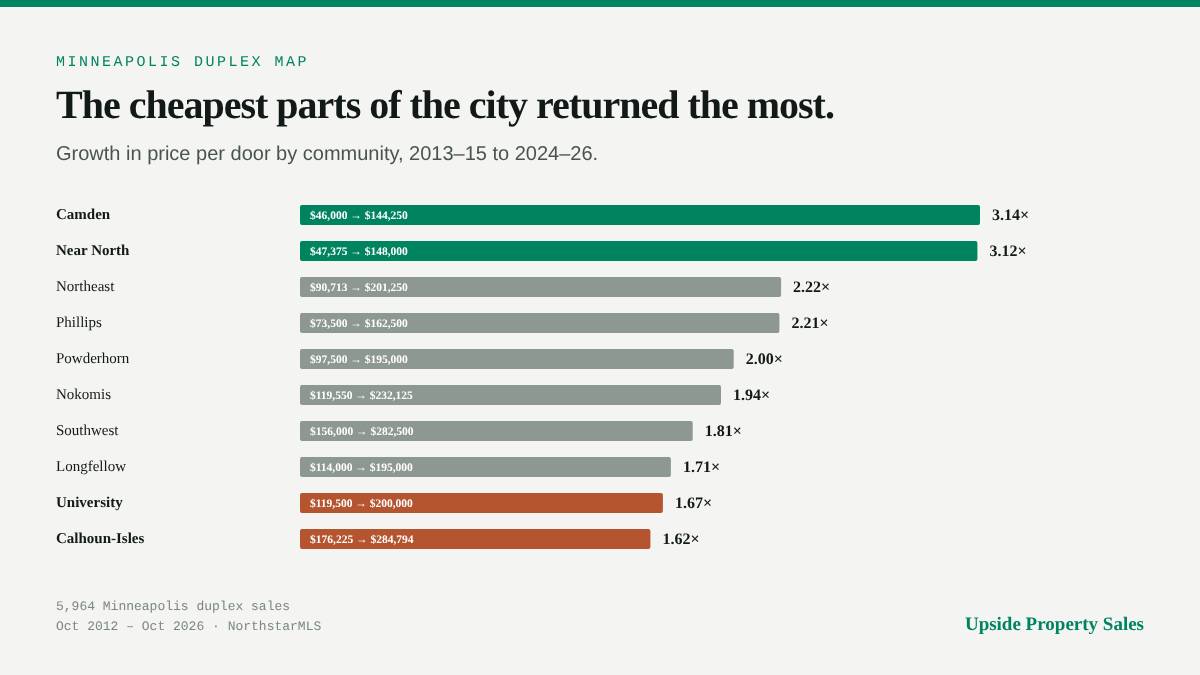
I ranked all ten Minneapolis communities by duplex appreciation over 11 years, and the ranking is close to inverse to price.
The method is below, then the numbers, then where I think it breaks. Tell me what I got wrong.
THE DATA
5,984 closed duplex sales in Minneapolis, October 2012 through October 2026, NorthstarMLS. I grouped the MLS neighborhood field into the city's eleven official communities and dropped Central (downtown), which only had 18 duplex sales, leaving ten communities and 5,964 sales. Price per door is sale price divided by two.
TWO INDEPENDENT MEASURES
I didn't want to publish a single-method ranking, so I ran it two ways.
The first is the change in median price per door between 2013-15 and 2024-26. It's simple, but it isn't quality-adjusted.
The second is matched repeat sales, which finds buildings that sold twice and subtracts. That removes mix effects because it's the same building both times. I kept only holds of two years or more with both prices above $50,000 and no decline steeper than 35%, which gave 1,113 pairs.
The two rankings agree at a Spearman rho of 0.67. That's decent but weaker than the 0.886 I got in St. Paul, and I explain the gap below.
THE RANKING (growth in $/door, 2013-15 to 2024-26)
Camden 3.14x $46,000 -> $144,250
Near North 3.12x $47,375 -> $148,000
Northeast 2.22x $90,713 -> $201,250
Phillips 2.21x $73,500 -> $162,500
Powderhorn 2.00x $97,500 -> $195,000
Nokomis 1.94x $119,550 -> $232,125
Southwest 1.81x $156,000 -> $282,500
Longfellow 1.71x $114,000 -> $195,000
University 1.67x $119,500 -> $200,000
Calhoun-Isles 1.62x $176,225 -> $284,794
The top two both started under $50,000 a door, and the bottom one started at $176,000. Citywide, the median door doubled, from $100,000 to $200,000.
REPEAT SALES VERSION (median annualized, same building twice)
Near North 10.4% (155 pairs), Camden 9.0% (70), Northeast 8.5% (269), Nokomis 6.8% (60), Longfellow 6.4% (78), University 6.3% (37), Powderhorn 6.2% (173), Southwest 5.6% (123), Phillips 5.4% (57), Calhoun-Isles 4.2% (84)
The top three and the bottom one are the same on both lists. The big disagreement is Phillips, which is fourth by median and ninth by repeat sales. My read is that a good chunk of the Phillips median gain is better buildings selling now compared to what sold in 2014, and the repeat-sales number is the one I'd trust there.
THE CONVERGENCE
The spread between the cheapest and priciest community:
2013-15: 3.83x ($46,000 Camden to $176,225 Calhoun-Isles)
2018-20: 2.44x ($105,800 Near North to $258,340 Calhoun-Isles)
2024-26: 1.97x ($144,250 Camden to $284,794 Calhoun-Isles)
Minneapolis's duplex market got a lot more uniform, and most of that happened before 2020.
WHERE IT IS MOVING NOW
This is the part that keeps an eleven-year ranking from being misleading. Change in median price per door from 2020-22 to 2024-26:
Nokomis +16.1% (1.94x since 2013)
Southwest +12.4% (1.81x)
Camden +12.3% (3.14x)
Near North +11.7% (3.12x)
Phillips +8.3% (2.21x)
Calhoun-Isles +6.1% (1.62x)
Northeast +5.9% (2.22x)
Powderhorn +4.0% (2.00x)
Longfellow 0.0% (1.71x)
University -3.8% (1.67x)
This is different from St. Paul, where the cheap neighborhoods that led the eleven-year ranking went flat after 2020. In Minneapolis the North Side is still moving, but Southwest and Nokomis are moving just as fast or faster, so price no longer predicts growth. The gap is still closing, just slowly.
One neighborhood-level note, because it gets lost at the community level: the Uptown area is going backwards. Whittier is down 11% and Lowry Hill East is down 10% since 2020-22, and South Uptown (formerly CARAG) is down 3%. Those are 20 to 45 sales per window, so treat them as a signal and not a verdict.
ENTRY PRICE TODAY (median $/door, 2024-26)
Camden $144,250, Near North $148,000, Phillips $162,500, Powderhorn $195,000, Longfellow $195,000, University $200,000, Northeast $201,250, Nokomis $232,125, Southwest $282,500, Calhoun-Isles $284,794
WHERE IT COULD BE WRONG
1. Price per door is not quality-adjusted. If North Side duplexes selling today are much nicer than the distressed inventory that sold in 2014, part of that 3x is the buildings improving rather than the area. The repeat-sales version exists to check this, and it still puts Near North and Camden on top.
2. 2013 was the bottom for the cheap areas. More than half the duplexes that sold in Camden and Near North in 2013-15 went for under $100,000 total, and a lot of that was post-foreclosure. If I start in 2014-16 instead, Near North drops to 2.47x and Camden to 2.36x, though they still rank first and second and Calhoun-Isles is still last at 1.41x.
3. Some rows are thin. University has 37 matched pairs and Camden had 61 sales in the early window. Northeast with 1,383 sales and Powderhorn with 1,018 are the rows you can lean on.
4. 2026 is a partial year, running through October 2.
5. This is duplexes only. My St. Paul numbers included triplexes and fourplexes, so don't line the two cities up row for row.
6. None of this is income. It's what buildings sold for, and the fastest appreciating areas aren't automatically the ones that cash flowed best.
The practical read: if you're buying on the strength of the eleven-year column, you're buying a run that mostly already happened. The recent column is the one that applies to a purchase this month, and in Minneapolis it says the cheap end and the expensive end are now growing at about the same rate.
Poke holes in it.