Investor · The Woodlands TX / Avon, CT · Member since 2009 · 6k+ posts · 10k+ votes
How to Make REAL Money in Real Estate
We all (well many of us) know, or at least suspect that CREATIVITY is the key to real estate wealth, but WHAT does that mean?
To me, it means being able to RECOGNIZE an opportunity to earn a substantial profit, understand the level of associated risk, and have the knowledge of how to execute the transaction/purchase, the operations and the transaction/sale.
Here are some actual examples
Borrower came to us for a loan, but his retail/service center couldn’t carry 13% interest loan. So instead my partner and I put up $200k (about 20% ownership value) and refinanced using our credit at 4% fixed 20 year no balloon mortgage, for which we received 60% ownership. The property cash flowed $100,000+ annual for three years and we sold out for a $700,000 + profit
Borrow came to us for a loan on their land smack in the middle of a near downtown development they’ve been the developer of for the last 12 years. But foreclosure is difficult in that state and borrower had legal issues. We purchased the existing note from the note holder with borrower paying us $350,000 UPFRONT and signing over a deed in lieu of foreclosure with an option for the borrower/seller to buy back the property over 2 years at a price giving us a 20% minimum annual return. In addition $150,000 of the borrower’s $350,000 option money did NOT apply to the purchase base price so was a non refundable option fee.
Commercial real estate broker brought us a deal for a purchase lease back of 2 auto collision shops for $3.8 million. Since we believed the property was worth less than that we declined. The broker called the lender, and told us we could purchase the note at a discount. We purchased the existing $3.3 million outstanding balance note for $1.9 million, and restructured the note with the borrower. Unfortunately, after a year the borrower defaulted. We foreclosed on the properties, sold one for $2.3 million, and are leasing the other one for $10,000 per month 3N while we await a good offer.
Anyone else have examples of how they used creativity to structure a profitable transaction?
I'm curious how many people buying Class D rentals in places like Detroit, Gary, Baltimore, Cleveland, Chicago, and Philadelphia are actually making "real" money. Especially if they're just buying them off of the MLS. Can you make money? Of course, and there are people that do, but many of the people I see buying well-priced properties end up losing money and not making money.
I share this because you, as well as Jay, have great and interesting deals. Those deals come from the experience you have creating deals and knowing how to make money - which is not something a weekend guru can teach you quickly
Mine are not quite as complicated as yours.. However I have done some participation loans.. probably 10 or so with small builders/developers.. were we take a first position at an agreed interest rate then a % of profit or sometimes refi proceeds if they buy us out.. These can spin the return wheel pretty significantly when they work as you intend.
I'm curious how many people buying Class D rentals in places like Detroit, Gary, Baltimore, Cleveland, Chicago, and Philadelphia are actually making "real" money. Especially if they're just buying them off of the MLS. Can you make money? Of course, and there are people that do, but many of the people I see buying well-priced properties end up losing money and not making money.
I share this because you, as well as Jay, have great and interesting deals. Those deals come from the experience you have creating deals and knowing how to make money - which is not something a weekend guru can teach you quickly
Exactly right. A guru “mentorship” can not possibly provide the knowledge needed to be able to analyze, strategize, and execute as needed to “make the deal” happen.
As I continually preach, it starts with the BASICS - a working knowledge and understanding of real estate principles, real estate law, and real estate finance. No “guru” courses on these, because without the promise of easy roaches no one is gonna pay $40,000 for what they can get from reading a few text books (and understanding and practicing those principles). Further, it’s WORK, Without the “tribe”, “mentor”, “bs stories”, false promises, statistical lies, major hype, and slick marketing.
I'm curious how many people buying Class D rentals in places like Detroit, Gary, Baltimore, Cleveland, Chicago, and Philadelphia are actually making "real" money. Especially if they're just buying them off of the MLS. Can you make money? Of course, and there are people that do, but many of the people I see buying well-priced properties end up losing money and not making money.
I share this because you, as well as Jay, have great and interesting deals. Those deals come from the experience you have creating deals and knowing how to make money - which is not something a weekend guru can teach you quickly
I would throw Memphis in the mix also. Memphis is starting to have 1% rentals again, however when looking at the prospect of renting a property without Section 8, Some offers simply don't show well. I have come to realize, maybe some people dont "Need" as much of a return or Simply plan to do most of the work themselves.
I would be curious are properties selling at 80% or 75% LTV to satisfy DSCR Requirements.
OP. Our deals are more on the physical or market side versus the financial side. But there are still strategic financial components that make these hits. I'll explain the following at a level for non-investors.
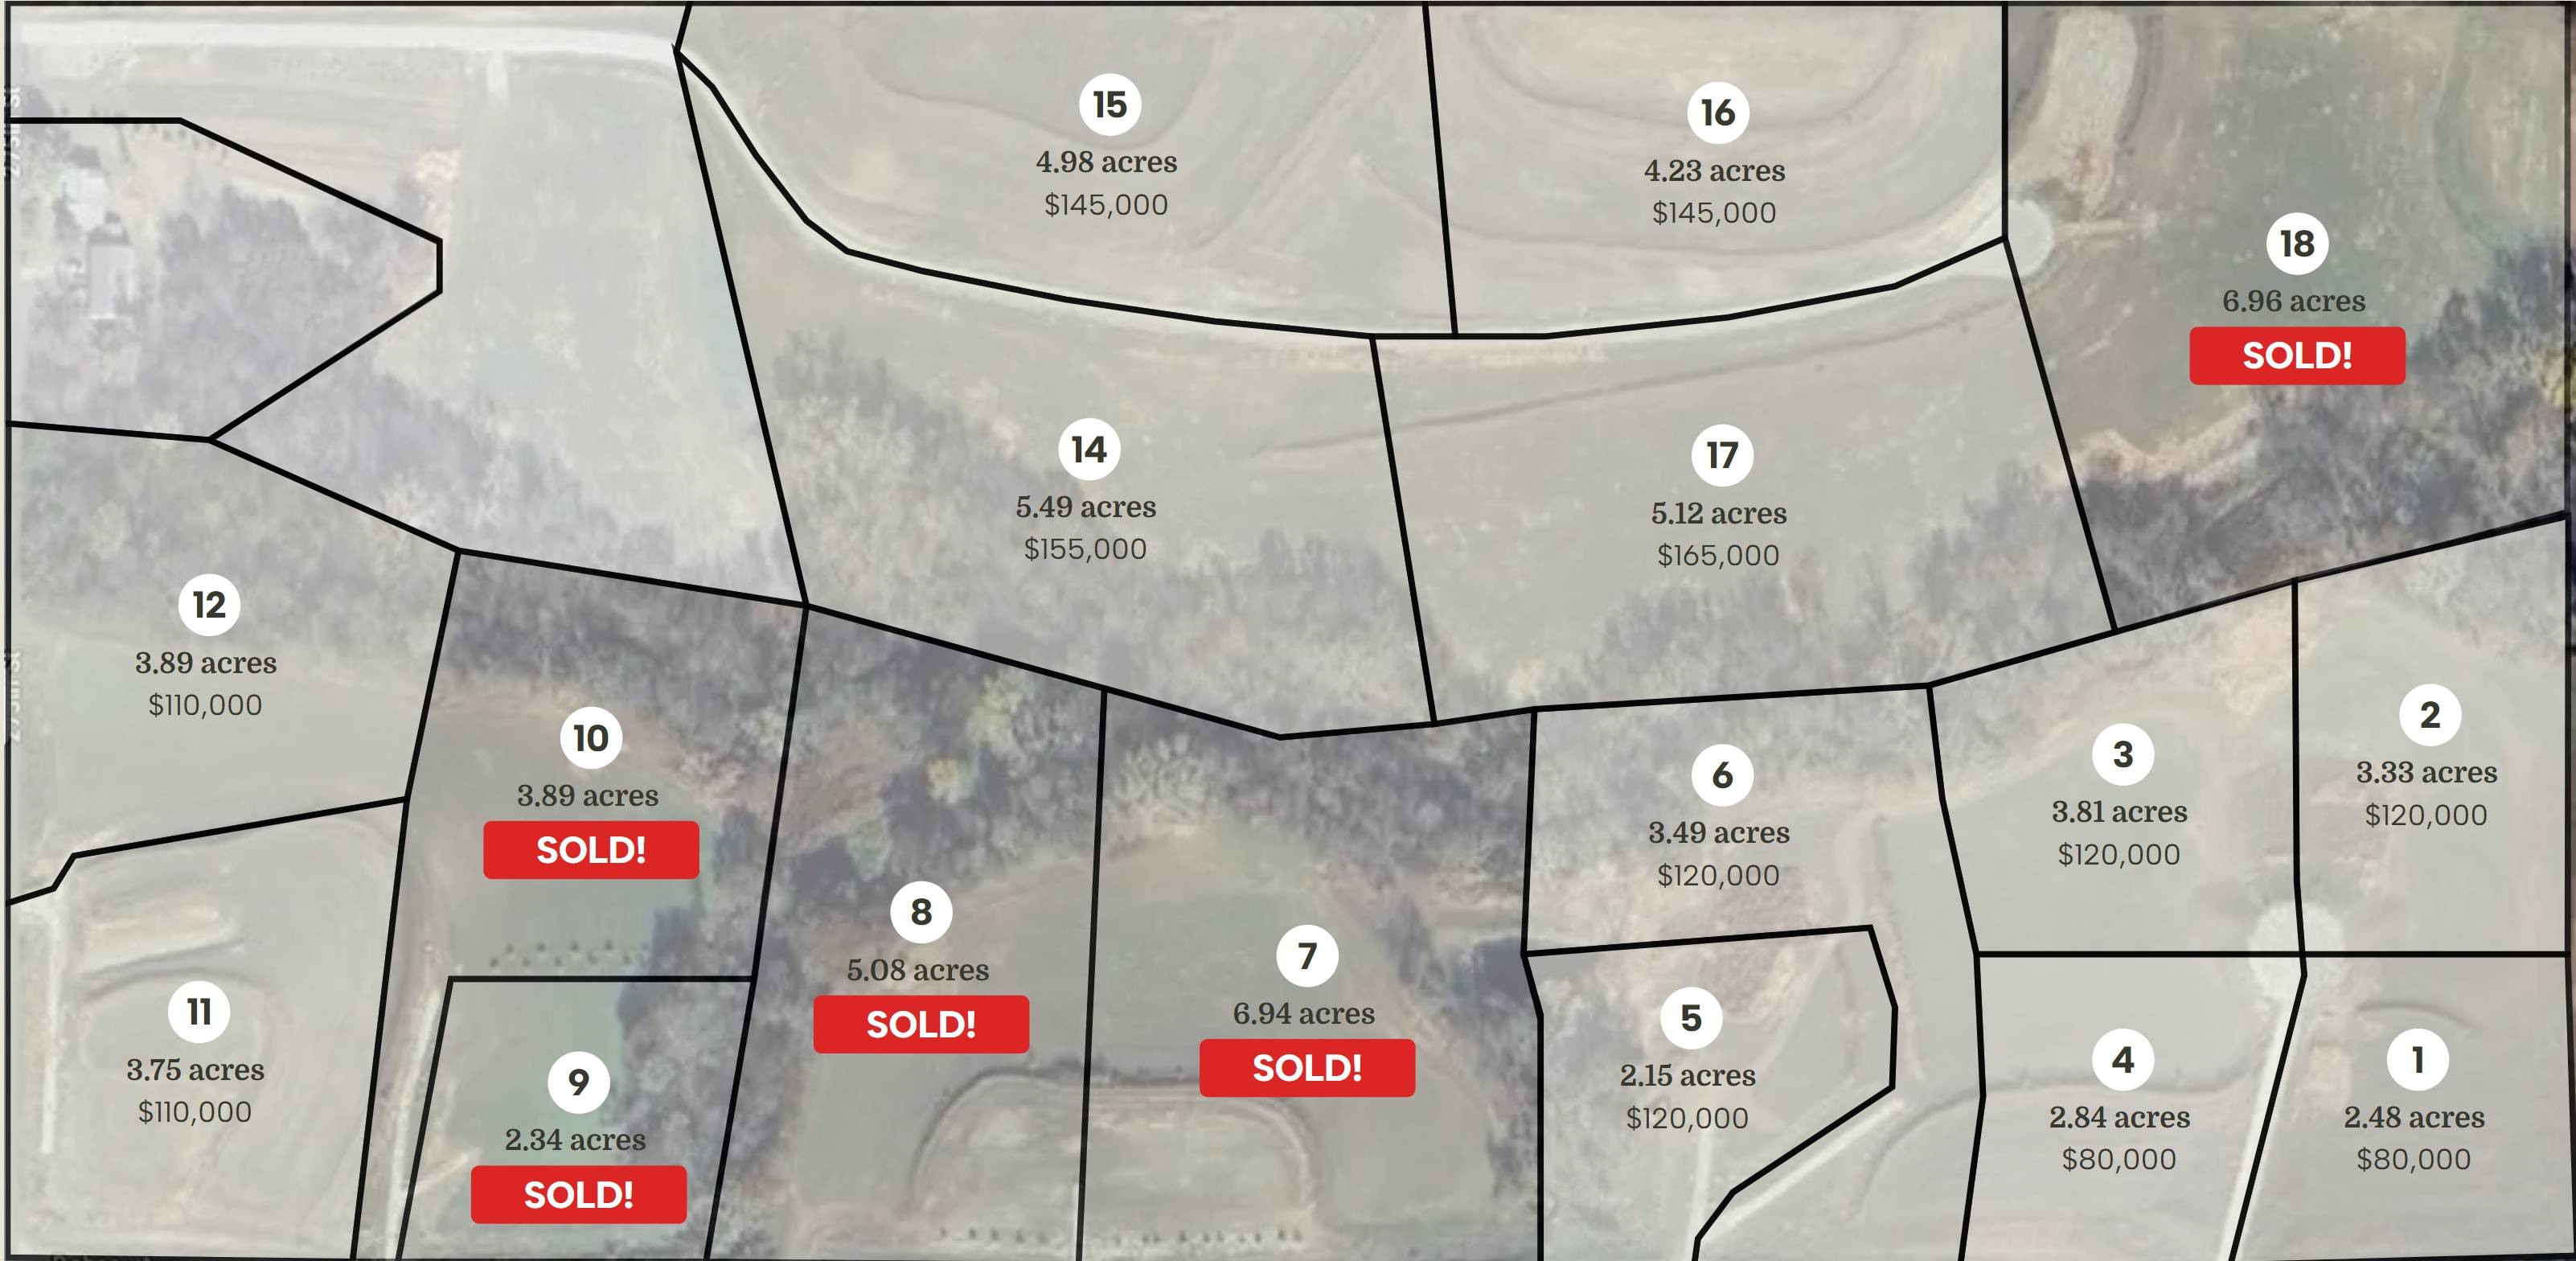
Example 1 above is our second Country Subdivision we have done. This is an example of what I call a Nasty property. Actually, clean farm ground, but:
75 acres- almost no homeowners can buy this large.
75 acres, but only 50 is farmable. There are ditches and streams with tall trees running thru the middle. Also, there are 4 entrances to get to all of the fields. Farmers hate moving equipment for small field sections. The farmers who would be interested in this "Small" of a farm are very limited and local. So not a lot of strong interest to Bid this property up. Was sold at an auction.
Traditional developers can't really bite into this. Farther from a high dollar market. 2 acre or larger sizes due to Water well/Sewer distances required. These are too large of lots for traditional concrete/Asphalt roads to be feasible, and the lot prices are not high enough to justify.
Folks- don't do this. We did cash financing. Right now, to me is one of the worst times to do a Subdivision; but we are comfortable with our Market mix. We need 18 buyers from a 1.3mm metro area to want to move here.
Size- you can do this on a 2 or 3 lot sized property. Size is irrelevant.
Time span- our first subdivision only took 11 months to sale out (Great Location). This one will take about 5 years.
Return- we would never do a deal like this unless over 100% return. This one will come in around 125%, but over the 5 years. Low risk. Projected return will increase when we sale over 50% of lots. Then we raise the Price. FOMO- fear of missing out kicks in.
Example 2:
Self Storage. We were building in a Town and then 2 of the existing locations ask if we wanted to buy. Ended up paying about 20% higher than I wanted to, based on each deals analysis. One of them we paid about 70% and the rest, noninterest loan to be paid in 5 years. The reason I was willing to pay more than the deal analyzed at. Self-storage is a weird deal. We were able to control about 60% of the market for that town. The other 40% was already 100% full. This allowed us to control the rental prices. Next town was 20 miles away. Self-Storage and majority of Commercial is valued based on CAP rates and NOI- net operating income. CAP rate is normally close to your Loan interest rate, even though they don't have anything to do with each other directly. Let's say 6%. NOI let's use a $10 per month or $120 price increase across say 250 units. 250 units x $120= $30,000. Using the full rate increase of $10, since there is no cost other than mailing notices and phone calls. $30,000 at a CAP rate of 6%= $500,000 valuation increase. So, we overpaid about $60,000 on both locations. But we took Risk out that renters would leave for another storage location, thus our $10 price increase would be firm. Two years later, another $10 per unit increase. "But" they will drive to the next town 20 miles away???? We are there already. This is our spider web approach. If you're near a large Metro area, then use our Wagon Wheel approach.
Time Span- Most Commercial loans require a 25% downpayment. Being able to generate another $500,000 valuation on day 1 and then say 2 years later.
Return- When we "develop" a new Self Storage location, we expect a 300 to 400% return COC on day one.
Risk management- "Will they Come?". As long as you know how to do your market study and understand zoning for current and any future competition the investment risk is very low.
Example 3:
Belize Teak Plantations- this is really not a REI strategy. We are in Iowa and wanted a warmer place. Once I got down there, I can't turn my Deal brain off. Grew up in a national forest in Louisiana. Locked on to Teak. You can read my detailed Belize Teak postings. This is a poor undeveloped economy. You can still buy beautiful river, stream, mountain, hilltop views cheap. The land ownership there is strange. These are long term 15 to 30 year investments. No cash coming out.
Example 4:
Walk away. Offer your Walk Away price, give 3 day offer, 30 day DD, 30 Day financing and then Walk Away. This is not really a Real Estate type of investment. It is a strategy. All of our successions are having Great deals on 1 thru 3 only worked using this Offer approach.
Find your niche and your strength. There is an approach for everyone in every market.
The above are for more financially capable investors.
If you have ZERO downpayment, ZERO experience, ZERO risk tolerance or assessment, ZERO for everything related to REI.
Seek out USDA loans.
Or join the US Military or Coast Guard. Or go overseas with a US Civil Service position. You will be a Millionaire in 20 years doing just basic investing.
OP's title- How to Make Real Money in Real Estate. Plus, I'm not charging you $1mm, which I would if I helped you. Don't call me, it's all in posts for free on BP.,
Henry.. on your country subdivisions what is the zoning. Can you bust those up by Right or do you need zone change or any other government approvals beside just the obvious survey roads perc test wells . how is power handled is it brought in overhead or underground.. And can it be extended as you build out. How about storm drainage how do you handle the water ??
@Don Konipol These are great examples of creativity being more than simply finding an unusual financing structure. In each case, the opportunity came from understanding the borrower’s problem, the property’s value, and the available paths to protect the downside while still creating a meaningful return.
That last part is easy to overlook. Creative deals can produce impressive results, but they often involve more moving pieces—title, priority of liens, borrower incentives, foreclosure timelines, environmental exposure, operating risk, and a realistic exit if the original plan fails. The structure only works when the economics remain acceptable under a less favorable outcome.
The strongest form of creativity may be finding several ways to win without depending on everything going perfectly. That takes experience, careful underwriting, the right legal and tax guidance, and enough patience to walk away when the margin is not there. It would be interesting to hear more examples where the original strategy changed but the structure still protected the investment.
Here’s one from many years ago, when I was more aggressive about building wealth…..
Through a number of transactions, I found myself owning a vacant city lot zoned for commercial/retail use, appraised at about $250k. There was no financing available for this property, and as a result would be impossible to sell at anything close to appraised value.
I purchased a 4 unit residential property that had been on the market forever. I paid $225,000 with $32,500 down and seller finance for the balance, about $200,000 (cover closing costs). The note was at 0% interest, amortized over 20 years ($833 per month) and assumable as well as having a “substitution of collateral” clause.
After closing I "substituted" the city lot for the 4unit as collateral, thereby freeing up the 4 unit to either mortgage or sell. After about 6 months of ownership I sold the 4 unit for $230,000 cash to me. The result was (so far) that I was out $32,500 + $833 per month for 6 months or about $37500. However I collected about $8500 net cash flow after operating expenses on the 4 unit , so net cash out $29,000. This is subtracted from the $230,000 I received from selling the 4 unit, so I put about $201,000 "in my pocket. However, I owed $195,000 remaining balance on the city lot. Net result was I was able to "finance" the city lot at about 80% LTV at 0 % interest!
BUT, I wasn’t through yet. I spend about $7 or 8 k to put a pre fab type building (office) on the lot and another $5k putting a low cable like fence. A friend of mine was in the used car business and wanted a second location for his son. I leased the location to him with a $5k deposit, no rent for 3 months, and thereafter rent of $1,000 per month. In addition I earned about 40% interest when I financed the purchase of some vehicles for him. While this rental broke even cash flow wise, my debt on the property was being reduced by $10k per year. Over the years I had about three or four different car lot tenants with maybe a total of 6 or 7 months where I didn’t receive rent. I owned the property 14+ years, paid the loan balance down to about $50k, and sold the lot for $370,000 to a developer as part of an accumulation package.
To give credit where due, I need to reveal that the idea for this transaction, as well as specific guidance, was provided to me by Jimmy Napier. I told Jimmy that I had a lot I didn’t know what to do with, and his creativity and conceptual ability can be observed from this transaction.
This is a great example of looking beyond the property itself and focusing on the terms, collateral, and exit options. The substitution-of-collateral clause was the key: it turned an illiquid lot into acceptable security, freed the four-unit for resale, and effectively created long-term financing on the land at 0% interest. Adding a simple income-producing use afterward made the structure even stronger while the tenant’s rent steadily reduced the debt.
The bigger lesson is that creative finance is rarely just about getting a low rate—it is about solving several problems at once and preserving flexibility. Of course, a transaction like this depends on a willing seller, precise loan documents, clear valuation of the replacement collateral, and legal review so the substitution and later sale work as intended. Credit to Jimmy Napier is well deserved; this is the kind of structure that shows how valuable an experienced mentor can be when a conventional solution does not exist. Thanks for sharing the full numbers and timeline—it makes the strategy much easier to understand.
We all (well many of us) know, or at least suspect that CREATIVITY is the key to real estate wealth, but WHAT does that mean?
To me, it means being able to RECOGNIZE an opportunity to earn a substantial profit, understand the level of associated risk, and have the knowledge of how to execute the transaction/purchase, the operations and the transaction/sale.
Here are some actual examples
Borrower came to us for a loan, but his retail/service center couldn’t carry 13% interest loan. So instead my partner and I put up $200k (about 20% ownership value) and refinanced using our credit at 4% fixed 20 year no balloon mortgage, for which we received 60% ownership. The property cash flowed $100,000+ annual for three years and we sold out for a $700,000 + profit
Borrow came to us for a loan on their land smack in the middle of a near downtown development they’ve been the developer of for the last 12 years. But foreclosure is difficult in that state and borrower had legal issues. We purchased the existing note from the note holder with borrower paying us $350,000 UPFRONT and signing over a deed in lieu of foreclosure with an option for the borrower/seller to buy back the property over 2 years at a price giving us a 20% minimum annual return. In addition $150,000 of the borrower’s $350,000 option money did NOT apply to the purchase base price so was a non refundable option fee.
Commercial real estate broker brought us a deal for a purchase lease back of 2 auto collision shops for $3.8 million. Since we believed the property was worth less than that we declined. The broker called the lender, and told us we could purchase the note at a discount. We purchased the existing $3.3 million outstanding balance note for $1.9 million, and restructured the note with the borrower. Unfortunately, after a year the borrower defaulted. We foreclosed on the properties, sold one for $2.3 million, and are leasing the other one for $10,000 per month 3N while we await a good offer.
Anyone else have examples of how they used creativity to structure a profitable transaction?
Deals like these are not created within the "system" that Guru's offer. These deals are created on the need of on party and the ability of another party to realize the most mutually beneficial structure.
How do you approach negotiations to end up in the driver seat in such a way?
not answering for Don.. however for me these deals are just a process. IE getting my RE license at 18 and my brokers at 20 being in the game. You meet all sorts of folks.. once chance meeting is all it can take sometimes.. Then for lending I got into HML in my early 30s.. and development along the way.. Then Post the GFC I became an accidental home builder/developer IE builders i made loans to failed and I had to take the projects over
not answering for Don.. however for me these deals are just a process. IE getting my RE license at 18 and my brokers at 20 being in the game. You meet all sorts of folks.. once chance meeting is all it can take sometimes.. Then for lending I got into HML in my early 30s.. and development along the way.. Then Post the GFC I became an accidental home builder/developer IE builders i made loans to failed and I had to take the projects over
I have some opportunities in front of me. To be honest, I realized how to raise capital and that is something that i have never taken advantage of. Doing my first deal with OPM, Raising Capital has opened up my eyes to the possibility. Consequently, Some of the more creative deals are:
over longer periods
Due to challenging circumstances.
Require the experience to Manage a failed project to completion
I have some experience with the process of building, rehabs and rentals. However I havent been in the hot seat many times. What would you say to help me leverage those opportunities in a similar fashion as yourself. Particularly as in the Development arena working with a Private HML.
First, I look at a LOT of deals - probably about 500 + per year.
Second, I have a good real estate education - college courses in real estate principles, real estate finance and real estate law; studied for brokers licenses in 3 states; successful completion of CCIM commercial courses; read about 100 real estate books
Third, 50 years experience as real estate investor, lender, broker, syndicator and fund manager.
Comes from a lifetime of learning and doing. Plus, I’m a natural “deal maker”; I’m happiest putting deals together, especially creative deals.
Impressive, Don! I've become pretty passionate about creative financing myself, but you take deal structuring to a whole different level!
I'm currently working on a mobile home park deal here in Florida. I submitted an offer at $1.05M with creative terms, and the sellers came back at $1.1M with some adjustments. So we're still negotiating.
What's interesting is that I'm evaluating several ways to structure the deal. I could acquire and hold it myself, bring in an end buyer; local investor looking to get into the multi-fam space, or potentially partner with that buyer on a long-term hold.
There are also several opportunities within the property itself: selling some of the park-owned homes to existing tenants to reduce debt, adding homes to vacant pads, potentially developing additional pads on the vacant land, and even selling off the single-family residence or using it as housing for an on-site manager.
Lots of moving pieces, but that's what makes these deals interesting to me! I'm trying to figure out which combination creates the most value while keeping the risk manageable. It's been in discovery and negotiations for a year+
What fascinates me about creative finance is that sometimes the real opportunity isn't negotiating the lowest price, but finding a structure that works for everyone involved.
With your experience, Don, I'm curious how you approach a deal when there are multiple potential structures and exit strategies. Do you work backward from your preferred exit, or let the seller's priorities help determine the structure?
Well, honestly, I never let the seller’s priorities determine anything I do, because I never HAVE to purchase any specific property.
I concentrate on what works best for me to reach my goals. If the seller can also benefit, to a lesser or hopefully greater degree, then we will probably have a deal. If not, we both move on.
I analyze any "deal" as to risk, ROI, portfolio fit, and lifestyle fit.
When I analyze what will “work” for me in a deal I next determine if it would be a good outcome for the seller. If I believe the seller could do better, I’ll let them know that and how I think they could achieve a better result, either by obtaining a partner with a capital infusion, or selling to someone who may pay more. It’s amazing how many sellers either just want to accept my deal, or who come back later for my (pretty much” guaranteed) closing. I say “pretty much” guaranteed because one I commit the ONLY reason I won’t close is if the seller has either lied about something, or with held vital information/knowledge. So if the seller represents thru financial statements that the net income is $300,000 per year, and when required to provide tax returns the net income after “add backs” is $175,000, I don’t feel obligated to close as I was deceived by the seller.
Now specifically for MHP - experienced MHP investors understand that (1) a park where all pad sites are leased to people who own their home is way more valuable than a park where tenants lease the home from the park, or where they’re purchasing their home from the park. Further, parks with newer tenant owned homes are more valuable than parks with older tenant owned homes. The reason is quality of tenants, turnover, collections and evictions, etc. Further, in a park with POH the pad site rental should be separated and valued differently than the mobile home rental. Mobile home rental is not a real estate rental, it is a personal property rental. While real estate rental in MHP may carry cap rates of 7 for the largest newest parks to mid teens for older, rural type parks, mobile home rental income not only carries cap rates from 20% on up but the net income must be reduced by actual depreciation. This is why a lot of MHP owners with a majority of park owned homes on their pad sites think the park is worth $2 million while an appraiser values it at $900,000 and the mobile homes owned at $225,000.
Now, one more note of clarification. When I say what also WORKS BEST for a seller I DON’T mean some fuzzy thinking idea of “fair” price or not “taking advantage” of someone. It all depends on the circumstances. A prime example of this was I was approached by a seller who owned a 50% interest in a property who needed to sell within 12 hours (while I’m not at liberty to explain WHY, I did know this to be true. His big problem was that the owner of the other 50% was known as a SOB and was going to be a “never ending” problem. BUT, I knew his partner, and how to deal with him (I may be the only one who could). So, I told the seller I would only offer $15,000 for his 50% interest, and to shop it to everyone’s and anyone else who’ll pay more. He told me he already did, knew I’d pay very little, but I was his only hope. I did buy him out for $15,000. Two weeks later I sold my half interest to his partner for $175,000. I’m also not at liberty to explain why I was able to deal with his partner and no one else was.
Don, great points on the park.. also when thinking you can put in extra pads that can cost some significant money and then you have absorption to deal with which depending on the park can be years and years
Here’s one of the most creative and successful MULTI STEP real estate deals I have ever been fortune enough to witness.
This had to be about 40+ years ago. John Beck had been attending foreclosure tax sale auctions for about 5 years in California and Arizona. He said he had accumulated over 1000 properties (lots), most without utilities and many without road access! He paid $10 - $50 for each lot, and the few good ones he had sold for enough to pay for all his purchases three or four times over. This is what he CLAIMED, anyway.
Jimmy Napier asked him what he was going to do with the rest of the “recreational” lots he held. John said that he had been and was continuing to use them as either down payments for property he purchased, or as “sweeteners” in relation to estate trades (exchanges). Jimmy asked if he could buy some of those lots. I seem to remember he paid John $1000 for 20 or 25 lots.
Jimmy had been negotiating with the owner/seller of a rental duplex to purchase it with seller financing and nothing down. He approached the seller and offered the 20 lots as down payment. Interestingly theese lots were valued by the taxing authorities at $1500 a piece. The seller of the duplex looked up the tax value of the lots, and after some back and forth agreed to credit the lots at $1000 each ($20,000) as down payment on the duplex, providing seller financing for the balance at 0 % interest fully amortized over 15 years. He did this because (1) he wasn’t able to deal with the type of tenants attracted to this property and (2) Jimmy was paying him about 10% more than he duplex was worth, with no sales commission to reduce his “take”. So Jimmy bought the duplex, worth maybe $200,000, for $220,000, but actually costing him $1000 for the lots and taking on a $200,000 - interest note with payments all principle at $1,111.11 per month.
A deal like this would be creative and successful enough; but this was only step 1 for Jimmy Napier. Jimmy had worked into the note a “substitution of collateral” clause, and then went looking for a situation where he could multiply his “benefits”.
So, Jimmy comes across a MHP for sale, where the bank holding the loan just called the note; the park has many vacant sites, and most importantly the owner/seller has lousy credit. The seller owes $140,000, and any financing he is able to get to replace the bank financing is going to cost him 18%+ in interest, probably 25% with all fees. Jimmy works out a deal giving him 50% ownership to replace the financing with the 0 interest loan. He sells the duplex for about $208,000, uses $140,000 to pay off the existing bank financing on the MHP, and substitutes the MHP as collateral for the seller financed 0 % interest duplex note. This leaves Jimmy with about $60,000 in cash (the duplex’s cost him out of pocket the $1000 he paid John Beck for the lots), and half ownership of the MHP.
Jimmy purchases some used mobile homes, puts them on the vacant sites, and sells them with $250 down and owner finances the rest. He does this until the park is at 90% occupancy.
Not only is the park cash flowing, but a new appraisal put the value of the MHP at $550,000.
So, for a $1000 investment in some lots, and a lot of know how, wisdom, moxie and experience, Jimmy now has $60,000 cash, and about $200,000 equity in the MHP.
First, I look at a LOT of deals - probably about 500 + per year.
Second, I have a good real estate education - college courses in real estate principles, real estate finance and real estate law; studied for brokers licenses in 3 states; successful completion of CCIM commercial courses; read about 100 real estate books
Third, 50 years experience as real estate investor, lender, broker, syndicator and fund manager.
Comes from a lifetime of learning and doing. Plus, I’m a natural “deal maker”; I’m happiest putting deals together, especially creative deals.
I would love the opportunity to rattle off 50 years of experience in anything. I started in RE back in 2015. First deal was in 2016. While I dont have 50 years, I pride myself in looking at tons of deals a year. Ive made over 100 offers this year. I will commit myself to looking at more deals. that is something I can control.
I guess with the creative deals, I worry that i will confuse the seller. How do I avoid that and create understanding in something that isn't a cash close?
Lay it all out in writing g, in detail. Go over each point thoroughly, answer all questions and concerns honestly. Since I don’t deal with homeowners, only investors or business owners, more of my sellers or buyers are more knowledgable and experienced in real estate law, real estate principles and real estate finance. I tell the people I’m negotiating with that if they don’t think the deal I’m offering is in their best interest to pass on it. It’s surprising how many come back 3 months, 6 months , 12 months, even 3 years later and are then interested in my offer.
And one more thing. You have to believe your offer is (1) “legit”, (2) a viable alternative for the seller given HIS circumstances, goals, needs, and wants, and (3) has a good chance to get to the closing table. If, for instance, you believe that your offer is just a lowball and you’re trying to “steal” the property your chance of getting to the finish line just decreased about 95%. I never make an offer I’m embarrassed to defend or stand behind. And I’m never embarrassed to stand behind any offer I make.
Recently bought a deal where the lender foreclosed and did not want to have to deal with the eviction because of a problem tenant, so they sold the property to us for a 25% discount, which was approximately $100,000 discount. The property actually consisted of over 7 acres. After buying it, we subdivided the property from one lot into four lots and are now selling each one of those lots for $50,000 to $70,000 apiece. The cost of the subdivision was about $7,500. I would consider that a nice ROI.
I bought a house at the tax sale last Tuesday that is worth north of $550,000 and I only paid $66,000 for it. Not very creative but it might turn out to be very profitable. Time will tell....
I can only tell you that I will make at least 25% more than the $66,000 at this point. I'll get the deed in a few weeks and then get to go inside. There was no mortgage and there are no liens, there are $75 in HOA fee's overdue but that's it. It's a homestead so all I can do is rent it out for the next 24 months and see if they ever come back and redeem. The house is in a really nice neighborhood with a new pool added in the last few years. The previous owner was at the tax sale 30 minutes before it started and turned down the lawyers offer of a payment plan to catch up on his taxes. Lot's of questions as to why anyone would walk away from this kind of equity. I'll update more as the story unfolds.
Yeah, although it seems crazy, I’ve experienced people walking away from equity, even cash. We had one some years ago on a note we held; the borrower offered us a deed in lieu and gave us the name of a buyer who wanted the property. The buyer had offered $200,000 + more than was owed total on the property. We asked the borrower why he didn’t sell the property, pay us off and pocket $200,000. He said he was just sick of the whole thing and wanted out.
Can you offer the former owner some amount of compensation to sell his right of redemption to you?
Yes, good idea, we are considering offering something in exchange for selling his rights of redemption. Once I get the deed we will pursue that. Right now I'm concerned for the guys health. His truck hasn't moved since the morning of the tax sale and there are no lights on at night in the house.
i have purchased properties during the redemption period before. some owners just want out and will take moving money. the tax sale buyers are never happy because I pay the redemption cost and wholesale the property.
True creativity isn't pitching gimmicky seller financing on retail listings—it’s engineering a solution around debt, lien, or balance sheet friction that institutional capital won't touch. On our deal desk, the widest spreads never come from simply haggling over price; they come from stepping in ahead of a maturity cliff, purchasing discounted junior paper, or unravelling back-tax and title messes where the owner needs certainty more than top-dollar equity.
When you're structuring these note buyouts or equity injections, what is your absolute non-negotiable underwriting filter to protect your basis in case the borrower defaults and you have to take title and operate the asset yourselves?
With these admittedly ‘RISKIER" deals we would rarely go above 60% LTV on the money we "invest".
If the deal is involved in litigation we usually want a path out of litigation immediately after (or better yet before) our involvement
We used to do deals in two places we won’t do them any more - “war zones” (I made a lot of money in war zones and it still wasn’t worth it) and very rural areas (too hard to liquidate large type properties).
Very very selective on financing land and ultra careful with any type of assisted living facility. Totally eliminate older large former nursing homes or the like that are obsolete and worth about 10% of their appraised value, if that.
That’s seasoned wisdom right there. That point on "war zones" hits home—just because a deal can be profitable on paper doesn't mean the operational brain damage and friction are worth the return.
And spot-on with obsolete assisted living facilities; too many people get blinded by a past appraisal without realizing the conversion cost makes the underlying dirt the only real collateral.
Appreciate the unvarnished breakdown, sticking to that 60% basis floor and clear liquidation paths is how you actually survive market cycles.