Evaluating Kamala Harris’s Proposals For the Real Estate Industry

Evaluating Kamala Harris’s Proposals For the Real Estate Industry

Andrew SyriosPro Member
Moderator
Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes

Kamala Harris announced her plan for the economy, which includes many incentives and disincentives for the real estate industry. Many of her points are actually designed to stimulate the real estate industry, which could benefit investors (although cause some unintended consequences to boot). For others, we’re in the crosshairs.

Let’s take a look at each one individually and how they’ll affect the economy, particularly the real estate industry. We’ll ignore proposals that don’t relate to real estate—for example, a “price-gouging ban” or limiting taxes on tips—and just focus on our industry.

Helping First-Time Homebuyers

Harris’s plan is to offer “…first-time homebuyers with $25,000 to help with the down payment on a new home.” This would be the most significant down payment assistance the government has ever offered and dwarves the $8,000 First-Time Homebuyer Tax Credit that was in place between 2008 and 2010. That also happened while we were in the middle of a deep recession and credit crunch, unlike today.

In 2020, there were 1,782,500 first-time homebuyers in the country. Had all of them used such an incentive, that would have cost the taxpayer a cool $44.6 billion.

Of course, not every first-time homebuyer would use it. But then again, with such an incentive in place, demand for first-time homebuyers would likely skyrocket.

FHA loans already only require 3.5% down to purchase a home. And Fannie Mae dropped its required down payment for multifamily properties where the owner lives in one unit to just 5% last November.

Indeed, with a 3.5% down payment, a house that costs $714,286 would conceivably have the down payment completely covered by this program. (And this ignores seller credits, which are commonly offered to homebuyers during negotiations.)

Affording the down payment is an issue for prospective homebuyers, but not the main one. One recent survey found 40% of non-homeowners said that their inability to afford a down payment was their main obstacle. But more (46%) cited insufficient income. Especially outside expensive coastal cities with almost comically bloated housing prices, the biggest issue for homebuyers isn’t the down payment—it’s affording the monthly mortgage payments, especially with interest rates where they are.

By throwing money at the demand side without addressing the supply side, the most likely result is just to increase the price of properties all the more, as prospective homebuyers with $25,000 in government money behind them bid up prices against each other. This will make the mortgage payments even less affordable. This program could certainly be beneficial for house hackers, but on a policy level, it’s likely throwing good money after bad.

---

Continued Here: https://www.biggerpockets.com/blog/evaluating-kamala-harris-...

3Reply
46 views

Most Popular Reply

Bruce WoodruffPro Member
Contractor/Investor/Consultant · San Diego / Phoenix · Member since 2021 · 12k+ posts · 15k+ votes
2y

Beyond the very real possibilty that some overall good may come of programs such as the 'Down-payment assistance program'...there still lies at least a couple of flaws, conceptually and very real...

1) The Gov't (we) are forcing people who cannot afford to even think about buying a home to subsidize those who are in a more fortunate position. [Similar to the Student Loan Bail-out where people who made different (and smarter) choices, are forced to give up  their hard earned money to others.]

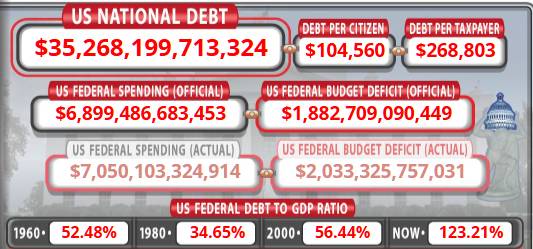
2) When is this country going to really realize that we are headed down a steep slope to ruin? We are $35 TRILLION in debt and we want to throw another $45 BIllion after it ? Forget if that money might come back around somehow, we cannot afford to keep printing money and throwing it down the toilet.

Just my $.02

See this reply in the discussion

38 Replies

Jump to latestLatest
  • Real Estate Agent · Spanish Fork, UT · Member since 2020 · 79 posts · 56 votes
    2y

    Utah had a bill passed (SB240) with limited funding (it has been plenty so far) that gives $20k to first time home buyers in a form of a 0% loan that is paid back on refinance or sale. I think it is an awesome program because of the following. 

    - Must be on a new construction home 

    - Must be under $450k (which can be hard to do on new construction here) 

    - Also protects against deflation by saying if the equity upon sale is less than $20k, only 50% of the equity needs to be paid back. Which helps keep the home buyer from being boxed out of a sale if they happen to see depreciation. 

    - Is income capped so we are helping those most in need. 

    This bill is meant to help first time home buyers while also incentivizing builders to build more starter homes rather than bigger more expensive homes. Addressing the issue on both ends is key and I believe this bill does that. 

    I think a similar approach should be taken by states with the biggest issues. Mainly those that have seen sharp price increases without incomes keeping up. I agree that the current proposal by VP Harris is not the right approach. 

  • Bruce WoodruffPro Member
    Contractor/Investor/Consultant · San Diego / Phoenix · Member since 2021 · 12k+ posts · 15k+ votes
    2y

    Beyond the very real possibilty that some overall good may come of programs such as the 'Down-payment assistance program'...there still lies at least a couple of flaws, conceptually and very real...

    1) The Gov't (we) are forcing people who cannot afford to even think about buying a home to subsidize those who are in a more fortunate position. [Similar to the Student Loan Bail-out where people who made different (and smarter) choices, are forced to give up  their hard earned money to others.]

    2) When is this country going to really realize that we are headed down a steep slope to ruin? We are $35 TRILLION in debt and we want to throw another $45 BIllion after it ? Forget if that money might come back around somehow, we cannot afford to keep printing money and throwing it down the toilet.

    Just my $.02

  • Andrew SyriosPro Member
    Moderator
    OP
    Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes
    2y
    Quote from @Masyn Grant Barney:

    Utah had a bill passed (SB240) with limited funding (it has been plenty so far) that gives $20k to first time home buyers in a form of a 0% loan that is paid back on refinance or sale. I think it is an awesome program because of the following. 

    - Must be on a new construction home 

    - Must be under $450k (which can be hard to do on new construction here) 

    - Also protects against deflation by saying if the equity upon sale is less than $20k, only 50% of the equity needs to be paid back. Which helps keep the home buyer from being boxed out of a sale if they happen to see depreciation. 

    - Is income capped so we are helping those most in need. 

    This bill is meant to help first time home buyers while also incentivizing builders to build more starter homes rather than bigger more expensive homes. Addressing the issue on both ends is key and I believe this bill does that. 

    I think a similar approach should be taken by states with the biggest issues. Mainly those that have seen sharp price increases without incomes keeping up. I agree that the current proposal by VP Harris is not the right approach. 


    For it to only be on new construction is pretty clever. This appears a way to benefit home buyers and simultaneously stimulate construction, which seems like a pretty good idea (at least as far as government subsidies go). The problem with Harris' approach is its on everything so without specifically stimulating the existing housing stock which just means it will push prices higher and ironically make housing less affordable. 

  • Andrew SyriosPro Member
    Moderator
    OP
    Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes
    2y
    Quote from @Bruce Woodruff:

    Beyond the very real possibilty that some overall good may come of programs such as the 'Down-payment assistance program'...there still lies at least a couple of flaws, conceptually and very real...

    1) The Gov't (we) are forcing people who cannot afford to even think about buying a home to subsidize those who are in a more fortunate position. [Similar to the Student Loan Bail-out where people who made different (and smarter) choices, are forced to give up  their hard earned money to others.]

    2) When is this country going to really realize that we are headed down a steep slope to ruin? We are $35 TRILLION in debt and we want to throw another $45 BIllion after it ? Forget if that money might come back around somehow, we cannot afford to keep printing money and throwing it down the toilet.

    Just my $.02


    In the full article I discuss the fiscal cliff we are heading toward (gone off and just haven't looked down yet like Yosemite Sam?) and how neither Trump nor Harris appear to even acknowledge this problem. Although I should be honest and note that Harris is worse. 

  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    2y
    Quote from @Andrew Syrios:

    Kamala Harris announced her plan for the economy, which includes many incentives and disincentives for the real estate industry. Many of her points are actually designed to stimulate the real estate industry, which could benefit investors (although cause some unintended consequences to boot). For others, we’re in the crosshairs.

    Let’s take a look at each one individually and how they’ll affect the economy, particularly the real estate industry. We’ll ignore proposals that don’t relate to real estate—for example, a “price-gouging ban” or limiting taxes on tips—and just focus on our industry.

    Helping First-Time Homebuyers

    Harris’s plan is to offer “…first-time homebuyers with $25,000 to help with the down payment on a new home.” This would be the most significant down payment assistance the government has ever offered and dwarves the $8,000 First-Time Homebuyer Tax Credit that was in place between 2008 and 2010. That also happened while we were in the middle of a deep recession and credit crunch, unlike today.

    In 2020, there were 1,782,500 first-time homebuyers in the country. Had all of them used such an incentive, that would have cost the taxpayer a cool $44.6 billion.

    Of course, not every first-time homebuyer would use it. But then again, with such an incentive in place, demand for first-time homebuyers would likely skyrocket.

    FHA loans already only require 3.5% down to purchase a home. And Fannie Mae dropped its required down payment for multifamily properties where the owner lives in one unit to just 5% last November.

    Indeed, with a 3.5% down payment, a house that costs $714,286 would conceivably have the down payment completely covered by this program. (And this ignores seller credits, which are commonly offered to homebuyers during negotiations.)

    Affording the down payment is an issue for prospective homebuyers, but not the main one. One recent survey found 40% of non-homeowners said that their inability to afford a down payment was their main obstacle. But more (46%) cited insufficient income. Especially outside expensive coastal cities with almost comically bloated housing prices, the biggest issue for homebuyers isn’t the down payment—it’s affording the monthly mortgage payments, especially with interest rates where they are.

    By throwing money at the demand side without addressing the supply side, the most likely result is just to increase the price of properties all the more, as prospective homebuyers with $25,000 in government money behind them bid up prices against each other. This will make the mortgage payments even less affordable. This program could certainly be beneficial for house hackers, but on a policy level, it’s likely throwing good money after bad.

    ---

    Continued Here: https://www.biggerpockets.com/blog/evaluating-kamala-harris-...


     This reminds me of my 8th grade class president trying to bribe people with longer study halls, a vending machine and soda fountain in the room and ice cream fridays. None of it will ever get passed and its a ploy to buy votes. Both sides do it and its actually pretty comical.

    7e investments53 Reviews
  • Nicholas L.Pro Member
    Flipper/Rehabber · Pittsburgh · Member since 2018 · 6k+ posts · 5k+ votes
    2y

    @Chris Seveney

    genuine question - is everything every politician does just a "ploy to buy votes"?  i feel like that is certainly at least partially true in some cases, but what if they also (mistakenly) believe in the policy?  

    or, to put it slightly differently, how do you separate sincere policy proposals from ploys?  or is there never any such thing as a sincere policy proposal?

  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    2y
    Quote from @Nicholas L.:

    @Chris Seveney

    genuine question - is everything every politician does just a "ploy to buy votes"?  i feel like that is certainly at least partially true in some cases, but what if they also (mistakenly) believe in the policy?  

    or, to put it slightly differently, how do you separate sincere policy proposals from ploys?  or is there never any such thing as a sincere policy proposal?


     Honestly, not getting into a political discussion on a real estate website. To me it does not matter. 

    7e investments53 Reviews
  • Nicholas L.Pro Member
    Flipper/Rehabber · Pittsburgh · Member since 2018 · 6k+ posts · 5k+ votes
    2y

    @Chris Seveney

    Fair enough.

    I agree that these won't have a meaningful impact on the whole market or bring prices down.

    So IMO they are sincere but misguided

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    2y

    AS for building 3 mil more homes that will cause price rises again in lumber and other items for the house not to mention man power  ..  we already have manpower issues at these numbers.

  • Rene HosmanPro Member
    Rental Property Investor · Denver, CO · Member since 2024 · 583 posts · 653 votes
    2y
    Quote from @Masyn Grant Barney:

    Utah had a bill passed (SB240) with limited funding (it has been plenty so far) that gives $20k to first time home buyers in a form of a 0% loan that is paid back on refinance or sale. I think it is an awesome program because of the following. 

    - Must be on a new construction home 

    - Must be under $450k (which can be hard to do on new construction here) 

    - Also protects against deflation by saying if the equity upon sale is less than $20k, only 50% of the equity needs to be paid back. Which helps keep the home buyer from being boxed out of a sale if they happen to see depreciation. 

    - Is income capped so we are helping those most in need. 

    This bill is meant to help first time home buyers while also incentivizing builders to build more starter homes rather than bigger more expensive homes. Addressing the issue on both ends is key and I believe this bill does that. 

    I think a similar approach should be taken by states with the biggest issues. Mainly those that have seen sharp price increases without incomes keeping up. I agree that the current proposal by VP Harris is not the right approach. 


     Since you're an agent in Utah - I'm curious if this Utah program has helped your clients personally? 

    I live in Colorado where I've noticed programs that are income restricted while they have great and important intentions - it's so limiting because the folks who both have a high enough income to qualify for the mortgage yet also low enough to make income qualifications are such a small small % of the population it makes it almost impossible to meet both criteria at once.

    BiggerPockets
  • Real Estate Agent · Spanish Fork, UT · Member since 2020 · 79 posts · 56 votes
    2y
    Quote from @Rene Hosman:
    Quote from @Masyn Grant Barney:

    Utah had a bill passed (SB240) with limited funding (it has been plenty so far) that gives $20k to first time home buyers in a form of a 0% loan that is paid back on refinance or sale. I think it is an awesome program because of the following. 

    - Must be on a new construction home 

    - Must be under $450k (which can be hard to do on new construction here) 

    - Also protects against deflation by saying if the equity upon sale is less than $20k, only 50% of the equity needs to be paid back. Which helps keep the home buyer from being boxed out of a sale if they happen to see depreciation. 

    - Is income capped so we are helping those most in need. 

    This bill is meant to help first time home buyers while also incentivizing builders to build more starter homes rather than bigger more expensive homes. Addressing the issue on both ends is key and I believe this bill does that. 

    I think a similar approach should be taken by states with the biggest issues. Mainly those that have seen sharp price increases without incomes keeping up. I agree that the current proposal by VP Harris is not the right approach. 


     Since you're an agent in Utah - I'm curious if this Utah program has helped your clients personally? 

    I live in Colorado where I've noticed programs that are income restricted while they have great and important intentions - it's so limiting because the folks who both have a high enough income to qualify for the mortgage yet also low enough to make income qualifications are such a small small % of the population it makes it almost impossible to meet both criteria at once.


     Yep! I have had clients benefit from it. It’s been an awesome program that I believe was correctly targeted to help those who need it the most and also boost supply. 

    Another credit union here (I believe they lend in Colorado too) has a no income limit 0% down program. Lmk if you want me to connect you to a lender that offers it. It's a 40 year amortization with no PMI. It's awesome.

  • Andrew SyriosPro Member
    Moderator
    OP
    Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes
    2y
    Quote from @Account Closed:
    Quote from @Andrew Syrios:
    Quote from @Account Closed:
    Quote from @Andrew Syrios:
    Quote from @Account Closed:
    Quote from @Andrew Syrios:
    Quote from @Bruce Woodruff:

    Beyond the very real possibilty that some overall good may come of programs such as the 'Down-payment assistance program'...there still lies at least a couple of flaws, conceptually and very real...

    1) The Gov't (we) are forcing people who cannot afford to even think about buying a home to subsidize those who are in a more fortunate position. [Similar to the Student Loan Bail-out where people who made different (and smarter) choices, are forced to give up  their hard earned money to others.]

    2) When is this country going to really realize that we are headed down a steep slope to ruin? We are $35 TRILLION in debt and we want to throw another $45 BIllion after it ? Forget if that money might come back around somehow, we cannot afford to keep printing money and throwing it down the toilet.

    Just my $.02


    In the full article I discuss the fiscal cliff we are heading toward (gone off and just haven't looked down yet like Yosemite Sam?) and how neither Trump nor Harris appear to even acknowledge this problem. Although I should be honest and note that Harris is worse. 

    The problem isn't the republicans or the democrats, it's the American people

    accepting the "buy off" for the last 50 years. We've been paid handsomely for being stupid and not running the politicians out of town on a rail. Okay, Rand Paul has spoken up, but the rest are just part of the "happy machine" to keep spending our money (while keeping a very large cut, kinda like a mafia loan shark) to give to ourselves to "make us happy". I hear the roosters and they are coming home to roost.

    Time’s up folks. Debt payment is due.

    It was shocking when Reagan had a 90 Billion dollar year. Well Biden/Harris is 2.5 Trillion which is 27 times worse. 

    Rumsfeld said there was a Trillion missing from the pentagon. That would build 2,500,000 houses at 400,000 each. Kinda makes you proud we are willing to squander that much wealth, eh? Harris/Walz says "Let's do it again".


    I think blaming the American people is a bit of a cop out in my opinion. After all, it makes sense in game theory to "get yours" even if it's bad for the country on the whole. The political structure is a mess and perhaps we need a new constitutional convention to reorient ourselves. That being said, with today's partisanship, that would be a complete trainwreck so there doesn't really seem to be a good solution. 

    Your comment: "political structure is a mess" and "a new constitutional convention"

    1. Voted in by people
    2. Consists of people.
    3. Influenced by people
    4. Designed by people
    5. Supported by people

    I guess I see your, point, the american people have nothing to do with this.


     I think there's a difference between the "people" in general and the "people in charge." I mean, no matter who we vote for, the deficit goes up. Republicans are supposed to be for fiscal responsibility but both Bush and Trump had huge deficits. And Biden and Obama had huge deficits too. So having "voted for this" seems like a weak argument when there's no alternative.

    And if you want to say third parties are an alternative, with basic game theory you can see that in a first past the post voting system, they are not. 

    Hmmm, so your position is that there is no difference between Trump and Biden/Harris in jobs creation, amount spent on war, amount spend on illegal aliens, interest rates, amount spent on failed green policies and so on? Interesting perspective and you are entitled to your opinion.

    I think most people might disagree with that and perhaps we'll see in November.

    To not take responsibility for our actions is the name of the game in this day and age. That changes abrubtly . . . pretty soon.


    Saying they both have done a bad job is not "so I'm saying" that there is no difference. Biden has been certainly been worse on spending, but Trump (and Bush) did very badly as well. 

  • Andrew SyriosPro Member
    Moderator
    OP
    Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes
    2y
    Quote from @Jay Hinrichs:

    AS for building 3 mil more homes that will cause price rises again in lumber and other items for the house not to mention man power  ..  we already have manpower issues at these numbers.


    I suspect it won't do much more than crowd out private investment given private developers are already building houses at almost the highest rate since the 2008 crash. 

  • Member since 2022 · 1k+ posts · 1k+ votes
    2y

    Olympia WA just passed an assistance program for certain minorities if they can show they have roots in this state prior to 1968. Up to $150k (or 20 percent down) no interest loan, paid back if the property is sold.  Where's the skin in the game like I had to do?  Sorry, it doesn't sit right with me.

  • Andrew SyriosPro Member
    Moderator
    OP
    Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes
    2y
    Quote from @Account Closed:
    Quote from @Andrew Syrios:
    Quote from @Account Closed:
    Quote from @Andrew Syrios:
    Quote from @Account Closed:
    Quote from @Andrew Syrios:
    Quote from @Account Closed:
    Quote from @Andrew Syrios:
    Quote from @Bruce Woodruff:

    Beyond the very real possibilty that some overall good may come of programs such as the 'Down-payment assistance program'...there still lies at least a couple of flaws, conceptually and very real...

    1) The Gov't (we) are forcing people who cannot afford to even think about buying a home to subsidize those who are in a more fortunate position. [Similar to the Student Loan Bail-out where people who made different (and smarter) choices, are forced to give up  their hard earned money to others.]

    2) When is this country going to really realize that we are headed down a steep slope to ruin? We are $35 TRILLION in debt and we want to throw another $45 BIllion after it ? Forget if that money might come back around somehow, we cannot afford to keep printing money and throwing it down the toilet.

    Just my $.02


    In the full article I discuss the fiscal cliff we are heading toward (gone off and just haven't looked down yet like Yosemite Sam?) and how neither Trump nor Harris appear to even acknowledge this problem. Although I should be honest and note that Harris is worse. 

    The problem isn't the republicans or the democrats, it's the American people

    accepting the "buy off" for the last 50 years. We've been paid handsomely for being stupid and not running the politicians out of town on a rail. Okay, Rand Paul has spoken up, but the rest are just part of the "happy machine" to keep spending our money (while keeping a very large cut, kinda like a mafia loan shark) to give to ourselves to "make us happy". I hear the roosters and they are coming home to roost.

    Time’s up folks. Debt payment is due.

    It was shocking when Reagan had a 90 Billion dollar year. Well Biden/Harris is 2.5 Trillion which is 27 times worse. 

    Rumsfeld said there was a Trillion missing from the pentagon. That would build 2,500,000 houses at 400,000 each. Kinda makes you proud we are willing to squander that much wealth, eh? Harris/Walz says "Let's do it again".


    I think blaming the American people is a bit of a cop out in my opinion. After all, it makes sense in game theory to "get yours" even if it's bad for the country on the whole. The political structure is a mess and perhaps we need a new constitutional convention to reorient ourselves. That being said, with today's partisanship, that would be a complete trainwreck so there doesn't really seem to be a good solution. 

    Your comment: "political structure is a mess" and "a new constitutional convention"

    1. Voted in by people
    2. Consists of people.
    3. Influenced by people
    4. Designed by people
    5. Supported by people

    I guess I see your, point, the american people have nothing to do with this.


     I think there's a difference between the "people" in general and the "people in charge." I mean, no matter who we vote for, the deficit goes up. Republicans are supposed to be for fiscal responsibility but both Bush and Trump had huge deficits. And Biden and Obama had huge deficits too. So having "voted for this" seems like a weak argument when there's no alternative.

    And if you want to say third parties are an alternative, with basic game theory you can see that in a first past the post voting system, they are not. 

    Hmmm, so your position is that there is no difference between Trump and Biden/Harris in jobs creation, amount spent on war, amount spend on illegal aliens, interest rates, amount spent on failed green policies and so on? Interesting perspective and you are entitled to your opinion.

    I think most people might disagree with that and perhaps we'll see in November.

    To not take responsibility for our actions is the name of the game in this day and age. That changes abrubtly . . . pretty soon.


    Saying they both have done a bad job is not "so I'm saying" that there is no difference. Biden has been certainly been worse on spending, but Trump (and Bush) did very badly as well. 

    Sorry about that. I though your post was about
    "Evaluating Kamala Harris’s Proposals For the Real Estate Industry"
    so I responded as Harris vs the others, not as Bush or others that you've brought up. For my efforts, the posts themselves got deleted, yet remain in the responses if one looks for them. 

    I like your point that for Harris, "we're in the crosshairs". I think that is the real point of her interest in real estate. She is looking for things to tax. I am not swayed by her "benevolence" by taxing us more.

    I'll end my participation with this:

    "You get the leaders you deserve".


     Huh, I don't think anything you wrote deserved to be deleted. Not my call I guess. But I would agree at least that Kamala Harris' economic proposals will be bad; for the real estate industry, the deficit and the economy in general. 

  • Andrew SyriosPro Member
    Moderator
    OP
    Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes
    2y
    Quote from @Henry T.:

    Olympia WA just passed an assistance program for certain minorities if they can show they have roots in this state prior to 1968. Up to $150k (or 20 percent down) no interest loan, paid back if the property is sold.  Where's the skin in the game like I had to do?  Sorry, it doesn't sit right with me.


    Also seems to be a pretty blatant violation of the equal protections clause, although they don't seem to care much about that anymore

  • Scott TrenchPro Member
    Rental Property Investor · Denver, CO · Member since 2014 · 2k+ posts · 6k+ votes
    2y
    Quote from @Nicholas L.:

    @Chris Seveney

    genuine question - is everything every politician does just a "ploy to buy votes"?  i feel like that is certainly at least partially true in some cases, but what if they also (mistakenly) believe in the policy?  

    or, to put it slightly differently, how do you separate sincere policy proposals from ploys?  or is there never any such thing as a sincere policy proposal?


    I think that this quote comes to mind in reading your response here: 

    "It is difficult to get a man to understand something, when his salary depends on his not understanding it." 

    Just to be equally critical of both parties, and make everyone mad, here are two examples: 

    - Imposing tariffs on China absolutely contributes to inflation in many consumer goods. 

    - Giving first time homebuyers $25,000 absolutely contributes to housing price inflation

    Getting some conservatives running for office to change their mind on the first point ain't gonna happen. Getting some liberals running for office to understand the second point is just as difficult.


  • Rental Property Investor · Manteno, IL · Member since 2009 · 2k+ posts · 2k+ votes
    2y
    Quote from @Masyn Grant Barney:

    Utah had a bill passed (SB240) with limited funding (it has been plenty so far) that gives $20k to first time home buyers in a form of a 0% loan that is paid back on refinance or sale. I think it is an awesome program because of the following. 

    - Must be on a new construction home 

    - Must be under $450k (which can be hard to do on new construction here) 

    - Also protects against deflation by saying if the equity upon sale is less than $20k, only 50% of the equity needs to be paid back. Which helps keep the home buyer from being boxed out of a sale if they happen to see depreciation. 

    - Is income capped so we are helping those most in need. 

    This bill is meant to help first time home buyers while also incentivizing builders to build more starter homes rather than bigger more expensive homes. Addressing the issue on both ends is key and I believe this bill does that. 

    I think a similar approach should be taken by states with the biggest issues. Mainly those that have seen sharp price increases without incomes keeping up. I agree that the current proposal by VP Harris is not the right approach. 


     That, to me, is the most wisely crafted way to fix the housing problem. And it doesn't really cost the taxpayers as much money as they're putting out because the principal is getting returned to the taxpayer when that buyer sells the home.

    What I really like is that its only for first time home buyers and only for new construction.  We're never going to fix this supply problem for housing unless we can juice the number of builds getting done to where its back to normal (i.e. pre boom times from 2005 to 2008).

    The federal government should do the exact same thing to stretch the money.  25k down payment assistance for first time home buyers who buy new construction homes as a no interest loan payable only upon sale or transfer (i.e. if the person dies and someone inherits, that 25k could be called due). 

    To me, that would definitely jump start new construction.  And until they do that, this problem is never going to get better.

  • Andrew SyriosPro Member
    Moderator
    OP
    Residential Real Estate Investor · Kansas City, MO · Member since 2014 · 10k+ posts · 5k+ votes
    2y
    Quote from @Scott Trench:
    Quote from @Nicholas L.:

    @Chris Seveney

    genuine question - is everything every politician does just a "ploy to buy votes"?  i feel like that is certainly at least partially true in some cases, but what if they also (mistakenly) believe in the policy?  

    or, to put it slightly differently, how do you separate sincere policy proposals from ploys?  or is there never any such thing as a sincere policy proposal?


    I think that this quote comes to mind in reading your response here: 

    "It is difficult to get a man to understand something, when his salary depends on his not understanding it." 

    Just to be equally critical of both parties, and make everyone mad, here are two examples: 

    - Imposing tariffs on China absolutely contributes to inflation in many consumer goods. 

    - Giving first time homebuyers $25,000 absolutely contributes to housing price inflation

    Getting some conservatives running for office to change their mind on the first point ain't gonna happen. Getting some liberals running for office to understand the second point is just as difficult.


    I would completely agree with both statements although I would note that I do think you can at least partially justify tariffs on Chinese goods in so far as a way to raise tax revenue particularly in lieu of increasing income taxes or what not. Especially since we have such high deficits right now. But of course, you need to be very careful about the risk of starting a trade war. 

  • Rental Property Investor · Manteno, IL · Member since 2009 · 2k+ posts · 2k+ votes
    2y
    Quote from @Andrew Syrios:
    Quote from @Scott Trench:
    Quote from @Nicholas L.:

    @Chris Seveney

    genuine question - is everything every politician does just a "ploy to buy votes"?  i feel like that is certainly at least partially true in some cases, but what if they also (mistakenly) believe in the policy?  

    or, to put it slightly differently, how do you separate sincere policy proposals from ploys?  or is there never any such thing as a sincere policy proposal?


    I think that this quote comes to mind in reading your response here: 

    "It is difficult to get a man to understand something, when his salary depends on his not understanding it." 

    Just to be equally critical of both parties, and make everyone mad, here are two examples: 

    - Imposing tariffs on China absolutely contributes to inflation in many consumer goods. 

    - Giving first time homebuyers $25,000 absolutely contributes to housing price inflation

    Getting some conservatives running for office to change their mind on the first point ain't gonna happen. Getting some liberals running for office to understand the second point is just as difficult.


    I would completely agree with both statements although I would note that I do think you can at least partially justify tariffs on Chinese goods in so far as a way to raise tax revenue particularly in lieu of increasing income taxes or what not. Especially since we have such high deficits right now. But of course, you need to be very careful about the risk of starting a trade war. 


     I agree that tariffs can be justified against certain countries like china on specific products where their govt is clearly subsidizing the manufacture of those goods and dumping the products to try to run the competition into the ground.

    That being said.  This idea that you can tariff your way into generating a bunch of income by hitting entire countries on everything just because you have a trade deficit and think you're raising money is absolutely awful.  

    Make no mistake.  Tariffs are a tax on the american people. The exporting countries aren't paying anything.  The importing business here in america is paying that tariff and then passing those costs on to the american consumer.   Those trump tariffs definitely contributed to inflation. And bigger tariffs that he's supposedly going to roll out is going to make things worse.

    And then what happens is that the other countries respond with tariffs of their own and that costs businesses here to lose revenue because now their goods are more expensive with the added tariffs in those overseas countries.

    Again, I think there is a place for tariffs.  But this idea that tariffs for every country are some magic elixir to solve everything is just silly.  The other thing I don't understand is this idea that somehow we need more jobs here in america as if there is some huge unemployment problem.  Last I checked, our unemployment has been ridiculously low and anybody that wanted a job could get one. In fact, businesses inability to find workers is what also contributed to inflation - they had to raise salaries to fill their openings.

    I'd say right now we're running just about right.  Good jobs are out there.  But you don't have such a huge shortage of employees that salaries are shooting up and creating an inflationary problem.

  • Severna Park, MD · Member since 2013 · 7k+ posts · 7k+ votes
    2y

    The federal government cant solve the problem . The problem lies with local jurisdictions . You have areas where property taxes are going up too fast based on the over valuation of properties  ( tax on unrealized gain ) . Fees for new construction , between capitol connections , impact fees , environmental fees , engineering fees , etc  you CANT build AFFORDABLE housing .   I didnt even mention land costs , and the cost of the construction itself , and commissions . 

    All that both sides are saying about housing is a ploy for votes .  

    There is plenty of affordable housing available right now , the problem is that no one wants to live in the cities where its located . Due to crime and poor schools .  Fix the crime and education problem and the free market will solve the rest .

    " I am with the government and we are here to help "        Not 

  • Bruce WoodruffPro Member
    Contractor/Investor/Consultant · San Diego / Phoenix · Member since 2021 · 12k+ posts · 15k+ votes
    2y
    Quote from @Matthew Paul:

    There is plenty of affordable housing available right now , the problem is that no one wants to live in the cities where its located . Due to crime and poor schools .  Fix the crime and education problem and the free market will solve the rest .

    True that. Not only in cities where it's located, but even more specifically in areas within cities where it's located. I don't know how we fix crime and schools without getting the Goobermint involved, which rarely works....

    Unless we gave tax breaks and incentives to builders and investors like us that would encourage us to take bigger chances and go develop some of these down-and-out areas......it's worked before....


  • Rental Property Investor · Manteno, IL · Member since 2009 · 2k+ posts · 2k+ votes
    2y
    Quote from @Matthew Paul:

    The federal government cant solve the problem . The problem lies with local jurisdictions . You have areas where property taxes are going up too fast based on the over valuation of properties  ( tax on unrealized gain ) . Fees for new construction , between capitol connections , impact fees , environmental fees , engineering fees , etc  you CANT build AFFORDABLE housing .   I didnt even mention land costs , and the cost of the construction itself , and commissions . 

    All that both sides are saying about housing is a ploy for votes .  

    There is plenty of affordable housing available right now , the problem is that no one wants to live in the cities where its located . Due to crime and poor schools .  Fix the crime and education problem and the free market will solve the rest .

    " I am with the government and we are here to help "        Not 


     I disagree completely. The govt has to be the one to fix this problem.  We have a supply issue because banks stopped lending to builders other than one or two at a time for spec builds after the bust in 08 so they were limited in being able to grow the supply.  And now the margins are too tight for people to do it. 

    The govt absolutely has to help nudge new construction or this problem is never going to be corrected.  We simply don't have enough homes for the number of people who want them.  And the pace of homes being built is too far below what we need to keep pace let alone catch up to where its only going to get worse.

    And that is going to drive up inflation big time. Which then leads to the fed keeping rates artificially higher than they should be.

  • Severna Park, MD · Member since 2013 · 7k+ posts · 7k+ votes
    2y
    Quote from @Mike H.:
    Quote from @Matthew Paul:

    The federal government cant solve the problem . The problem lies with local jurisdictions . You have areas where property taxes are going up too fast based on the over valuation of properties  ( tax on unrealized gain ) . Fees for new construction , between capitol connections , impact fees , environmental fees , engineering fees , etc  you CANT build AFFORDABLE housing .   I didnt even mention land costs , and the cost of the construction itself , and commissions . 

    All that both sides are saying about housing is a ploy for votes .  

    There is plenty of affordable housing available right now , the problem is that no one wants to live in the cities where its located . Due to crime and poor schools .  Fix the crime and education problem and the free market will solve the rest .

    " I am with the government and we are here to help "        Not 


     I disagree completely. The govt has to be the one to fix this problem.  We have a supply issue because banks stopped lending to builders other than one or two at a time for spec builds after the bust in 08 so they were limited in being able to grow the supply.  And now the margins are too tight for people to do it. 

    The govt absolutely has to help nudge new construction or this problem is never going to be corrected.  We simply don't have enough homes for the number of people who want them.  And the pace of homes being built is too far below what we need to keep pace let alone catch up to where its only going to get worse.

    And that is going to drive up inflation big time. Which then leads to the fed keeping rates artificially higher than they should be.


     I have been waiting for a permit from the " government " for a sewer connection since June . Its an existing house with septic , and the sewer stack is already there . Its digging in a straight line 85 ft .  Its a $7000 job , with $21,000 of fees , permits and engineering . The job will take a day and a half .    

    Sure we need more government help 

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    2y
    Quote from @Mike H.:
    Quote from @Matthew Paul:

    The federal government cant solve the problem . The problem lies with local jurisdictions . You have areas where property taxes are going up too fast based on the over valuation of properties  ( tax on unrealized gain ) . Fees for new construction , between capitol connections , impact fees , environmental fees , engineering fees , etc  you CANT build AFFORDABLE housing .   I didnt even mention land costs , and the cost of the construction itself , and commissions . 

    All that both sides are saying about housing is a ploy for votes .  

    There is plenty of affordable housing available right now , the problem is that no one wants to live in the cities where its located . Due to crime and poor schools .  Fix the crime and education problem and the free market will solve the rest .

    " I am with the government and we are here to help "        Not 


     I disagree completely. The govt has to be the one to fix this problem.  We have a supply issue because banks stopped lending to builders other than one or two at a time for spec builds after the bust in 08 so they were limited in being able to grow the supply.  And now the margins are too tight for people to do it. 

    The govt absolutely has to help nudge new construction or this problem is never going to be corrected.  We simply don't have enough homes for the number of people who want them.  And the pace of homes being built is too far below what we need to keep pace let alone catch up to where its only going to get worse.

    And that is going to drive up inflation big time. Which then leads to the fed keeping rates artificially higher than they should be.

    Mike agreed about spec lending at a few at a time but that stopped at least in most markets about 2014 or 2015.. I am a small time builder and my bank will give me 9 specs in Oregon and 4 or 5 in Charleston if I could find the lots which I cant.  

    I can see mid west still having issues with spec lending .  However I really agree with Mathew on this.. there are thousands of houses in every big city in the mid west and rust belt. these are less than replacement costs.. I mean Indy has 3k vacant s.. Baltimore no telling how many but its got to be 10k  and philly same way chicago every city.. the issue is clearly as Mathew states .  schools and crime.. And all that inventory has just been sold off to investors for rental purposes.. I know I have funded probably 5k of them over the last 20 years for investors. Clean up the cities is something the fed can do.. Thats your starter housing.  
    Out here in the west its simply impossible to build anything that will sell for much less than 500k when your lots start at 100k to 200k each then permits are 30 to 75k each.. then you build the home thats the reality.. only way fed helps there is to buy private land and subsidize or turn federal lands into developments. the one market that would work is VEGAS as its surrounded by federal land.

    And from what I see in west coast the regional builders are back to pumping out spec homes as fast as they were pre GFC.. I have 3 deals going in Loudoun county VA that national builders are buying our lots and when I was there going through existing developments its was full speed ahead Toll Brothers on one project probably had 40 up and running some i am sure are presold.. But you cant get any velocity if you dont spec build . So I agree smaller banks hamstrung the small builders by only allow 2 or 3 specs.. No way they can scale at that pace..

    And for sure small tertiary markets in the mid west new builds are just not really happening.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.