Lender · Mesa, AZ · Member since 2026 · 9 posts · 3 votes
I am a mortgage broker and I have an Arizona client who is looking to finance a PadSplit. Does anyone have experience with these kinds of properties? Any lenders that are PadSplit friendly?
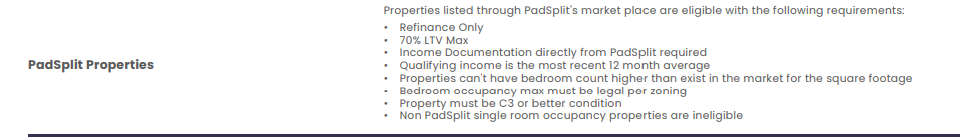
Following up with specifics. Looking for DSCR lenders that will close on a turnkey rent-by-the-room PadSplit house in the Phoenix metro (Mesa, Glendale, north Phoenix), 9 to 11 rooms, purchase around $500-575K, 25% down from a 1031 exchange. Specifically: (1) do you treat it as a standard rental, short-term rental or its own category? (2) how do you calculate rent, from the appraiser, from actual PadSplit income, or both? (3) do you count rooms or legal bedrooms? (4) any problem closing before the rehab or conversion is finished? Thanks in advance.
This is definitely an issue but for whatever reason even if the appraisal fully clears any "functional obsolescence" or quantifies it as a minimal number to revert (like $1,000) many secondary market loan investors will still not touch it.
Rent by the room is common enough in Arizona and Texas now, especially near the bases, that the income itself isn't the problem. In our experience the per room income can be used as third party rent as long as the platform statements are provided and they line up with the bank statements, with the final call still sitting with the underwriter on conditions.
Is the house already operating as a PadSplit with a trailing history, or is this a conversion the buyer finishes after closing?
Good questions — PadSplit is its own animal with most DSCR lenders, not a standard rental and not an STR. A few things that matter: (1) Rent: most lenders start with the appraiser's market rent for the property, and some will credit actual PadSplit income if the platform statements reconcile with bank deposits — underwriter has the final call, so get that answer in writing before you commit. (2) Rooms vs bedrooms: legal bedrooms count; extra rooms only count if zoning, permits, and the appraisal support the rent-by-room use. (3) Closing before the conversion is finished is the hard part — most DSCR lenders want it complete and operating, or at minimum permitted and nearly done; a half-finished conversion usually means a bridge/hard-money close first, then refi into DSCR once it's leased up. With 25% down from a 1031 you're in the right LTV range — the deal-killer here is almost always the rent math, not the down payment.
Hi Joe - PadSplit is a split underwriting world: many DSCR lenders will only use a market-rent appraisal form and will not credit actual by-the-room income, while a smaller set of portfolio and specialty DSCR lenders will look at documented room leases and collection history, usually with higher DSCR and reserve requirements because of the occupancy model. The 1031 funds for the 25% down and the house already being stabilized both help, as long as the room income is well documented. I am Marc with Royal Partners - if you want, DM me the property's room count, actual monthly collections, and target loan amount and I will give you straight numbers on which route pencils.
There are some Padsplit DSCR programs. Loan programs usually take a bit to catch up with the market so these seem to be newer programs. Arizona is one of the fewer states where it seems that an NMLS license is needed to originate the loan even if it's a DSCR or business purpose loan (not a conventional owner occupy loan), so that will probably factor in for what options materialize. There are DSCR loan programs that will use the actual rent by the room leases to calculate the DSCR ratio if the leases are six months are longer from when the lease began and then the lease can go month to month after 6 months. There are additional details around this.
The DSCR program will require an appraisal where a rent schedule will be done. The program will want the appraiser to mark the property "as is" so that the work has been completed and the property is in habitable condition with no additional rehab work needed. Usually appraisers won't count unpermitted work towards the value of the property. The zoning will matter as well.
Good question, Joe — and the trailing-history point others raised is the one I would watch closest. I rent by the room here in San Antonio on membership-fee agreements, not through PadSplit, and what I have learned is that the income only counts when the agreements and the payment tracking are consistent enough to show. Is your client's house already operating with that kind of documented history, or is this a conversion they would finish after closing? That answer seems to change the whole conversation with a lender.
Joe, interesting one. With a PadSplit deal coming out of a 1031, I'd want the tax and lending sides talking to each other before closing.
I wouldn't automatically treat the property as a traditional LTR or an STR for tax purposes. The actual rental periods and services provided can affect how the activity is classified, so I'd want to look at the PadSplit agreement and how the property will actually be operated.
I'd also make sure the 1031 is already properly structured before the relinquished property closes. The exchange timing and replacement-property requirements matter, and you don't want the financing structure to accidentally create an issue with the exchange.
From the appraisal side, I'd want the lender to be clear on whether they're underwriting the property based on traditional rental comps, actual PadSplit income, or some combination. That's probably where I'd want the CPA, lender, appraiser, and 1031 intermediary coordinated.
Hi @Joe Valenti , I'm also in the business, not a broker, a lender.
From what I've seen, most private lenders don't do pad splits/rent by room, but they will do a DSCR loan based on the market income. Usually the income for the entire SFR is less than what you can get from doing rent by room. I've seen 80% for rate and term refi and 75% for a cash out refi.
Lenders will want to see the place is rent ready and not under construction before doing a DSCR loan. If you use the same lender for both transactions, first one a fix and flip purchase, and the second a DSCR cash-out refi, they should be able to work with you and minimize the fees.
The issue I have not seen addressed is the appraisal on these deals. There is functional obsolescence to a 8 bedroom/ 2 bath home in a 4/2 neighborhood. The vast majoirty of the buyer market does not want an 8/2 so the demand for that property if needed to liquidate is much less (or, there is a cost to revert back to 4/2). Are you guys not seeing this as an issue? I know as someone who lends money out of my own balance sheet this would be an issue for me.
This is definitely an issue but for whatever reason even if the appraisal fully clears any "functional obsolescence" or quantifies it as a minimal number to revert (like $1,000) many secondary market loan investors will still not touch it.
Right, I never see that part mentioned on these PadSplit conversations. But, it should be covered as exiting or even refianancing a property that was converted into a PadSplit might not be easy no matter how the income is calculated.