I live in San Diego, CA and want to buy my first rental property but I don't have a primary residence yet. Does renting an apartment so I I can use my savings out of state sound like a good idea? Or would you dig for a house hack untill a decent deal comes up?
OOS equates to 80% LTV (possibly 75% LTV). FHA in San Diego equates to as high as 96.5% LTV. This implies that without closing costs you can purchase a home local that is 5.5 times as expensive as the OOS property (assuming you can qualify for the loan).
Why is this important? If the purchase appreciates 10% (over whatever time span), the 96.5% LTV will have returned 285% while the 80% LTV will have returned 50% from the property appreciation.
Historically San Diego has outstanding appreciation. This implies not only will the higher LTV produces a higher return, but it is also extremely likely that the San Diego purchase will have a higher long term appreciation rate. This implies that the San Diego purchase is likely to achieve that 10% appreciation much faster than cheaper markets. We have quite a few local properties. Every one of them, regardless if they were purchased with horrendous timing at full retail, has appreciated at least $1K/month over the holding period. We have 2 properties that have appreciated over $4K/month over the holding period. This implies if you purchase a local property to live in, there is a very good chance over the long term that you experience at least $1k/month appreciation over the hold period. Note there have been a few depreciating cycles (worse being the Great Recession), so my statement is very likely in the long term, but may not be true in the short term. Two of our purchases depreciated close to 20% after purchase (and both were purchased at retail), but both are up over $1K/month over the hold period now (1993 3/2/2 SFH purchase in Claremont for $167K, worth ~$700K today; 2003 4/3/3 SFH purchased for $741K, worth ~1.25M today).
OOS almost necessitates use of a PM. I high priced markets like San Diego true PM fees (after including all costs) could be 8%, but in lower cost markets you should factor in a cost of 10% (when including for all costs).
What do you get in the OOS market? Not a cheaper entry cost in the case of an OO local property. Not likely same return from appreciation. Not likely cheaper rental costs when factored as a percentage of rents.
Note because the local property is not a rental there is no cash flow comparison. If the local property was a rental, the initial cash flow would be better in many markets. San Diego's cash flow is slower to be realized, but for long term holds will out produce the cheaper markets (it is simple math that the higher appreciating rent with both areas experiencing similar other cost increases will always eventually produce the better cash flow).
If you want a local rental property, you could consider a house hack option. I typically suggest a detached duplex if going this route. There are various reasons why this is my recommendation that I will not cover unless you express interest.
Good luck
@Vidal Preciado I come from the mindset of doing both. What are your long terms goals? Do you plan on staying in SD? I have one clients who purchased the first half of last year are refinancing with a lot more equity than expected. Some are purchasing again this year.
@Dan Heuschele Thank you Dan! This is really helpful information. I was planning to invest OOS because I want to get more out of the money I currently have but I had not considered the long tear return with the appreciation included. I was focusing on initial cash flow but I do know San Diego has a great history of appreciation compared to many places.
@Kenneth Donaghy
Thank you for the response Kenneth! My long term goal simply put, is to be a buy and hold investor. My next purchase will be my first and I do plan to stay in San Diego long term. My thinking was if I can purchase a cash flowing property out of state first it might help me increase my savings quicker to purchase locally with a larger down payment..
@Vidal Preciado Price appreciation is a combination of stupidity and desirability....every time I go to Miami Fl everyone is driving Bentley's...every time I go to San Diego, everyone is driving a Honda civic and living off the HELOC they pulled on their primary...how does this make sense...don't get me wrong, I'll hang at Balboa Park any day, but the desirability of the location is questionable...nice for vacation, but how long will prices rise....and appreciation is super location specific across asset classes and property types....it certainly does not happen on a macro level.
Contrary to @Dan H. comments, San Diego really is not appreciating steadily...as an example:
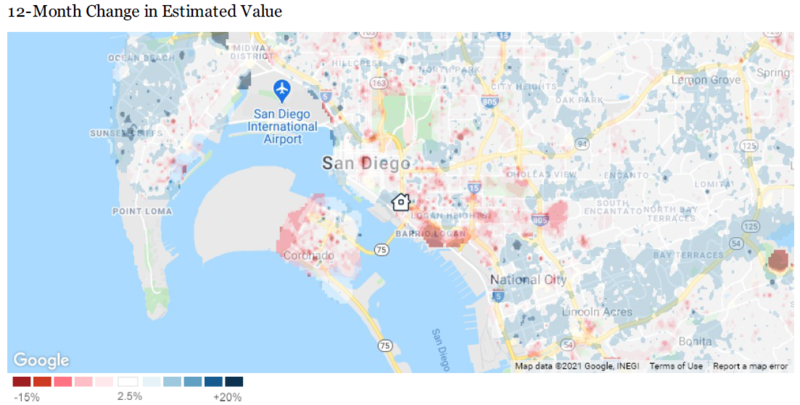
What you are seeing in locations like San Diego and LA is growth driven by poor judgment...only 20% of the population can actually afford to live in the city.
The #1 determinant of what you can buy is how much money you have...by the time you save enough cash to buy a crap SFR in San Diego your 10-unit in Central Ohio you paid the same price for would have stabilized... rents would have increased...your debt would be paid down...and the equity could serve as your way into your next 10-unit...would you rather have a ****** bungalow 5 miles from the beach or retirement income?
Odds are high that you will seek a more reasonable place to live in Colorado, Utah, New Mexico, or Arizona over being a lifetime renter in San Diego, anyway...
@Vidal Preciado Price appreciation is a combination of stupidity and desirability....every time I go to Miami Fl everyone is driving Bentley's...every time I go to San Diego, everyone is driving a Honda civic and living off the HELOC they pulled on their primary...how does this make sense...don't get me wrong, I'll hang at Balboa Park any day, but the desirability of the location is questionable...nice for vacation, but how long will prices rise....and appreciation is super location specific across asset classes and property types....it certainly does not happen on a macro level.
Contrary to @Dan H. comments, San Diego really is not appreciating steadily...as an example:
What you are seeing in locations like San Diego and LA is growth driven by poor judgment...only 20% of the population can actually afford to live in the city.
The #1 determinant of what you can buy is how much money you have...by the time you save enough cash to buy a crap SFR in San Diego your 10-unit in Central Ohio you paid the same price for would have stabilized... rents would have increased...your debt would be paid down...and the equity could serve as your way into your next 10-unit...would you rather have a ****** bungalow 5 miles from the beach or retirement income?
Odds are high that you will seek a more reasonable place to live in Colorado, Utah, New Mexico, or Arizona over being a lifetime renter in San Diego, anyway...
The red parts are probably where the forest fires were
@Vidal Preciado @Dan Heuschele
What Dan said...for your first property, going the house hacking route with as little as 3.5% down payment on something such as a duplex in San Diego would make your money go a lot further than purchasing an investment in a high cap rate market.
@Vidal Preciado
Unless you have trustworthy boots on the ground in an out-of-state market already (broker, PM, inspector, rehab contractor, etc.), I'd at least look into the 3.5% down FHA loan on a house hack opportunity in San Diego County.
Assuming you have a solid credit score, you will get in at a record low 30-year fixed rate. Not sure of the exact FHA rules on pre-paying the PMI at closing, but this could be an option for you as well.
Let a little time go buy. Maybe fix up the property some to increase market rent and appraisal value. Then look into getting a HELOC on this property. Many HELOC products come with a promotional 1-year to 3-year low fixed rate option right now (turns variable rate after that timeframe on any remaining balance). Rates should be low for the next few years. Even the Fed has gone on record in 2020 stating this.
Use those HELOC funds to make that down payment on an out-of-state property. By then, you should have your out-of-state team on board in one or two solid markets.
Nothing against out-of-state turnkey providers, as I have used one before and had favorable results, but you might find yourself on a waitlist in the markets worth investing in.
Good luck!
I'm actually in a very similar situation. It feels like that we're hitting the ceiling slowly in San Diego appreciation-wise. Investing in San Diego doesn't seem to make a lot of sense at the moment looking at basic metrics. I hear a lot of people doing something similar where they invest in cash-flowing assets out of state and renting in San Diego and California in general as from rent to value ratio it makes more sense.
@Vidal Preciado Price appreciation is a combination of stupidity and desirability....every time I go to Miami Fl everyone is driving Bentley's...every time I go to San Diego, everyone is driving a Honda civic and living off the HELOC they pulled on their primary...how does this make sense...don't get me wrong, I'll hang at Balboa Park any day, but the desirability of the location is questionable...nice for vacation, but how long will prices rise....and appreciation is super location specific across asset classes and property types....it certainly does not happen on a macro level.
Contrary to @Dan H. comments, San Diego really is not appreciating steadily...as an example:
What you are seeing in locations like San Diego and LA is growth driven by poor judgment...only 20% of the population can actually afford to live in the city.
The #1 determinant of what you can buy is how much money you have...by the time you save enough cash to buy a crap SFR in San Diego your 10-unit in Central Ohio you paid the same price for would have stabilized... rents would have increased...your debt would be paid down...and the equity could serve as your way into your next 10-unit...would you rather have a ****** bungalow 5 miles from the beach or retirement income?
Odds are high that you will seek a more reasonable place to live in Colorado, Utah, New Mexico, or Arizona over being a lifetime renter in San Diego, anyway...
There is so many things factually incorrect in Brandon’s post.
>Contrary to @Dan Heuschele comments, San Diego really is not appreciating steadily...as an example:
I do not know what Brandon considers long term, but 12 months is not what I consider long term buy n hold. It is an example of my statement of it may not be true in the short term (read my post). Long term, there is no location in San Diego county that has not appreciated faster than the appreciation rate.
>The #1 determinant of what you can buy is how much money you have...by the time you save enough cash to buy a crap SFR in San Diego your 10-unit in Central Ohio you paid the same price for would have stabilized... rents would have increased...your debt would be paid down...and the equity could serve as your way into your next 10-unit...would you rather have a ****** bungalow 5 miles from the beach or retirement income?
Some of this was already addressed in my post. At 96.5% LTV OO in San Diego would allow the same down payment to purchase 7 times the value of an OOS purchase at 75% LTV.
The point about appreciation is laughable and I’m not sure if he is serious. neighborhoodscout has Cleveland appreciation as a 1 (the lowest score, terrible) for this century at 15.64%. It has San Diego appreciation as a 10 (the highest score, great) at 159.62%. Basically San Diego for this century has had 10 times the appreciation of Cleveland. More importantly, Cleveland appreciation rate is significantly below the inflation rate which implies in inflation adjusted dollars there is a negative inflation rate. San Diego’s appreciation far exceeds the appreciation rate. Columbus does a little better with a 4 and 59.03% (2.26% annual which just barely beats the inflation rate which is over 2%). San Diego appreciation rate for this century is 3 times the appreciation rate of Ohio’s best appreciating large city.
>Odds are high that you will seek a more reasonable place to live in Colorado, Utah, New Mexico, or Arizona over being a lifetime renter in San Diego, anyway...
The OP is proposing buying in San Diego or buying OOS and renting in San Diego. Your comment is correct that he should not rent in San Diego. He should buy here. The OP question is phrased such as he apparently has already chosen to live in San Diego. My view is people who want to leave coastal Ca, is good riddance. My biggest issue in San Diego is the crowds.
Does renting an apartment so I I can use my savings out of state sound like a good idea?
If you have decided your strategy as out of state investing then saving should be #1 priority. If that means renting, eating out less and networking as much as possible on BP.
Or would you dig for a house hack untill a decent deal comes up?
I would definitely explore a house hack but reading about the investors in San Diego, its definitely hard to find a rental property. I started out of state investing last year and explored the Cleveland and Memphis property. Let me know if you want to connect and talk about the purchase process on these.
@Dan Heuschele
I think you bring some good value to this discussion on the appreciation factor of a coastal market like San Diego. Should you solely plan on appreciation to make your investment decision, probably not.
But, I truly believe that anybody that plans to live in San Diego for the long term will be deeply disappointed in themselves if they don’t get some of their capital invested in San Diego real estate especially if it can be done as way of a house hack.
I certainly will not look back a decade from now and wish I had purchased more real estate in a low cost of living Midwest town over the chance of buying into a great neighborhood in San Diego, especially with having the benefit of local knowledge. For example, I've experienced over 3.5x my original 20% down payment in appreciation alone on a San Diego SFR since 2014. Even if there is a 10% correction before I'd sell some day say in a decade from now, I will still be multiple six figures ahead of the cashflow generated on a B-class 10-unit property in the Midwest over that same timeframe with tax benefits aside. When you take that big chunk of dead equity in that San Diego SFR and put it to work on generating more positive cashflowing assets, you get the best of both worlds.
I do own rental properties in the Midwest to be able to make this comparison, and those properties serve a much different purpose in the wealth building game plan.
You need to do what is best for you based on your own goals in your own strategy I would caution you from asking other people their opinions until you have a clearly defined goal and strategy of your own
Remember that their information could actually put you in a worse position because they're giving you their goals and their strategy based on what they would do not based on what's right for you always be careful of asking other people their opinion
First thing I would do as others in here have stated is figure out "WHY" you are doing this. Once you know that and you know your end goal then you work backwards. The goal has to have a finite destination and time limit on it.
For example you may say your goal is 20 houses in 20 years (paid off) earning $20,000 per month.. (20,20,20 goal).
Now you know where you're going and the timeframe for this to happen. From here you can build out your strategy, for example here you would want to have the 20 properties purchased the first 10 years so that they can use the final 10 years to pay themselves off. This means that you have to buy 2 properties per year which means you have to close on a property every 6 months which means that you have to find a property in 3 months to have it on the market and rented the following 3 months.
And the properties need to have a final cashflow of $1,000 per month after all expenses are paid. This will dictate where you purchase and look for properties based on that number alone.
My point is that you always start with the end in mind and work it backwards, this creates the strategy (Buy and hold, flip, Wholesale, Notes) which will be driven by the tactic (SFR, MFR, Mobile homes, Short term rental etc)
I always coach people and explain that the property is actually the last piece of the puzzle not the first.
Hope this helps
@Dan H. Columbus, not Cleveland. Nothing personal, but neighborhood scout is about as bunk as zillow...I don't condone investing in Cleveland...
I think the root of the question is barrier to entry...I don't doubt there is incredible long-term appreciation in San Diego, but buying at $900/ft. is impossible for most people...trust me, I have my eye on Bird Rock. Every time I go to Mission Bay there are always a bunch of hillbillies walking around with an open case of Natural Light banking off the fact the oceanside property they bought in the 80's for $200k is now worth $4m. That's incredible.
In reality, I think making assumptions on "market prices" is misleading...sourcing deals off market at 50% ARV in any market creates wealth. And I'm always a fan of investing where you live if you can swing it.
@Eric Schultz I'd wager on that...I recently bought a C-class 10-unit at $26k/unit...$6k reno per unit...rents at $650/unit almost entirely fixed income folks that will die in their unit, 15% operating expenses all day long with $180k loan balance and a $450k appraisal...and I have 2 more in the queue...and can do 1 of these deals a year. Call me in 10-years and we'll have a beer over it ;)
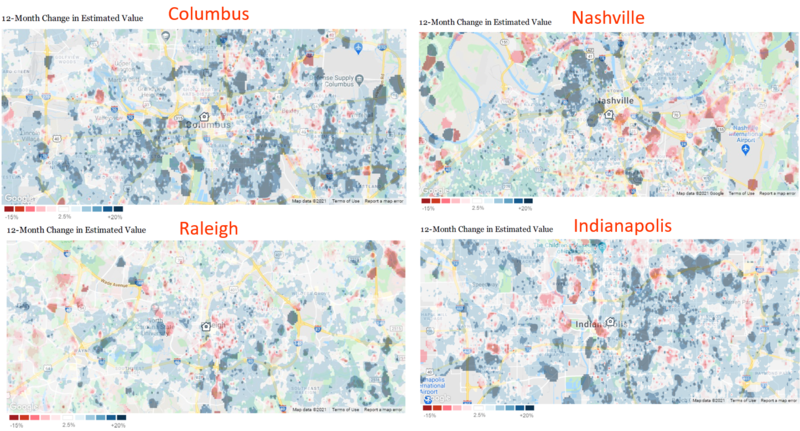
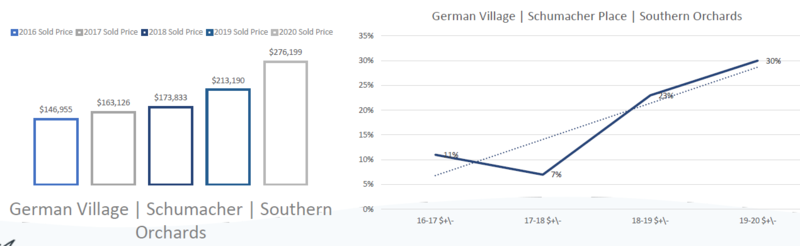
This is common across Columbus...it's ok, lots of folks have a misconception about the Midwest, but this is happening in places other than Columbus...if California could keep pace with thus type appreciation the median purchase price would be $30m..
Your looking at two good years and 2 mediocre years by San Diego standards; which is better than the one year you initially referenced. As a long term buy and hold, I look at sustained appreciation. With those 4 years you reference, Columbus has a 2.26% appreciation rate for this century. Look at Neighborhood Scout for the appreciation of San Diego versus Columbus. San Diego appreciation is in a different league for long term buy and hold. Neighborhood scout shows San Diego as a 10 for both this century and for the last decade. Columbus is good for Ohio (9 for the state) but is a 4 for nation for this century.
I can find many cities to beat the best city on a short period as that means little to a long term buy n hold investor.
I have, in the past looked, at rent default rates and Columbus and Cleveland were significantly higher than San Diego. The Columbus vacancy rate is around 25% higher than San Diego (and Cleveland is significantly worse than Columbus).
If you were making the case based on initial cash flow there could be a decent case (for long term buy n hold, I care less about the initial cash flow than I care about the cash flow over the expect hold period). Or making the case for cost of entry for an non-OO investor in each location (the OP was OO in San Diego).
However, you are trying to compare the appreciation rates of Ohio to San Diego (San Diego appreciation ranked by Neighborhood Scout as a 10 in the nation and most people are aware of its appreciation history) is such that I thought maybe your post was in jest. Then you try to double down using a short period of time that discounts that for this century Columbus' appreciation rate barely is higher than the inflation rate. The reality of Columbus long term appreciation is that it barely exceeds the inflation rate for this century (but that barely beats the inflation rate is good for Ohio cities).
I believe investors can succeed in virtually all RE markets. I am not intending to indicate that an RE investor cannot succeed in Columbus (I believe they can). What I am indicating is that historically San Diego's long term appreciation is far superior to Columbus' long term appreciation.
The best investment that you have is ALWAYS ALWAYS your primary residence no matter where it is. If you never able to grow in your local market never expect OOS to be successful. OOS investments are twice harder than primary. There're many ways to make number works for local property no matter where you live. Especially in low-interest rate and high appreciation like today, investing at primary first actually easier.
If you've been successful in house hacking in CA, OH/AL/WI/TX OOS is piece of cake.
I agree that house hacking is the best way to get into real estate. It teaches you the skills you need to invest out of state. A lot of investors that I talk to are past the point in their lives where they want to house hack though. This is why they choose to invest in other markets like Columbus, Ohio
In our area 21 years ago Remington, a lady rent 20 big houses with 5 rooms for $2k each houses. She then subleases each room for 1k ... just saying a simple approach to generate income, not saying someone shall do that, but it's possible. It's similar to that Airbnb arbitrager.
Other than that, BRRRR in a highly appreciating market every 2 years but use it as a primary residence is also making a large income.
Also offering folks to move from sunny-best-location-in-the-US San Diego to snowbelt Ohio is not really that enticing for some, except if the offer is moving to Hawaii or Cancun :) ha ha
A house hack is THE real estate strategy IMO. Everything else is a distant second.
@Vidal Preciado - I am going thru the same thing here (on Oahu). The cost of homes are so expensive. Of course I would love to house hack but those are hard to find and would definitely be over $1M (at least). I guess I need to figure out my end goal and work backward like @Steve Rozenberg suggested. Good Luck! and keep your fingers crossed for me!
If you can do a house hack first, it should free up your monthly rent to slowly save for an investment property out of state in a market like Columbus, OH. But I know it is not easy to find a good house hack in San Diego. You'll most likely need to rent out the bedrooms to break even on mortgage. @Jack Landry is a local to San Diego, you should connect to brainstorm.