Investor · Salt Lake City, UT · Member since 2015 · 56 posts · 25 votes
I have 10 existing loans with only one being a Jumbo on my current primary residence. The others are on investment properties (6 fourplexes, one duplex, a single family rental and a STR vacation property).
In speaking with a new, to me, mortgage broker, he was concerned that I could not get a conforming loan because of the existing 10 loans I already have even if I decided to put over 50% down to get under the 726.2k limit. This would be for a new primary residence for me -- owner occupied, of course.
It was my understanding, from others, that the 10 loan limit only applies if the property is an investment property rather than an owner occupied property.
Two say 10 is the max and three say there is not max, because it is owner occupied, which was my understanding. Thanks, @Jay Hurst for providing the citation.
This won't really apply since I will most likely get a jumbo loan, so conforming rules won't apply.
If there is no NMLS number, they are just guessing....
Lender · Saddle Brook, NJ · Member since 2023 · 431 posts · 231 votes
3y
As far as I'm concerned, the most amount of conventional loans is 10. That being said, if any of those loans are not conventional loans, you should be fine.
Also, if you ever run into a mortgage professional that won't explain things to you, ditch them and find another.
I have 10 existing loans with only one being a Jumbo on my current primary residence. The others are on investment properties (6 fourplexes, one duplex, a single family rental and a STR vacation property).
In speaking with a new, to me, mortgage broker, he was concerned that I could not get a conforming loan because of the existing 10 loans I already have even if I decided to put over 50% down to get under the 726.2k limit. This would be for a new primary residence for me -- owner occupied, of course.
It was my understanding, from others, that the 10 loan limit only applies if the property is an investment property rather than an owner occupied property.
Please help me understand the rules. Thanks!
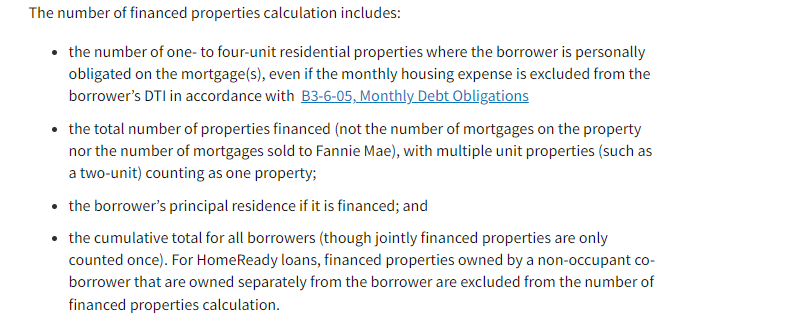
and to add for others benefit, if you are personally obligated on a loan the is vested in a LLC, that will still be counted as one of your 10. Lot of DSCR only lenders will tell you that you if in a LLC it does not count, but that is incorrect.https://selling-guide.fanniemae.com/Selling-Guide/Originatio...
Lender · Sacramento, CA · Member since 2009 · 1k+ posts · 277 votes
3y
@Doug Quist..find yourself another broker. If you're purchasing a new primary residence, there is no number of financed properties or properties owned free/clear. It might be they are new, confused, or a lender overlay. But straight Fannie/Freddie guides do not have a number of financed properties limit if you are purchasing a primary residence.
What @Jay Hurst and @Jared Rine said. The Fannie Mae Conventional 10 property limit does NOT apply to a primary residence. Find another LO who knows what they are doing :)
Rental Property Investor · Orange County, CA · Member since 2016 · 740 posts · 529 votes
3y
10 conventional loans per person. No exceptions and includes your primary. The best trick is to get NON conventional loans when rates are lower, and Conventional loans when rates go up. When/If rates drop- do a refi into non conv loans to open up spots. If you are married, your spouse can get 10 in their name too!
Investor · Salt Lake City, UT · Member since 2015 · 56 posts · 25 votes
3y
Two say 10 is the max and three say there is not max, because it is owner occupied, which was my understanding. Thanks, @Jay Hurst for providing the citation.
This won't really apply since I will most likely get a jumbo loan, so conforming rules won't apply.
Two say 10 is the max and three say there is not max, because it is owner occupied, which was my understanding. Thanks, @Jay Hurst for providing the citation.
This won't really apply since I will most likely get a jumbo loan, so conforming rules won't apply.
If there is no NMLS number, they are just guessing....
Two say 10 is the max and three say there is not max, because it is owner occupied, which was my understanding. Thanks, @Jay Hurst for providing the citation.
This won't really apply since I will most likely get a jumbo loan, so conforming rules won't apply.
and make sure your LO understands the jumbo product they are selling you. Jumbo products are of course not conventional therefore they make up their own rules and each product can and will be different. Some of the best priced will not allow more then 4 financed properties with the primary counting as one of those 4.
I have 10 existing loans with only one being a Jumbo on my current primary residence. The others are on investment properties (6 fourplexes, one duplex, a single family rental and a STR vacation property).
In speaking with a new, to me, mortgage broker, he was concerned that I could not get a conforming loan because of the existing 10 loans I already have even if I decided to put over 50% down to get under the 726.2k limit. This would be for a new primary residence for me -- owner occupied, of course.
It was my understanding, from others, that the 10 loan limit only applies if the property is an investment property rather than an owner occupied property.
Please help me understand the rules. Thanks!
Why are you wasting your time with a mortgage broker?
At this point you should be laser focused on portfolio lenders, and with that, no limits just negotiations.
Investor · Salt Lake City, UT · Member since 2015 · 56 posts · 25 votes
3y
Last time I looked at the rates from "portfolio lenders", the rates were multiple percentage points (2-3%) higher than I could get from Freddie/Fannie or Jumbo lenders.
Do you have a few portfolio lenders that will lend on a $1.5 M primary residence for better than 7.375 at par with a 30 year fixed amortization?
I think you may be still thinking mortgage broker when saying portfolio lending.
When I say portfolio lending, I mean it in the banking terminology of such. Which is generally connecting with a regional bank, who your working with 1-on-1, that is not originating mortgages for you but directly lending to you, which will remain on their books, not resold.
With that, lending process generally involves submitting a proposal to be reviewed by bank board, who approves, denies, or lends conditional approval.
Remaining on their books, they can do whatever.
And what they are most often taking into consideration is the entirety of your portfolio.
So while rates are up, yes, you can get more favorable rates because there not originating for resale, they will be holding and servicing that mortgage.
This is also how one can get sizable open line of credit's to acquire properties with the pre-set relation that at whatever point that property acquired with the line of credit will get pulled into an in-house mortgage and thus replenish that working line of credit.
I just recently helped an associate to do this and he received $1.5m line of working capital for the "acquisition rinse and repeat" of things.
So again, at your size you should be looking to setup this kind of direct relationship, not with brokers who are originating for resale of the mortgage.
Thanks for providing an excellent definition of a portfolio lender for those reading. This would have been exactly how I would have defined it as well.
At this point in my investing journey, I have never needed / seen the point to deal with a portfolio lender, especially since I was able to get conforming loans for all my fourplexes as they were purchased in the $800k to $1.1M range, so easily stayed under the limits and I could get Freddie/Fannie money for 2.5% to 3%. When I did speak with a local portfolio lender, they wanted at least 4.5% to lend. They wanted me to "refinance" my portfolio, or some part of that portfolio into that higher rate with a shorter amortization schedule (25 years). That did not make financial sense.
Since this purchase is for a primary residence, there is no need for me to seek a portfolio or commercial loan, so I shopped around with multiple mortgage brokers in my network and provided a bit of education to the one who was providing the best quotes.
I have three fourplexes being built and for those I will get commercial loans with local banks. My current main bank isn't thrilled with financing out of state, but will probably do it because of our existing relationship. They will keep the loans and won't be looking to resell them. Technically the loans will probably be DSCR loans for two of them and since I'm partnering with a buddy on one of the three, he will get Freddie/Fannie money.
Still, I'd LOVE to have a referral, for a portfolio lender, who can do better than what I'm getting quoted from Chase and Key Bank.
10 conventional loans per person. No exceptions and includes your primary. The best trick is to get NON conventional loans when rates are lower, and Conventional loans when rates go up. When/If rates drop- do a refi into non conv loans to open up spots. If you are married, your spouse can get 10 in their name too!
Forgetting about the personal residence issue…the “10 loan limit” is not “10 conventional loans”….it is “10 mortgages properties”, regardless of type of loan.
I think there is come confusion..... you are allowed 10 conventional (Freddie/Fannie) loans. Non conventional loans have no limit. I personally have well over 10 loans as do most investors. I have a client that is at 85 loans right now, But the "golden ticket" is 10 conventional loans per person. That is it. The reason people want these is because the rates are lowest, easy to get with a good credit score, and best terms.
This is incorrect. You can get as many Freddie/Fannie conforming loans as long as you want to owner occupy the property for loans 11, 12, etc. You can NOT get an 11th investment (non-owner occupied) loan if you already have 10. Please see the table at the top of the page for the link provided by @Jay Hurst
I think we are talking about the same thing... Everyone on here is an investor, so I am specifically talking about investment properties. I work with hundreds of clients and investment lenders and while I am not a lender- the conventional lenders that I work with like Aaron Chapman, Graham Parham etc. All have a cap at 10 investment properties for conventional loans
10 conventional loans per person. No exceptions and includes your primary. The best trick is to get NON conventional loans when rates are lower, and Conventional loans when rates go up. When/If rates drop- do a refi into non conv loans to open up spots. If you are married, your spouse can get 10 in their name too!
Forgetting about the personal residence issue…the “10 loan limit” is not “10 conventional loans”….it is “10 mortgages properties”, regardless of type of loan.
I think there is come confusion..... you are allowed 10 conventional (Freddie/Fannie) loans. Non conventional loans have no limit. I personally have well over 10 loans as do most investors. I have a client that is at 85 loans right now, But the "golden ticket" is 10 conventional loans per person. That is it. The reason people want these is because the rates are lowest, easy to get with a good credit score, and best terms.
This is incorrect. You can get as many Freddie/Fannie conforming loans as long as you want to owner occupy the property for loans 11, 12, etc. You can NOT get an 11th investment (non-owner occupied) loan if you already have 10. Please see the table at the top of the page for the link provided by @Jay Hurst
Also, I think there is confusion bc we are not using time frames. You can have limitless loans in a lifetime. As of today- all of my lenders that I work with daily are saying 10 investment loans for rental properties at 1 time are allowed for conventional loan) As per the link you attached- it shows 10 for investment loans.
Investor · Salt Lake City, UT · Member since 2015 · 56 posts · 25 votes
3y
My original post specifically indicated that I was an investor with a number of loans on fourplexes, etc. At the end, I made it very clear that this 11th loan would be for a new primary residence -- owner occupied:
> This would be for a new primary residence for me -- owner occupied, of course. > > It was my understanding, from others, that the 10 loan limit only applies if the property is an investment property > rather than an owner occupied property.
Lender · Nashville, TN · Member since 2017 · 205 posts · 107 votes
3y
Hi @Doug Quist, you have received a variety of answers to a very simple question. This is straight from Fannie Mae's guidelines. Going to be a little different if you end up in a jumbo loan program, as every investor will have their own criteria. I typically originate jumbo loans through Citi Bank, which allows for a max of 5 financed properties for an owner occupied transaction. I believe Chase is a little more lenient, but not positive.
Your primary counts in the 10. I ran into the same problem a couple years ago. My lender told me my primary counted.
Yes, it counts into the 10, if buying new second home or investment property, but how many loans you have is not important or considered when purchasing a new primary, owner occupied mortgage.
Realtor · Memphis, TN · Member since 2018 · 19 posts · 9 votes
3y
@Doug Quist use a DSCR loan. It's a NQM loan product. Typically 25% down and typically if you BRRRR a deal you can refi out of a deal within 6 months due to it not being a qualified mortgage product. Plus way less paperwork and less to consider. Easiest way to scale your portfolio.
Using a DSCR loan isn't possible for my primary residence as it won't be generating any income.
For my two new fourplexes, that are being built, using a DSCR will be one of the options that I'll explore when the time comes.
Realtor · Memphis, TN · Member since 2018 · 19 posts · 9 votes
3y
I missed that you are trying to get a new primary. I would for sure refinance one of the existing loans if not multiple into a DSCR loan product. If you need a mortgage broker I'll send DM the broker I use.