Mortgage Loan Denial
Mortgage Loan Denial

Member since 2024 · 2 posts · 3 votes

Hi everyone,

I’m trying to understand why my mortgage was denied after being pre-approved and wanted to see if anyone has had a similar experience.

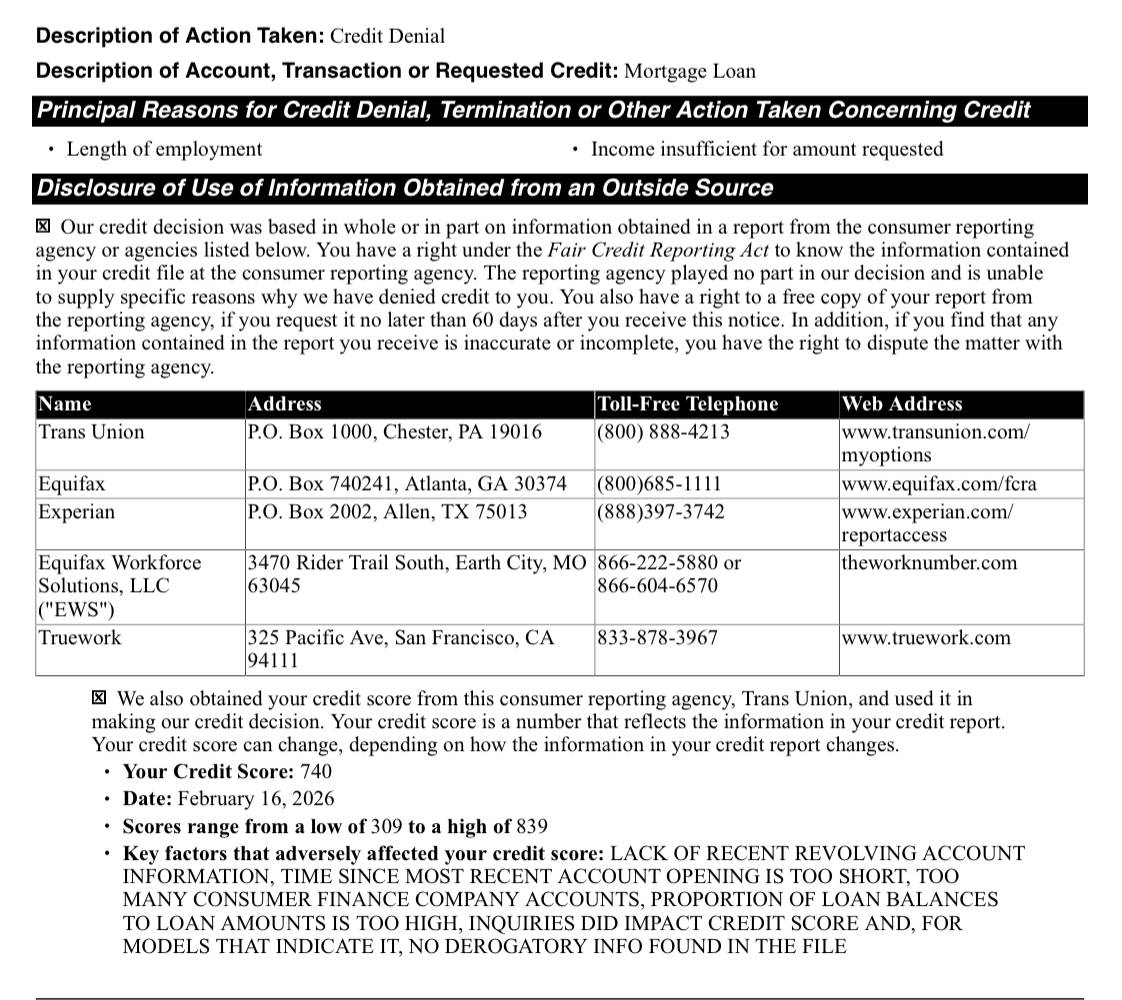
I applied for a $650k mortgage through Navy Federal Credit Union and was initially pre-approved. However, after underwriting, my application was denied. The reasons listed were:

• Length of employment
• Income insufficient for amount requested

Some details about my situation:

  • Credit score: 740
  • Debt: very low (student loans mostly deferred while in school)
  • Income history:
    • 2024 tax return: ~$141k income
    • 2025 tax return: ~$152k income
  • I work remotely as a nurse in utilization/care management.
  • I worked at Humana for about 2 years, then switched jobs within the same field.
  • I currently have two full-time jobs now.
  • My second job is less than a year old, so I’m wondering if underwriting ignored that income.

When I spoke to the lender, they mentioned notes from the underwriter saying:

  • borrower works less than 40 hours (not sure which job they meant)
  • housing ratio exceeds guidelines

So I’m thinking they may have only counted one job instead of both.

I’ve asked my loan officer to appeal the decision and request reconsideration, since I can show 2+ years of stable income in the same field through my tax returns and W-2s.

Has anyone been through something similar?

Specifically wondering:

  1. Were you able to get an appeal approved in a situation like this?
  2. Do lenders ever reconsider second-job income if it's in the same profession?
  3. Would it make sense to try another lender, or is this a standard underwriting rule everywhere?
3Reply
240 views

Most Popular Reply

Erik EstradaBusiness Member
Lender · Member since 2022 · 6k+ posts · 1k+ votes
7mo
Quote from @Angelica Collado:

Hi everyone,

I’m trying to understand why my mortgage was denied after being pre-approved and wanted to see if anyone has had a similar experience.

I applied for a $650k mortgage through Navy Federal Credit Union and was initially pre-approved. However, after underwriting, my application was denied. The reasons listed were:

• Length of employment
• Income insufficient for amount requested

Some details about my situation:

  • Credit score: 740
  • Debt: very low (student loans mostly deferred while in school)
  • Income history:
    • 2024 tax return: ~$141k income
    • 2025 tax return: ~$152k income
  • I work remotely as a nurse in utilization/care management.
  • I worked at Humana for about 2 years, then switched jobs within the same field.
  • I currently have two full-time jobs now.
  • My second job is less than a year old, so I’m wondering if underwriting ignored that income.

When I spoke to the lender, they mentioned notes from the underwriter saying:

  • borrower works less than 40 hours (not sure which job they meant)
  • housing ratio exceeds guidelines

So I’m thinking they may have only counted one job instead of both.

I’ve asked my loan officer to appeal the decision and request reconsideration, since I can show 2+ years of stable income in the same field through my tax returns and W-2s.

Has anyone been through something similar?

Specifically wondering:

  1. Were you able to get an appeal approved in a situation like this?
  2. Do lenders ever reconsider second-job income if it's in the same profession?
  3. Would it make sense to try another lender, or is this a standard underwriting rule everywhere?

 It seems like the Loan Officer did not adequately pre-approve you. I would just reach out to someone more experienced, preferably a broker. Anyone that pushes documents to underwriting without doing due diligence first, will most certainly get a denial letter. 

LuxePrivate Investments LLC 572 Reviews
See this reply in the discussion

12 Replies

Jump to latestLatest
  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    7mo

    Yes you can protest. One thing that I am viewing as an investor and homeowner is $150k is tight for $650k mortgage depending on what escrow payments are also gonna be. That's the top of the mountain so if you get approved just don't bite off more than you can chew 

    7e investments53 Reviews
  • Member since 2024 · 2 posts · 3 votes
    7mo

    Thank you. My income is now $180,000 between both jobs, but I totally am in agreement with you.

  • Erik EstradaBusiness Member
    Lender · Member since 2022 · 6k+ posts · 1k+ votes
    7mo
    Quote from @Angelica Collado:

    Hi everyone,

    I’m trying to understand why my mortgage was denied after being pre-approved and wanted to see if anyone has had a similar experience.

    I applied for a $650k mortgage through Navy Federal Credit Union and was initially pre-approved. However, after underwriting, my application was denied. The reasons listed were:

    • Length of employment
    • Income insufficient for amount requested

    Some details about my situation:

    • Credit score: 740
    • Debt: very low (student loans mostly deferred while in school)
    • Income history:
      • 2024 tax return: ~$141k income
      • 2025 tax return: ~$152k income
    • I work remotely as a nurse in utilization/care management.
    • I worked at Humana for about 2 years, then switched jobs within the same field.
    • I currently have two full-time jobs now.
    • My second job is less than a year old, so I’m wondering if underwriting ignored that income.

    When I spoke to the lender, they mentioned notes from the underwriter saying:

    • borrower works less than 40 hours (not sure which job they meant)
    • housing ratio exceeds guidelines

    So I’m thinking they may have only counted one job instead of both.

    I’ve asked my loan officer to appeal the decision and request reconsideration, since I can show 2+ years of stable income in the same field through my tax returns and W-2s.

    Has anyone been through something similar?

    Specifically wondering:

    1. Were you able to get an appeal approved in a situation like this?
    2. Do lenders ever reconsider second-job income if it's in the same profession?
    3. Would it make sense to try another lender, or is this a standard underwriting rule everywhere?

     It seems like the Loan Officer did not adequately pre-approve you. I would just reach out to someone more experienced, preferably a broker. Anyone that pushes documents to underwriting without doing due diligence first, will most certainly get a denial letter. 

    LuxePrivate Investments LLC 572 Reviews
  • Investor · Austin, TX · Member since 2021 · 497 posts · 127 votes
    7mo

    You got it. They almost certainly ignored the second job income. Conventional guidelines typically require 24 months history to count secondary income and your second job is under a year old.

    You have two practical paths. Appeal with documented field continuity across both roles, same profession, same income type strengthens the case. Or go to a different lender who uses non-QM or bank statement underwriting and counts your full income from day one.

    Don't wait on the appeal alone — shop simultaneously.

    If you want I can help point you toward the right type of lender for your situation.

    What state are you purchasing in?

  • Lender · Charleston, SC · Member since 2019 · 1k+ posts · 1k+ votes
    7mo

    There are a lot of rules involved with this based on the limited info in the post. For one, most traditional loan programs will not count your second job income until you have a 2 year history working that job without gaps and simultaneously to your fulltime job. 

    Secondly, if your fulltime job isnt exactly the same amount of hours each week, meaning that it varies by more than one hour of time worked per week over the period that is evaluated, then your income is considered variable. The lender is most likely going to average your income over the past 24 months, rather than look at what you made last year or last month. This will vary by loan program (VA, Convetional, etc), as each program has its own rules.

    Third, you mentioned that you work as a nurse. Nurses and similar medical professions typically have lots of different pay types, like base, OT, differentials, training, stipends, etc. Not all of these can be used, and how each of them is caculated is not the same as how the base pay will be calculated. 

    In other words, you may have made $150k last year, but only have $110k of qualifying income because of how it's calculated. 

    Lastly - and this is a big one - banks and credit unions are hot garbage when it comes to originating loans. This is par for the course for a credit union. Your loan officer is likely a glorified teller who has no clue what theyre doing and is juggling your loan with 20 other different non-mortgage tasks. I strongly recommend working with a lender or broker who specializes in mortgages if youre trying to get a purchase loan. Refi's can sometimes be a different story as timelines arent as critical, so it's not as big of a deal if they drag on and take 6-7 weeks to close. 

  • Gordon CuffePro Member
    Investor · Roseville, CA · Member since 2009 · 1k+ posts · 587 votes
    7mo

    as a experience mortgage broker , I can only say drop the credit union and apply for a loan with a mortgage broker. This looks like a very easy loan to fund. Sometimes credit unions have brand new people working and they only work by the hour so there is not much incentive to work hard or be creative.  

  • Investor · Get yourself trained before doing something inadvisable. · Member since 2024 · 3k+ posts · 1k+ votes
    7mo
    Quote from @Angelica Collado:

    Hi everyone,

    I’m trying to understand why my mortgage was denied after being pre-approved and wanted to see if anyone has had a similar experience.

    I applied for a $650k mortgage through Navy Federal Credit Union and was initially pre-approved. However, after underwriting, my application was denied. The reasons listed were:

    • Length of employment
    • Income insufficient for amount requested

    Some details about my situation:

    • Credit score: 740
    • Debt: very low (student loans mostly deferred while in school)
    • Income history:
      • 2024 tax return: ~$141k income
      • 2025 tax return: ~$152k income
    • I work remotely as a nurse in utilization/care management.
    • I worked at Humana for about 2 years, then switched jobs within the same field.
    • I currently have two full-time jobs now.
    • My second job is less than a year old, so I’m wondering if underwriting ignored that income.

    When I spoke to the lender, they mentioned notes from the underwriter saying:

    • borrower works less than 40 hours (not sure which job they meant)
    • housing ratio exceeds guidelines

    So I’m thinking they may have only counted one job instead of both.

    I’ve asked my loan officer to appeal the decision and request reconsideration, since I can show 2+ years of stable income in the same field through my tax returns and W-2s.

    Has anyone been through something similar?

    Specifically wondering:

    1. Were you able to get an appeal approved in a situation like this?
    2. Do lenders ever reconsider second-job income if it's in the same profession?
    3. Would it make sense to try another lender, or is this a standard underwriting rule everywhere?
    I used to be a mortgage lender. Often times when one lender wouldn't approve, another one would. You can appeal, but it's likely you need to try other lenders (not banks, they tend to be more difficult) Try a different credit union or smaller lender.
  • J CastroBusiness Member
    Lender · Florida · Member since 2025 · 716 posts · 255 votes
    7mo

    Hi @Angelica Collado, welcome to BP!
    It sounds like you’re dealing with a pretty common situation — lenders often get cautious when a borrower has a short employment history at a new job, even if it’s in the same field. Here’s a breakdown from my perspective:

    1. Second job income – Many underwriters will only count income that’s been stable for at least 2 years. Since your second job is less than a year old, they may have ignored it, even though it’s in the same profession. That’s fairly standard across most traditional lenders.

    2. Employment length – Switching jobs within the same field usually isn’t a deal-breaker, but lenders often want consistency. Your 2+ years in healthcare definitely helps your appeal, but documentation showing continuity of role/responsibilities can strengthen your case.

    3. Housing ratio / debt-to-income (DTI) – Underwriters can be conservative here, especially with higher loan amounts. If they only counted one job, your DTI could have looked higher than it actually is.

    Options:

    • Appeal with your current lender – Definitely worth it. Include pay stubs, W-2s, and a letter explaining that both jobs are stable and in the same profession.

    • Consider a different lender – Some lenders, especially private or portfolio lenders, are more flexible with second-job income and will consider your total earning power.

    Your appeal has a good chance if you clearly document both jobs and your consistent income history. If the appeal doesn’t work, exploring another lender with more flexible guidelines is a smart next step. Best of Luck!

    JCREIG Capital Funding
  • Raymond J. RodriguesBusiness Member
    Lender · Miami, FL · Member since 2017 · 1k+ posts · 797 votes
    7mo

    @Angelica Collado the answer is simple and short. When calculating two jobs worth of income, you have to have been working both jobs for at least 12 months, in order to count both jobs income. Some loan types require 24 months with each job. Anyone can pick up a job to try and qualify for a loan the next day. Lenders need to know that you can manage that lifestyle before they will allow you to use it to qualify. I hope this helps. 

  • FL and GA · Member since 2023 · 1 post · 0 votes
    7mo

    If you are willing to put 10% down, you can bypass the tax returns and do a bank statements loan.

    Roland Victor

    813.244.2978

  • Roland VictorPro Member
    Lender · Member since 2025 · 2 posts · 0 votes
    7mo

    If you are willing to put 10% down, you can bypass the tax returns and do a bank statements loan.

    Roland Victor

    813.244.2978

  • Investor · NY · Member since 2026 · 121 posts · 42 votes
    7mo

    Just do DSCR you can close within 10 days

Join the conversationCreate a free account to reply, vote on answers and follow this thread.