🏡 OKC Rental Refi Review, Delayed Financing vs DSCR, Do These Terms Make Sense?
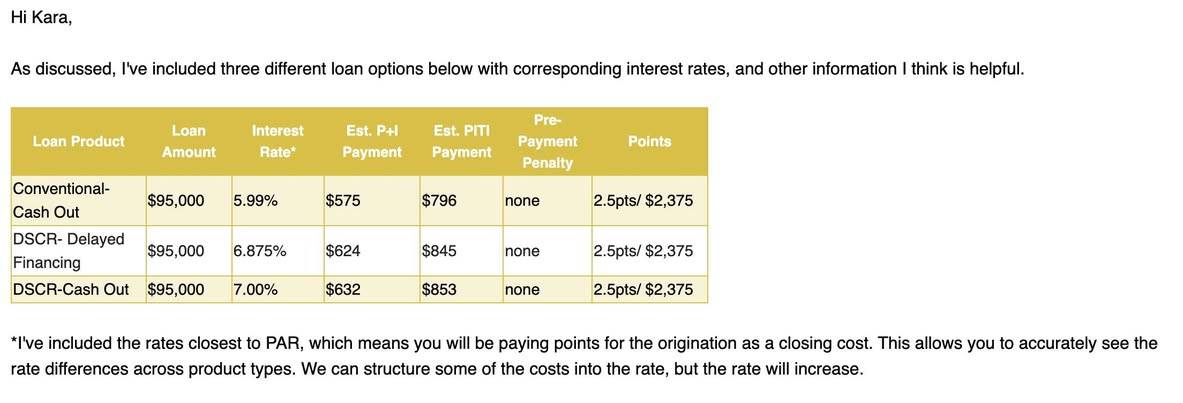
Any loan officers in OK open to a quick second opinion? I received these numbers today and want to check it and confirm that this is making sense and that we're looking at this the right way.
The background:
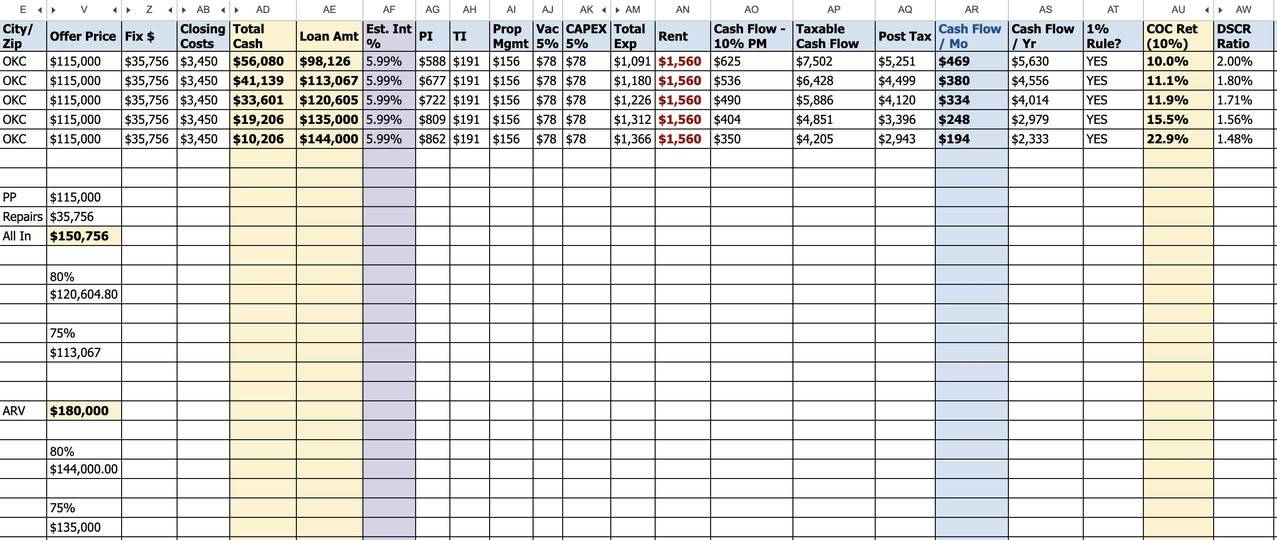
Purchased a SFR home in OKC with cash last year for $115,000, then spent $35,000 in repairs, so I'm in it approximately $150,000.
Estimated ARV is $180,000-$190,000.
I have 2 conventional loans right now and plan to purchase 6-10 homes in OKC the next 1-2 years once I sell one of my homes in CA (moving me down to only 1 conventional loan) this summer. I am mindful of the conventional loan max, but I'm not overly concerned at this moment.
I am a realtor and flip homes in CA, and while I'd prefer to go the easiest route for financing, I'm open to a full doc option if it makes more sense in the long run for getting a better rate.
My 6 months (for delayed financing option) is up on April 19 (which I guess would really be Fri April 17)
Rent is going to be $1,560/mo. Goal is to keep as a LTR. Proposed move in date is 4/1/26, but it's a section 8 tenant so we're going through the process right now with inspections.
My credit score is approximately 790-830 at the various bureaus.
Ideal goal is 12%+ COC return after factoring DP, repairs and 10% for property management and 10% for vacancy/capex. Taxes are $1,450/year. Insurance is $1,200/yr. This means a target PITI of $732.
I appreciate flexibility to refi or sell without huge pre-payment penalties, but I'm open to having one if it makes sense with a ton of upside on the cash flow. I'm thinking that the loan amount is so low that it's a pretty minimal benefit to taking on the penalty.
I don't want to over leverage myself, so I'm thinking that a loan amount of around $120,000 is the best all things considered.
What I’m trying to understand:
Are these rates and points competitive right now?
How would you recommend structuring this (DSCR vs conventional)?
Know of any OK lenders offering better delayed financing terms?
Does 2.5 points make sense at this loan size?
Open to connecting if you see a better structure or have helpful insight.