Investor · Get yourself trained before doing something inadvisable. · Member since 2024 · 3k+ posts · 1k+ votes
If you read that as "SubTo IS Mortgage Fraud" go back to your 4th grade teacher and apologize for not listening in class about sentence structure.
Subject To is legal, when done legally.
The problem comes in when you fill out lending or tax forms and you omit information. Sure your SubTo mortgage doesn't show up on your credit report, but you still owe the money you took over when you did the SubTo. The government demands that you list that on the forms. It is not an option.
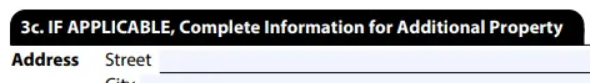
The form reads Click on to expand:
Prosecutors might file federal charges for bank fraud, loan and credit application fraud, wire fraud, or conspiracy to commit any of these crimes. They can also file federal racketeering charges under RICO (the Racketeer Influenced and Corrupt Organizations Act), especially in cases involving large-scale mortgage fraud schemes.
Loan application fraud statutes carry up to 30 years of prison time and $1,000,000 in fines. These penalties apply whether the defendant is the principal actor, attempted the offense, or conspired to commit fraud.
******************************************
You were smart enough to buy a property SubTo, don't be stupid enough to lie about it.
That’s something I wasn’t aware of - I assumed because someone taking over a property sub to doesn’t have personal liability and haven’t “acknowledge” the mortgage that it wasn’t a liability. Now I see where it could be a liability and interesting that it is considered one. Ken, if one were to purchase a property sub to taking title in the name of an entity, would that person still be require to list the mortgage note as a liability on their PFS so as to avoid a fraud charge?
I would think so. The Judge thought so in a case I was a professional witness in. :-) Anyway, anyone who has responsibility for the debt would have to list it. The goal is to understand debt liability vs income to determine risk. The lender has a right to know.
As you already know, but the lurkers don't necessarily, since these are backed by the good ole' USA (we as tax payers), I want that risk to be known too.
Liability and responsibility while somewhat related are two different concepts. I may be in some (limited) way the “responsible” party for loan payments, but have no “liability” should the payments not be made. I could more easily see that if one is required to list all ASSETS, then one would have to list the subject property and because the value of the property is listed as an asset the mortgage note needs to be listed as a liability whether or not the subject person is legally “liable”, “responsible” or not. In the case you refer to did the person list the property as an asset and not list the mortgage debt associated with it, or fail to list the asset all together?
If you read that as "SubTo IS Mortgage Fraud" go back to your 4th grade teacher and apologize for not listening in class about sentence structure.
Subject To is legal, when done legally.
The problem comes in when you fill out lending or tax forms and you omit information. Sure your SubTo mortgage doesn't show up on your credit report, but you still owe the money you took over when you did the SubTo. The government demands that you list that on the forms. It is not an option.
The form reads Click on to expand:
Prosecutors might file federal charges for bank fraud, loan and credit application fraud, wire fraud, or conspiracy to commit any of these crimes. They can also file federal racketeering charges under RICO (the Racketeer Influenced and Corrupt Organizations Act), especially in cases involving large-scale mortgage fraud schemes.
Loan application fraud statutes carry up to 30 years of prison time and $1,000,000 in fines. These penalties apply whether the defendant is the principal actor, attempted the offense, or conspired to commit fraud.
******************************************
You were smart enough to buy a property SubTo, don't be stupid enough to lie about it.
That’s something I wasn’t aware of - I assumed because someone taking over a property sub to doesn’t have personal liability and haven’t “acknowledge” the mortgage that it wasn’t a liability. Now I see where it could be a liability and interesting that it is considered one. Ken, if one were to purchase a property sub to taking title in the name of an entity, would that person still be require to list the mortgage note as a liability on their PFS so as to avoid a fraud charge?
One always has to list all their mortgages whether they are private or not on the PFS or application to a federal or state chartered bank.. although they usually pick them up on your tax returns though if you dont list it.
If you read that as "SubTo IS Mortgage Fraud" go back to your 4th grade teacher and apologize for not listening in class about sentence structure.
Subject To is legal, when done legally.
The problem comes in when you fill out lending or tax forms and you omit information. Sure your SubTo mortgage doesn't show up on your credit report, but you still owe the money you took over when you did the SubTo. The government demands that you list that on the forms. It is not an option.
The form reads Click on to expand:
Prosecutors might file federal charges for bank fraud, loan and credit application fraud, wire fraud, or conspiracy to commit any of these crimes. They can also file federal racketeering charges under RICO (the Racketeer Influenced and Corrupt Organizations Act), especially in cases involving large-scale mortgage fraud schemes.
Loan application fraud statutes carry up to 30 years of prison time and $1,000,000 in fines. These penalties apply whether the defendant is the principal actor, attempted the offense, or conspired to commit fraud.
******************************************
You were smart enough to buy a property SubTo, don't be stupid enough to lie about it.
That’s something I wasn’t aware of - I assumed because someone taking over a property sub to doesn’t have personal liability and haven’t “acknowledge” the mortgage that it wasn’t a liability. Now I see where it could be a liability and interesting that it is considered one. Ken, if one were to purchase a property sub to taking title in the name of an entity, would that person still be require to list the mortgage note as a liability on their PFS so as to avoid a fraud charge?
I would think so. The Judge thought so in a case I was a professional witness in. :-) Anyway, anyone who has responsibility for the debt would have to list it. The goal is to understand debt liability vs income to determine risk. The lender has a right to know.
As you already know, but the lurkers don't necessarily, since these are backed by the good ole' USA (we as tax payers), I want that risk to be known too.
Liability and responsibility while somewhat related are two different concepts. I may be in some (limited) way the “responsible” party for loan payments, but have no “liability” should the payments not be made. I could more easily see that if one is required to list all ASSETS, then one would have to list the subject property and because the value of the property is listed as an asset the mortgage note needs to be listed as a liability whether or not the subject person is legally “liable”, “responsible” or not. In the case you refer to did the person list the property as an asset and not list the mortgage debt associated with it, or fail to list the asset all together?
If it was Additional Property, you would list it. How it's financed is secondary. Same thing in bankruptcy court. When the question comes up, it is typically searching for any creative financing that
1. May have been a violation of law (scam)
2. May have hurt "vulnerable people" (elderly, disabled, etc)
3. May have violated the Consumer Protection Act
4. May have had excessive fees (foreclosure avoidance)
5. Were any taxes paid or deductions taken on the transaction (is it listed on your tax returns, oh yes, they look)
6. And in some places "May not have been in the public interest" figure that one out.
That was only a small part of the case. The case revolved around other issues, but it was brought up as "deception" to support another argument.
In court, perception is almost always the prevailing winner. Rightly or wrongly, whoever makes the best argument, gets the nod from the judge. I prefer to be squeaky clean, since it is the law. Life is easier that way.
There is someone, famous now, on Youtube, with a truckload of followers, who is probably headed for serious problems because of his cavalier approach to SubTo. He gives bad information and takes risky shortcuts, according to his videos. The SOL ( statute of limitations) can be 6 or 7 years, depending on the state it's prosecuted in, and that is after it has been discovered. It's just not worth the risk.
Send them my way. :-) One just needs to be trained on what a good deal is, what the law is and how to complete the transaction. I wouldn't try being a real estate agent, I'm not trained that way.