another "poor millennial can't afford a house" article, critiqued

another "poor millennial can't afford a house" article, critiqued

Adam TafelBusiness Member
Real Estate Agent · St. Paul, MN · Member since 2017 · 582 posts · 399 votes

Article:

https://www.wsj.com/articles/your-parents-financial-advice-is-kind-of-wrong-11568367000?mod=e2fb&fbclid=IwAR2XL4axyaQpo43fAkn_Q_fWBU3GiHJ9_K6t5c8G6rMnPCfed1KBBXIVhTo

Response:

Let me set the scene to save you some time. Our subject is 32 years old, a regulatory attorney living in Seattle. She got her undergrad at University of Rochester, law degree at Syracuse, and is absolutely crippled and distraught over her remaining 140k in student loan debt. Home ownership is completely out of reach, she got bad advice from her parents regarding her education, and feels like a “moral failure when [she] can’t reach these milestones”. Ok. Deep breath. Lets break this down.

Our friend didn’t pick cheap schools. She probably spent about 50k/year for 7 years of education, that’s a nice price tag. She’s been making payments for “much of the last decade”, which has got to sting a bit. Who knows how much was financed, but if she’s got her principal down to 140k she’s made a serious dent. She claims to be living frugally (packs a lunch, doesn’t vacation, takes bus), and shares a modest apartment with her husband. If she makes 100k/year, contributing 4000/mo will pay off the balance in about 3 years. If she’s a working attorney with a 350k education and can’t set aside 52k/year, I am forced to call BS on her “frugal” lifestyle. Regardless of my optimism, I feel for her.

Well played so far, WSJ. We’ve cherry-picked someone with a ton of debt, living in one of the most competitive housing markets in the USA, mad at the world. Yes, it will be a few years before our friend owns a home. It’s a convenient case study to make a point: it’s so hard for us millennials to buy houses! Here we go...

Citing “Apartment List” as a source, Carpenter (author) claims that 2/3 of millennial renters need at least 20 years to save 20% on a median priced home. Excuse you? Let’s do some quick maths. 280k (median home price) x .2 / 20 years = $53.84 per week, not accounting for 20 years of interest/stock market gains. Ok, maybe avocado toast IS a relevant concern at this point? If you don’t have more than $200 extra at the end of the month, please don’t invest in real estate. It’s not for you, you’ll get burned. My point is that these ^ numbers are nonsensical.

Let’s address the boogyman of the article: 20% down payment. Are you scared? It’s referenced at least five times, which is weird, considering she represents the WSJ and the average down payment in the US is 6%. I was making a lousy 38k when I bought my first house with a credit score of 620, it cost me about 5k. Yes, I’m in St. Paul, not Seattle. I still only hear excuses.

She then tells a tale of her parents, living in the good old days of 1980, buying a starter home in Decatur, GA with 22k down (adjusted for inflation). According to RedFin: the average home price in Decatur is currently 223k. Her parents' house might (unlikely but perhaps) be attainable TODAY for a measly 8k with an FHA loan! Regardless of the actual numbers, I think millennial home ownership is probably alive and well in ol' Decatur, as starter-home barrier to entry is under 10k.

The Wall Street Journal writer then suggests that we "consider" a Roth IRA. How about if you do ANYTHING short of lighting your money on FIRE you will max out that Roth IRA, you will eat ramen every Thursday before payday to hit that max, no excuses, you spend more on ubers in a year than the 6k the government lets you invest tax free, are you hearing me?

My main gripe with this article is the order in which it’s structured. IF it began with showing readers the best grad school choices to see financial returns, cited the attorney as a cautionary tale of bad financial planning, and then used relevant data on down payment/mortgage qualification, rather than “I told my mom I might need 20% for a house and she just couldn’t literally even”, I would consider it an excellent read.

The article isn’t 100% bogus. She’s got tons of great data points on the discrepancies between current cost of living ratios and those of our parents, but who doesn’t already know this? Yes, the thesis is correct: we need to look at money through a different lens than our parents did. The trouble with these statistics is that people turn them into excuses. The author reminds us that the median home price in 1979 was 68k less than today. Ok, so an extra $300 on a mortgage payment… Airbnb didn’t exist in 1979, either.

She makes an argument for viewing education as a financial investment that must result in direct gains to the student, something our attorney friend may have forgotten. Some good advice is given, comparing expensive graduate programs to their cheaper online substitutes. I’m getting off track, please don’t take educational advice from the guy who dropped out of three (three?!) community colleges, I’m here to talk about real estate!

Alright, no more negativity. I am biased and also blessed. I enjoyed many debt-free years of work in my mid 20s (it’s hard to rack up student loan debt when you can’t even get into a real college) and was able to save. I worked as a server, lived in cheap apartments, and always had plenty of extra dough. I don’t have kids, or a disability, and my family is supportive. I don’t know the backstory of the author or her subject; I’m simply using their arguments to illustrate a point: it’s all about perspective.

I hang out with a lot of realtors/investors/entrepreneurs. We hear things differently, we have optimism. When we hear “the median home now sells for four times the median income”, we envision finding a free place to live for 4 years, saving every dime, and buying a home outright. Realistic? Maybe not for most people, but that’s not entirely the point. It’s a mindset adjustment that leads to building wealth.

I heard something great on the Biggerpockets podcast the other day: getting pre-approved for a home loan is like getting a checkup at the doctor. You don’t have to buy, but it’s nice to know your financial health. Yes, your credit score will drop 5 points for a few months, you’ll survive. There’s nothing wrong with renting, and it makes sense for many people. Just don’t let articles like this make the decision for you.

Julia Carpenter, if you’re reading this, let a realtor buy you coffee sometime. We’d love to help!

-Adam Tafel

Upside Property Sales 4.9108 Reviews
16Reply
177 views

Most Popular Reply

Russell BrazilBusiness Member
Moderator
Real Estate Agent · Washington, D.C. · Member since 2012 · 17k+ posts · 30k+ votes
6y

I had about $100k in debt soon after I got out of school. I paid it all off before I was 30, without making over $70k a year, and that salary only when close to 30. I think my first job was about $30k at age 23. 

I lived cheaply, had roommates, got side hustles. I didnt spend $50 on avocado toast, instead I went to cheap happy hours. All while living in 2 of the more expensive cities of Boston and DC. Paid it all off and saved for my first rentals. 

We dont have a student loan crisis....we have a personal finance, spending, and consumerism crisis.

See this reply in the discussion

56 Replies

Jump to latestLatest
  • Anthony GaydenPro Member
    Rental Property Investor · Omaha, NE · Member since 2014 · 2k+ posts · 3k+ votes
    6y

    @Adam Tafel

    I agree with your observations, however I have always had a hard time being sympathetic to those who chose extremely expensive career fields at expensive universities and then are surprised to have so much debt. Their solution is people like me should pay off their student loans for them through my taxes. Keep in mind that I lived with my parents while commuting to community college and working a full-time job. 

    The entitled attitude is what bothers me the most. You live in one of the most expensive cities in the US and you are surprised that it is difficult and expensive to buy a house? 

    Honestly, the student loan issue doesn't bother me at all in cases such as the one featured, a highly paid upper middle class lawyer. 

    As for home ownership, it may require that she move out of that expensive city to a less expensive area. 

  • Specialist · Riverside, CA · Member since 2015 · 6k+ posts · 3k+ votes
    6y

    Agree I really dislike the lack of math and practical solutions (aside from policy changes) in these types of articles.

  • Investor · NJ · Member since 2018 · 869 posts · 921 votes
    6y

    As I am technically a millenial myself, I think it's funny when other millenials talk about their debts. It's ironic how we were taught that if you didn't go to college you'd be a nobody and be financially ruined. I decided to not go to college and go into trades and avoided that debt. now I own my own business that has nice growth, I still have a great job that pays well with full benefits, a professional license from the state and the best part is literally zero debts for anything besides mortgages.

    Then everytime I see old friends from high school they cry poverty and tell me that they have over 100k in debt. Same sob stories.

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    6y

    @Adam Tafel  not all attorney's make big bucks especially starting out.. 

    and median home price in that market is closer to 700k not 280k.. this is very region specific this question of home ownership. 

  • Handyman · Pittsburgh, PA · Member since 2018 · 5k+ posts · 13k+ votes
    6y

    We had these sob stories in my day, too, back when Gen. X was coming of age. Oh, so hard...so hard to make a buck in this world. So unfair. I believed it, too. I was raised on this brain gunk. I didn't believe that 83% of millionaires get there in one generation. What's the first rule of life? Have rich parents. I thought that was how it was.

    Then I read The Millionaire Next Door. Then I started living it. I keep getting closer to being it. Suddenly, an impossible puzzle came apart in my hands. But all my friends...they had to have the house and the car and the aspirational lifestyle. They had to be middle class, shooting for upper middle class.

    One of my closest friends from college is a tech guy who lives in an $800K house. I met him in state school. I know his parents. He grew up just as broke as me, ate government cheese, always made fun of Boomer pretensions. I reach into my mailbox today and find a Christmas card from him. Professional photoshoot of his kids and wife, custom card pattern and printing. Must have cost a fortune to send me and 200 other people a card on Christmas. They're all wearing matching scarves. Really? Really, dude? That's how you salt it away?

    This guy's like a brother. I would much rather know he's built an unassailable financial position for himself and his family than get that card. Generational wealth for his kids. The power to establish a philanthropic legacy. But what I get is a card, and that card fuels my determination to be there when the wolf comes snarling to his door, as it comes to all our doors.

  • Russell BrazilBusiness Member
    Moderator
    Real Estate Agent · Washington, D.C. · Member since 2012 · 17k+ posts · 30k+ votes
    6y

    I had about $100k in debt soon after I got out of school. I paid it all off before I was 30, without making over $70k a year, and that salary only when close to 30. I think my first job was about $30k at age 23. 

    I lived cheaply, had roommates, got side hustles. I didnt spend $50 on avocado toast, instead I went to cheap happy hours. All while living in 2 of the more expensive cities of Boston and DC. Paid it all off and saved for my first rentals. 

    We dont have a student loan crisis....we have a personal finance, spending, and consumerism crisis.

  • Rental Property Investor · Durham, NC · Member since 2016 · 7k+ posts · 7k+ votes
    6y

    @Adam Tafel I read some of your thread but I didn’t read the article. In general I hate all these millennial bashing or “woe is me” articles about my generation.

    I live in an expensive market. There are plenty of affordable houses in my market. When I buy my first home to live in a few years (I rent by choice), I will probably put 20 percent down.

    Your life is what you make it. Borrowing 100k or more to be a lawyer that isn’t from a top 20 school, is probably going to leave you in a hole you have a hard time getting out of. I can tell you that, no research required.

  • Rental Property Investor · East Wenatchee, WA · Member since 2014 · 10k+ posts · 16k+ votes
    6y
    Originally posted by @Adam Tafel:

    Article:

    https://www.wsj.com/articles/your-parents-financial-advice-is-kind-of-wrong-11568367000?mod=e2fb&fbclid=IwAR2XL4axyaQpo43fAkn_Q_fWBU3GiHJ9_K6t5c8G6rMnPCfed1KBBXIVhTo

    Response:

    Let me set the scene to save you some time. Our subject is 32 years old, a regulatory attorney living in Seattle. She got her undergrad at University of Rochester, law degree at Syracuse, and is absolutely crippled and distraught over her remaining 140k in student loan debt. Home ownership is completely out of reach, she got bad advice from her parents regarding her education, and feels like a “moral failure when [she] can’t reach these milestones”. Ok. Deep breath. Lets break this down.

    Our friend didn’t pick cheap schools. She probably spent about 50k/year for 7 years of education, that’s a nice price tag. She’s been making payments for “much of the last decade”, which has got to sting a bit. Who knows how much was financed, but if she’s got her principal down to 140k she’s made a serious dent. She claims to be living frugally (packs a lunch, doesn’t vacation, takes bus), and shares a modest apartment with her husband. If she makes 100k/year, contributing 4000/mo will pay off the balance in about 3 years. If she’s a working attorney with a 350k education and can’t set aside 52k/year, I am forced to call BS on her “frugal” lifestyle. Regardless of my optimism, I feel for her.

    Well played so far, WSJ. We’ve cherry-picked someone with a ton of debt, living in one of the most competitive housing markets in the USA, mad at the world. Yes, it will be a few years before our friend owns a home. It’s a convenient case study to make a point: it’s so hard for us millennials to buy houses! Here we go...

    Citing “Apartment List” as a source, Carpenter (author) claims that 2/3 of millennial renters need at least 20 years to save 20% on a median priced home. Excuse you? Let’s do some quick maths. 280k (median home price) x .2 / 20 years = $53.84 per week, not accounting for 20 years of interest/stock market gains. Ok, maybe avocado toast IS a relevant concern at this point? If you don’t have more than $200 extra at the end of the month, please don’t invest in real estate. It’s not for you, you’ll get burned. My point is that these ^ numbers are nonsensical.

    Let’s address the boogyman of the article: 20% down payment. Are you scared? It’s referenced at least five times, which is weird, considering she represents the WSJ and the average down payment in the US is 6%. I was making a lousy 38k when I bought my first house with a credit score of 620, it cost me about 5k. Yes, I’m in St. Paul, not Seattle. I still only hear excuses.

    She then tells a tale of her parents, living in the good old days of 1980, buying a starter home in Decatur, GA with 22k down (adjusted for inflation). According to RedFin: the average home price in Decatur is currently 223k. Her parents' house might (unlikely but perhaps) be attainable TODAY for a measly 8k with an FHA loan! Regardless of the actual numbers, I think millennial home ownership is probably alive and well in ol' Decatur, as starter-home barrier to entry is under 10k.

    The Wall Street Journal writer then suggests that we "consider" a Roth IRA. How about if you do ANYTHING short of lighting your money on FIRE you will max out that Roth IRA, you will eat ramen every Thursday before payday to hit that max, no excuses, you spend more on ubers in a year than the 6k the government lets you invest tax free, are you hearing me?

    My main gripe with this article is the order in which it’s structured. IF it began with showing readers the best grad school choices to see financial returns, cited the attorney as a cautionary tale of bad financial planning, and then used relevant data on down payment/mortgage qualification, rather than “I told my mom I might need 20% for a house and she just couldn’t literally even”, I would consider it an excellent read.

    The article isn’t 100% bogus. She’s got tons of great data points on the discrepancies between current cost of living ratios and those of our parents, but who doesn’t already know this? Yes, the thesis is correct: we need to look at money through a different lens than our parents did. The trouble with these statistics is that people turn them into excuses. The author reminds us that the median home price in 1979 was 68k less than today. Ok, so an extra $300 on a mortgage payment… Airbnb didn’t exist in 1979, either.

    She makes an argument for viewing education as a financial investment that must result in direct gains to the student, something our attorney friend may have forgotten. Some good advice is given, comparing expensive graduate programs to their cheaper online substitutes. I’m getting off track, please don’t take educational advice from the guy who dropped out of three (three?!) community colleges, I’m here to talk about real estate!

    Alright, no more negativity. I am biased and also blessed. I enjoyed many debt-free years of work in my mid 20s (it’s hard to rack up student loan debt when you can’t even get into a real college) and was able to save. I worked as a server, lived in cheap apartments, and always had plenty of extra dough. I don’t have kids, or a disability, and my family is supportive. I don’t know the backstory of the author or her subject; I’m simply using their arguments to illustrate a point: it’s all about perspective.

    I hang out with a lot of realtors/investors/entrepreneurs. We hear things differently, we have optimism. When we hear “the median home now sells for four times the median income”, we envision finding a free place to live for 4 years, saving every dime, and buying a home outright. Realistic? Maybe not for most people, but that’s not entirely the point. It’s a mindset adjustment that leads to building wealth.

    I heard something great on the Biggerpockets podcast the other day: getting pre-approved for a home loan is like getting a checkup at the doctor. You don’t have to buy, but it’s nice to know your financial health. Yes, your credit score will drop 5 points for a few months, you’ll survive. There’s nothing wrong with renting, and it makes sense for many people. Just don’t let articles like this make the decision for you.

    Julia Carpenter, if you’re reading this, let a realtor buy you coffee sometime. We’d love to help!

    -Adam Tafel

    Your critique is well-written and interesting.  I hope you write professionally in some capacity, Adam.  If not, you should 👍 

    College choice is huge.  Cute colleges  private or out of state cost a bundle. Some of us went to a state school and worked but nobody's writing about that.  And nope, don't need 20% down unless it's an investment.

    The article was probably another yawner, but your writing is superb!

  • Rental Property Investor · Bloomington, MN · Member since 2019 · 404 posts · 542 votes
    6y

    @Adam Tafel Interesting part about your first property. I was also making around $38k when I bought my first property 10 minutes outside St Paul. My credit score was higher though. :)

  • Investor · Wakefield, MA · Member since 2019 · 31 posts · 73 votes
    6y

    As a Millennial, it disheartens me to see so many of my generation "struggling". But I suspect a lot of this is due to people not truly being willing to make sacrifices (e.g. the schools, the lifestyle, etc). Packing a lunch is not a sacrifice. I listen to some people who make six-figure salaries tell me they will never be able to afford a home - well that may be true if only a luxury home in the most expensive neighborhood will do (all the while paying high rent to live alone). Other people I know complain that they had to spend some money renovating one part of their home and how much of a struggle it was. Everyone wants perfection and they want it immediately.

    On the other hand, if they were willing to do something like what a lot of people on here do (myself included): buy a fixer-upper and house-hack or just whatever it takes to get started, they could make a real sacrifice for a few years and come out far ahead. But people usually balk when hearing this. Too much work and supposedly too risky. 

    That said, I wonder if the subject of the article can't buy a home because her debt to income ratio is too high with how much she still owes in loans.

  • Contractor · Fitchburg, MA · Member since 2018 · 7 posts · 7 votes
    6y

    So happy to see everyone on here has such a great understanding of what it’s like navigating your way into adulthood on a foundation of bad advice from all you parents, teachers and mentors. Please tell me more about myself!

  • Developer · NY/NJ/PA · Member since 2018 · 758 posts · 935 votes
    6y
    Originally posted by @Caleb Heimsoth:

    @Adam Tafel I read some of your thread but I didn’t read the article. In general I hate all these millennial bashing or “woe is me” articles about my generation.

    I live in an expensive market. There are plenty of affordable houses in my market. When I buy my first home to live in a few years (I rent by choice), I will probably put 20 percent down.

    Your life is what you make it. Borrowing 100k or more to be a lawyer that isn’t from a top 20 school, is probably going to leave you in a hole you have a hard time getting out of. I can tell you that, no research required.

     I agree these articles are def stupid, but there are differences from our generations to our parents the boomers. Boomers raised these millennials. They have some responsibility of raising them like crap. 
    Boomers told their kids to go get educated, regardless of cost. A 17 year old didn’t make that decision, their parents did.


    my parents told us to go to schools we had the highest  scholarship. They told my sister to live at home for her undergrad/med school. Saved her $100k at least in NY. I did the same for 1 year and then transferred into a CUNY so I could save tuition $. We both graduated with low debt relative to our degrees. It’s the guidance from parents that help you when your a dumb teenager. 

  • Real Estate Consultant · Bloomfield, NJ · Member since 2010 · 2k+ posts · 1k+ votes
    6y

    @Syed H.

    Agreed . But I think what everyone is saying is that the article needs to be honest and admit that. Furthermore none of us were raised perfectly or on perfect advice. We have the personal responsibility to acknowledge what our parents did right and what they did wrong and build from there.

  • Rental Property Investor · South shore, MA · Member since 2017 · 1k+ posts · 1k+ votes
    6y

    Great post, thank you for sharing!

    As a millennial I didn't go to college, I tried it for a couple months at a community college, spent about $1000 on a few classes and never went back. I was under the impression that it was something I HAD to do in order to succeed in life. So, when my brilliant 19 year old mind was telling me otherwise, it was a battle of tug o' war.

    Now I didn't exactly succeed for the majority of my 20s, I did quite the opposite actually. But when I started to grow up and educate myself on sites like biggerpockets, and listening to podcasts, reading books, etc. I was able to implement strategies that I saw first hand working in my own life. Not just Real Estate, but finances as well. 

    I also believe that my poor choices in life put me in positions to HAVE to live frugally for a long time, and to be able to enjoy more with less. Getting my own apartment was once the biggest accomplishment I had achieved, and that was only a few years back. I have become a minimalist millennial through that process, and try to take advantage of it financially. Ive seen the fruits from my labor. Its not that difficult, But it does take hard work. 

  • WorldWide · Member since 2016 · 1k+ posts · 1k+ votes
    6y

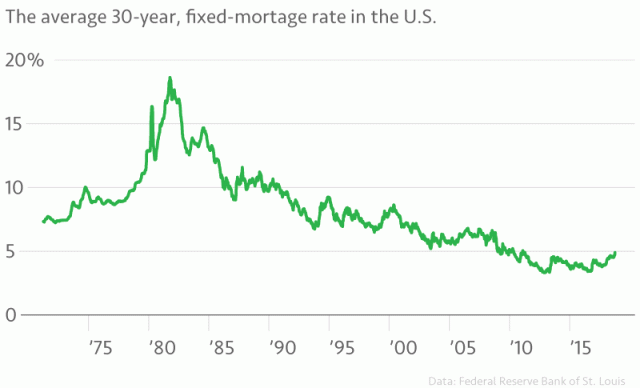
    they had different problems in the 80s, like high double-digit interest rates on mortgages:

    "The early ’80s saw particularly high rates, with the 30-year mortgage reaching a peak of 18.63 percent in October 1981, according to data from the Federal Reserve Bank of St. Louis."

    you wonder why housing was cheap(er)? was it really, tho? i can't imagine what total interest paid on a $100k house would look like after 30 years at double digit apr. it looks like people in the 80s refied every 5 years or so. 

    "If she makes 100k/year, contributing 4000/mo will pay off the balance in about 3 years. If she’s a working attorney with a 350k education and can’t set aside 52k/year, I am forced to call BS on her “frugal” lifestyle."

    After-tax, that 100k goes to mid $60s clean take home, if not less in states with higher local taxation. My take-home is around 63% right now after 401k @8% and a few medical contributions. maybe her husband has six-digit debt to contribute to as well. 100k in Seattle area is nothing like 100k in OKC. We're getting into specifics now, but I do agree that paying large debts off takes a lot of sacrifice. 


  • Rental Property Investor · Erie, PA · Member since 2015 · 1k+ posts · 2k+ votes
    6y

    I don't feel bad for her. She's in a ridiculously expensive market. She could move somewhere else and afford a house in 99% of this great country.

    I attended a college that cost around 5K a year and went to an expensive graduate school for two years (USC). Glad I went to college though it didn't really help me make money (granted I chose a major that isn't great for money). 

    It simply helped me not be so shy (I joined a fraternity and the one nice thing about that, aside from becoming less shy, was that a fraternity is a great microcosm of how life works and the B.S. social structure of society, which was a great lesson to learn young as you quickly learn that that popularity contest most people strive for is both an illusion and a waste of time and money).

    My nephew is 24 and has owned a house a few years (he worked and went to college later - he's still attending though he works a full work week). It's not hard to do when one isn't in a market that's red-hot and is smart with one's money. 

    This article should be more about specific markets that are ultra-expensive and not the general market for as mentioned, the lawyer lady could always move and buy a house in 99% of America - and if she doesn't want to then she can put on a hardhat because life is hard. 

    If Seattle has expensive homes then that's the way it is, but she can always join BP and educate herself and find ways she and her husband can get themselves a home within their budget (buy an ugly house and fix it up, house hack, etc.). 

    So many millennials (and Gen Xers, and boomers, and whatever other age class), successful or not, would rather get offended and make excuses than to find a way to do something. 

  • South Holland, IL · Member since 2017 · 374 posts · 432 votes
    6y

    @Adam Tafel

    There is PLENTY of affordable housing in the US. I have no pity for those choosing to live in tent cities rather than move to cheap housing in “flyover county” or must live on the EAST Coast. The problem is people desire to live where they WANT to live not where they SHOULD live according to their current finances. Sleep in the bed you’ve made but don’t expect me (taxpayers) to bail you out.

  • Mike CumbieBusiness Member
    REALTOR® · Brockport, NY · Member since 2015 · 3k+ posts · 4k+ votes
    6y

    Plenty of Millennial's are buying houses. Plenty of Gen X and Boomers still haven't because "They just can't afford it". It's not that it can't be done and someone else is at fault (Been there with that feeling). It's that some people just never woke up enough to see that they are doing it wrong and nobody can tell them otherwise. I'm sure most investors on here can tell stories of how they lost 20/50/100K on something due to a bad decision. These are of course in times where they did not have 20/50/100K but took a roll on something. When it failed they either sat there and blamed others or stood back and reevaluated their position and went forward. 

  • Cherry Hill, NJ · Member since 2019 · 51 posts · 21 votes
    6y

    I really appreciate this share and your analysis of the article.  Unfortunately, the model that most of our parents have given us does not align with the current costs of education, housing, etc..  Most don't realize that we have have to turn to other solutions, and sometimes be creative, to be able to "make it" today.  As a Millenial myself, I am thankful I discovered the FIRE movement and abandoned the entitlement mindset.  With the resources and information available to us, I feel like there are just no excuses anymore.

  • Joe SplitrockPro Member
    Moderator
    Rental Property Investor · Sioux Falls, SD · Member since 2015 · 9k+ posts · 18k+ votes
    6y

    Generation bashing is a long held American tradition.

    In the 1920's we saw the roaring 20's as a time of care free fun. It gave rise to the fun loving flappers and other jazz listening losers who later went on to become the "Greatest Generation".

    In the 1960s we had the hippies. Listening to horrible rock and roll while smoking weed. They are the "Baby Boomers" who many of you call Grandma and Grandpa today. 

    In the early 1990's we saw a generation of slackers have trouble finding jobs. Listening to punk, alternative music and grunge, this generation was the first raised with computers. Labeled "Generation X" this now aging generation was once the punching bag with movies like "Reality Bites" painting a horrible future.

    Here we are in almost 2020 and now "Millenials" are the generation that everyone likes to pick on. Good news for you millenials is that Generation Z is coming. Soon you will grow old, gain respect and this new generation will come of age to become the generational punching bag.

    In the mean time, just avoid reading articles like this. The only thing worse than these articles it the millenials who get offended. Who cares if someone slams your generation? There is over 80 million millenials and you are going to be personally offended - like this article was targeted at just you? 

  • San Antonio, TX · Member since 2019 · 930 posts · 836 votes
    6y

    Some people need to realize that if they want to live in an expensive market, they might have to make some sacrifices.

  • Rental Property Investor · Harrisburg, PA · Member since 2018 · 369 posts · 406 votes
    6y
    Originally posted by @Russell Brazil:

    I had about $100k in debt soon after I got out of school. I paid it all off before I was 30, without making over $70k a year, and that salary only when close to 30. I think my first job was about $30k at age 23. 

    I lived cheaply, had roommates, got side hustles. I didnt spend $50 on avocado toast, instead I went to cheap happy hours. All while living in 2 of the more expensive cities of Boston and DC. Paid it all off and saved for my first rentals. 

    We dont have a student loan crisis....we have a personal finance, spending, and consumerism crisis.

    Liked, and written in my notebook to be thrown at the next whiner!

  • Realtor · Seattle, WA · Member since 2019 · 117 posts · 165 votes
    6y

    Speaking as a millennial from Seattle, I have heard and listened to my friends who "can't" afford a house. The things I've noticed is that:

    1. They spare no expense when it comes to eating out, clothes, or vacations. Alcohol is so pricey, food is pricey, sales tax is one of the highest in the country 10.1%. 

    2. They spend a lot on rent. Which should be a reason to get into a house PRONTO...

    3. The competitive market deters them from even looking or getting pre-approved. When they finally do buy a house it is going to be a liability not an asset.

    They are not ignorant or uninformed(I've told my friends about FHA loans), they are just lazy and like living close to their work and paying the high rents, driving their nice cars, and buying new Patagucci every winter season. There is no sacrificing of comfort. They like it cushy.

    I have 5 houses in Seattle and I've been able to do that by buying fixers and working on them after I come home from my day job. The housing market isn't easy but it's doable. Sacrifice, hustle, these kids havent learned that.

  • Cheshire, CT · Member since 2018 · 87 posts · 60 votes
    6y

    I usually defend millennials as a millennial myself. I went to a stupid college that was hilariously expensive but walked away with comparatively little debt. Solidly against college now, unless you actually need it for your dream career. My wife and I own our own home and have a new baby. Tons of expenses and excuses, but not from where I sit.

    Since graduating 8 years ago, I have worked for 5 different companies. I went from $10 an hour to $38 an hour in that time. However my current commute is well over an hour one way. Because thats where my higher paying job is. Its what needs to be done.

    Most of my friends get by well enough, but have no sense of their finances. There are people like this in every generation. Most of America is shockingly average and would rather complain and spend then save for even a little while and live better on the other side.

    It might be callous, but let them. Millennials want to rent forever? Fine. That means that we will have tenants forever. You can lead a horse to water but you can't make the drink. In the age of the internet in your pocket at all times, how can you not look up a way to improve your own situation? 

  • Colleen F.Pro Member
    Investor · Narragansett, RI · Member since 2013 · 8k+ posts · 4k+ votes
    6y

    Great critique!  

    They cherry pick these people again talking about student loan debt.....  newsflash College is not for everyone but student loans were put in place to help people pay for an education to access opportunities they might not already have.  Here is the history of student loans.  https://lendedu.com/blog/histo…         They are there as an opportunity cost and have helped many people. I could not have gone to school without it.  I could half all their debt just tell them  all to stay home and go to school. It is a choice.

    The real issue here is a sense of personal responsibility. Her parents told her it was good debt. I bet her parents told her a lot of other things she didn't listen to.  You have to own where you are in life and weigh your choices.   My debt for school wasn't small even in todays terms but I would not have gone to college without it and it was worth it. I would never fault my parents for what I borrowed.  As for affording a home you do that when you can. I do remember those double digit interest rates so I believe there is a missed perception on how affordable things were. 

    The follow on in the article was quite good but the case cited... not so much. 

Join the conversationCreate a free account to reply, vote on answers and follow this thread.